



PW Consulting: ICU Equipment Market to Reach USD 13,227 Million by 2032 at 5.4% CAGR (2026–2032)

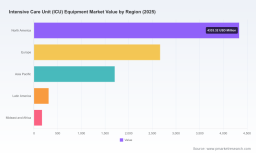
Intensive Care Unit (ICU) Equipment Market — Strategic Briefing for 2026 Decision‑Makers
Executive snapshot
Healthcare systems are entering a new phase of critical‑care modernization. After a period of accelerated investment and technological catch‑up, the global Intensive Care Unit (ICU) equipment market is set on a steady multiyear expansion. Our modeling — using 2025 as the base year and a forecast window spanning 2026–2032 — shows a continuation of growth at a compound annual growth rate (CAGR) of 5.4%. To put this into perspective, total market revenues expanded from approximately USD 7.28 billion in 2020 to about USD 9.18 billion in 2025 and are projected to reach roughly USD 13.23 billion by 2032.
Intensive Care Unit (ICU) Equipment Market
Why this research matters for 2026 corporate strategy
- Capital allocation and procurement timing: Hospitals and health systems will remain selective with high‑value ICU capex. This report provides the temporal demand patterns and adoption curves that inform whether to accelerate production, defer capacity expansions, or pursue asset-light servicing models.
- Product and portfolio prioritization: Suppliers face tradeoffs between continuing to invest in core ICU platforms (ventilation, hemodynamic monitoring, infusion systems, ICU infrastructure) and branching into adjacent software/connectivity services. Our scenarios show when incremental R&D investment yields disproportionate returns versus when market saturation favors aftermarket and service revenue.
- Regulatory and reimbursement stress‑testing: The interplay between device approvals, evolving clinical definitions of critical care, and reimbursement rules materially alters unit economics. Use our regulatory impact simulations to test product pricing, bundling and go‑to‑market strategies under alternate reimbursement assumptions.
- M&A and partnership scouting: Concentration metrics indicate a market structure where a small cohort of incumbents capture a sizeable share of revenues — creating attractive pockets for bolt‑on acquisitions and regional rollouts. Our buy/sell decision framework helps identify targets that shorten time‑to‑market or deliver complementary capabilities.
Data‑driven narrative (high level)
The market’s steady CAGR of 5.4% through 2032 reflects converging forces: aging populations, persistent high‑acuity cases, and steady replacement cycles for high‑utilization devices; counterbalanced by budget constraints and tighter reimbursement environments in several developed markets. Supply‑side pressures — notably higher spending on medical supplies broadly (an observed ~9.9% increase through 2025) and elevated labor and component costs — are compressing gross margins for new hardware launches. Meanwhile, regulatory updates such as ISO 10993‑1:2025 and shifting policy on how critical‑care services are defined and reimbursed are creating new compliance costs and, importantly, differentiation opportunities for firms that can quickly demonstrate safety and interoperability.
Intensive Care Unit (ICU) Equipment Market
What this report delivers (practical, operable intelligence)
- Macro market sizing and validated forecasts (base year 2025; forecast horizon 2026–2032) with scenario variants tied to capex cycles, pandemic/resurgence scenarios, and reimbursement shocks.
- Segment playbooks (product, application and region) that map adoption drivers, buying‑center economics, and deployment timetables — presented as decision matrices and actionable heat maps. Note: we intentionally omit granular segment figures in this briefing; the full tables and downloadable models are accessible through the report portal.
- Procurement and total cost of ownership (TCO) templates for hospitals, covering capital costs, consumables, service and labor impacts over multi‑year refresh cycles.
- Competitive benchmarking with SWOT profiles, technology roadmaps and home‑market strengths for the leading vendors, plus an M&A opportunities list and a prioritized partner shortlist.
- Regulatory and reimbursement impact analysis, including clinical coding sensitivities, pathways to 510(k) clearance, and risk mitigation checklists for ISO and biocompatibility compliance.
- Playbooks for product managers and BD teams: pricing simulations, launch sequencing recommendations, and a field rollout optimization model that minimizes inventory and service gaps.
Competitive landscape — what to watch in 2026
The market exhibits moderate concentration: the top three firms account for roughly 42% of revenue, and the top five about 48%. This structure rewards both scale and specialization. Key competitive dynamics covered in the report include the following profiles and strategic implications:
Intensive Care Unit (ICU) Equipment Market
- GE HealthCare (Chicago, IL) — a full‑suite critical care incumbent offering integrated monitoring, ventilation and diagnostic cardiology. Their strength lies in end‑to‑end clinical workflows and enterprise contracts; challengers should expect aggressive bundling and service offers where GE is present.
- Koninklijke Philips N.V. (Amsterdam) — focused on patient monitoring and connectivity solutions designed for ICU environments. Philips’ competitive advantage is interoperability and cloud‑enabled remote monitoring; rivals must match connectivity and cybersecurity credentials to compete on large tenders.
- Drägerwerk AG & Co. KGaA (Lübeck) — known for mechanical ventilation, respiratory monitoring and alarm management. Dräger’s deep clinical ventilation expertise makes them a prime partner for hospitals prioritizing complex respiratory cases.
- B. Braun Melsungen AG (Melsungen) — leading in infusion therapy, smart alarms and device interoperability. Their strengths are consumables and service networks — an important lever for locking in recurring revenue.
- ICU Medical (San Clemente, CA) — focused on infusion pumps, IV connectors, airway management and hemodynamic monitoring. ICU Medical is well positioned where safety‑focused consumable ecosystems matter.
- Mindray (Shenzhen) — a high‑velocity competitor in patient monitoring, ventilators and ultrasound systems. Recent product launches indicate a strategy to climb the value chain in high‑acuity settings.
- Nihon Kohden (Tokyo) — a patient monitoring and ventilation specialist with strong clinical adoption in Asia and select global markets.
- Getinge AB (Gothenburg) — focused on mechanical ventilators and ICU infrastructure; an important player where integrated infrastructure and OR/ICU refurbishments are procured.
Recent market signals reinforce a dynamic competitive field: new ventilator launches by established manufacturers and entrants, alongside a steady cadence of regulatory clearances for monitoring platforms. These events accelerate feature competition while driving customers toward complete systems that promise lower integration risk.
Industry dynamics and risk matrix
- Cost inflation and supply chain: Rising input costs across supplies and components are increasing unit costs and lengthening lead times. Procurement teams need hedging strategies (multi‑sourcing, longer contracts) and scenario TCO models to avoid margin erosion.
- Regulatory rigor: Updated clinical definitions of critical care and standards such as ISO 10993‑1:2025 increase pre‑market evidence requirements — favoring manufacturers with established clinical trial and assurance capabilities.
- Reimbursement complexity: Certain ventilator management codes remain tightly coupled with critical care billing constructs; product teams must design commercial models that reflect limited incremental reimbursement for device‑specific procedures in some geographies.
- Workforce constraints: Labor shortages and higher staffing costs change the economics of device usability — simple, low‑training devices and automation that reduce nurse burden will gain an adoption premium.
How senior leaders should use this intelligence in 2026
- CEOs and corporate strategy leads: Use our consolidation and concentration analysis to prioritize inorganic moves and to size the premium for platform deals that add recurring consumables or services.
- Product and R&D heads: Align product roadmaps to interoperability, safety evidence and ease‑of‑use. Allocate R&D to features that shorten hospital onboarding time and reduce nurse cognitive load.
- Commercial and BD teams: Reconfigure commercial models toward integrated offering bundles and outcome‑linked contracts where possible — especially in regions where reimbursement is fixed.
- Procurement and hospital leaders: Leverage our TCO templates and supplier scorecards to negotiate extended warranties, service level agreements and consumable commitments that reduce long‑term operating expenses.
Methodology, transparency and next steps
The analysis synthesizes historical data (2020–2025), primary interviews with hospital procurement leaders and manufacturers, and proprietary adoption models tuned to macroeconomic and reimbursement scenarios. The base year is 2025; forecasting spans 2026–2032 with sensitivity bands around the 5.4% CAGR baseline to reflect upside (accelerated technology substitution) and downside (reimbursement compression) cases.
In keeping with our “trailer” approach, this briefing highlights strategic conclusions and high‑level datapoints to guide boardroom discussion while preserving the granular segment tables, segmented forecasts, company financials and downloadable TCO models for subscribers. Detailed product‑by‑product and region‑by‑region forecasts, supplier scorecards, and the full dataset (including model inputs and scenario derivations) are available in the intensive study.
For strategy teams preparing 2026 budgets, procurement cycles or M&A screens, this report is designed to convert market foresight into specific actions: timing of launches, capacity commitments, bid strategies, and regulatory readiness. Contact our research desk or visit the report page to access the complete dataset, interactive dashboards and custom consulting engagements tailored to your 2026 priorities.
For detailed analysis of this topic, please visit the official page: Intensive Care Unit (ICU) Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


