



PW Consulting: Dashboard Camera Market Poised for 8.67% CAGR (2026–2032)

Dashboard Camera Market 2026: Strategic Preview for Enterprise Decision-Makers
As PW Consulting’s lead industry analyst, I present a forward-looking synthesis of the dashboard camera (dash cam) market designed to inform boardroom decisions throughout 2026. This is a strategic “trailer” — it surfaces the critical commercial, technological, and regulatory inflection points that will shape supplier economics, product roadmaps, and go-to-market plays across the 2026–2032 forecast horizon, while reserving the granular segmented tables and proprietary model outputs for the full report.
Dashboard Camera Market
Executive snapshot
The dashboard camera market has moved from niche accessory to core vehicle safety and telematics component. Our base-year analysis (2025) and historical window (2020–2025) show consistent expansion: the market grew steadily from its 2020 base and reached a sizable industry scale by 2025. Under current assumptions, the market is projected to expand through 2032 at a compound annual growth rate of 8.67%, reflecting accelerating adoption across consumer, commercial fleet, and OEM channels. Despite growth, the market remains relatively unconcentrated — a structural feature with important strategic consequences for entrants and incumbents.
Dashboard Camera Market
Why 2026 is a strategic inflection
- Regulatory momentum: New mandates and updated mounting/visibility rules are translating safety policy into procurement requirements for commercial operators and OEM platforms alike.
- OEM integration: Vehicle manufacturers are shifting from accessory partnerships toward built-in drive recorders as standard equipment on mainstream models, influencing the balance between aftermarket and factory-fit opportunities.
- Platformization and AI: Dash cams are no longer standalone recording devices; they are becoming sensors feeding AI-enabled risk detection, telematics platforms, and cloud services — changing the value capture model for vendors.
- Cost and supply pressure: Component and storage price inflation in early 2026 is forcing OEMs and aftermarket manufacturers to rethink sourcing, value engineering, and bundled service economics.
Market dynamics and core drivers
Our analysis segments demand drivers into four interacting vectors: regulation and compliance, fleet safety economics, consumer safety and convenience, and technology enablement.
Dashboard Camera Market
- Regulation: Legislative action requiring dash cams in commercial fleets has moved from discussion to statute in select jurisdictions — a pattern that tends to propagate across neighboring regions and industry associations. At the same time, vehicle-code updates on windshield-mounted devices continue to influence product form-factors and mounting solutions.
- Fleet economics: Total cost of ownership (TCO) improvements from incident reduction and faster claims resolution are motivating fleet operators to adopt multi-channel, cloud-connected solutions. Insurers and fleet managers increasingly view dash cams as risk-control investments rather than discretionary spend.
- Consumer adoption: Mainstreaming of driver-assistance features and demand for occupant protection have expanded the addressable market beyond enthusiasts to mass-market buyers — especially as OEMs offer integrated recorders in model lines.
- Technology and services: Advances in low-light sensors, edge AI for real-time event detection, and cloud workflow integration enable new monetizable features (driver coaching, automatic upload, telematics fusion), but they also raise privacy, cybersecurity, and data-governance requirements.
Competitive landscape: who matters and why
The competitive map is diverse: consumer-electronics brands, telematics/IoT platform players, specialist optics and sensor firms, and industrial-system integrators all compete for slices of hardware, software, and recurring-service revenues. Key strategic vectors we observe across core players include platform integration, AI-enabled analytics, and channel specialization.
- Garmin Ltd. (Olathe, KS): Leverages consumer brand recognition and an expanding portfolio of connected LTE models. Strengths include continuity of product experience, GPS expertise, and aftermarket distribution scale. Garmin’s connected offerings illustrate a hybrid hardware-plus-service approach that competes strongly in both consumer and small-fleet segments.
- Thinkware (Coquitlam, BC): Positions itself at the premium end with 4K recording, advanced optics, and AI-enabled parking modes. Thinkware’s product focus supports higher-margin propositions and appeals to safety-conscious consumers and light commercial buyers seeking superior image fidelity.
- Nextbase (Waterloo, UK): Demonstrates how a market leader in a major national market can combine award-winning product design with strong retail and online channels. Nextbase’s approach is instructive for brands targeting rapid consumer adoption while defending against commoditized low-cost imports.
- Samsara (San Francisco, CA): Exemplifies platform-first competition: dual-facing, AI-powered cameras integrated into a broader fleet management suite. Samsara’s model emphasizes subscription revenue, telematics integration, and real-time risk detection — a playbook for firms aiming to capture recurring service economics.
- VIOFO (Taiwan): Focuses on high-performance sensor packages (e.g., STARVIS 2) and multi-channel systems, targeting users demanding professional-grade capture. VIOFO illustrates how component excellence and price-performance balance can win enthusiast and specialist segments.
- IMAGO Technologies GmbH (Friedberg, Germany): Specializes in industrial-grade, trigger-based cameras for event capture and machine monitoring, bypassing continuous-recording paradigms. IMAGO’s product differentiation highlights opportunities where constrained recording modes reduce data overhead and regulatory exposure.
- FUHO Technology (Changhua, Taiwan): Builds on mobile DVR experience to deliver multi-channel fleet systems with IoT connectivity. FUHO’s strengths align with large fleet telematics and logistics operators that require integrated tracking and recording across multiple vehicle zones.
Collectively, these profiles show a market where hardware differentiation, service integration, and channel specialization are all viable pathways. Market concentration remains low, meaning nimble entrants can scale regionally or by vertical specialization — but they must select clear monetization strategies (one-time hardware, bundled service, or platform subscription) early.
Regulatory and cost risk vectors to monitor in 2026
- New mandates for dash cams in commercial vehicles in certain jurisdictions create immediate procurement demand, but also require suppliers to support compliance reporting and evidence retention workflows.
- Federal and state rules on windshield mounting and sightlines continue to alter preferred form-factors and installation kits.
- Material and component inflation — especially flash storage and certain optical components — pressures margins. Pricing strategies and supplier contracts must be revisited to protect gross margins while maintaining competitive price points.
- Data privacy and cybersecurity regulations are converging with vehicle safety laws, increasing the bar for secure cloud ingestion, retention policies, and lawful disclosure processes.
Strategic implications for enterprise leaders in 2026
For executives responsible for product, sales, procurement, or M&A, 2026 is the year to translate macro tailwinds into defensible positions. Below are high-leverage actions we recommend based on scenario analyses in the full study.
- Define your monetization thesis: Decide whether to compete on hardware margins, recurring platform subscriptions, or a hybrid bundling model. Players that delay this choice risk margin erosion from competing incentives across channels.
- Invest in regulated-compliant solutions: Rapidly deploy modular firmware and cloud workflows that support jurisdictional evidence retention and reporting requirements. Compliance is becoming a product feature that unlocks procurement in regulated fleets.
- Prioritize interface standards and partnerships: API-first integrations with major telematics and insurance platforms accelerate adoption. Strategic alliances (or white-label partnerships) with OEMs or fleet management providers can provide scale and lock-in.
- Hedge supply-chain exposure: Lock in storage and optical component capacity through multi-year contracts or alternative sourcing to mitigate short-term pricing shocks. Consider software-defined differentiation to reduce reliance on the most inflationary components.
- Differentiate by data services: Move beyond recording to deliver actionable insights (driver coaching, event triage, automated claims packages). The biggest recurring-revenue pools will belong to firms that own the analytics and workflow automation layer.
- Reassess channel economics: OEM-fit strategies change distribution math; aftermarket brands must compete on convenience, feature-upgradability, and post-sale services to keep lifetime value attractive.
- Prepare for regulatory-first competitive openings: Where local mandates appear, rapid response capability — compliant SKUs, installer networks, and proof-of-compliance feature sets — will determine who wins initial procurement rounds.
What the full PW Consulting Dashboard Camera Market report delivers
To support execution, our comprehensive study (base year 2025; historical 2020–2025; forecast 2026–2032) includes practical, operator-ready deliverables:
- Market-size modeling with scenario runs (conservative, base, accelerated) and sensitivity to regulatory adoption rates and component-price trajectories.
- Go-to-market playbooks for OEM partnerships, fleet procurement programs, and consumer retail strategies.
- Technology roadmaps mapping sensor evolution, edge AI maturity, and cloud-telemetry integration timelines.
- Competitive profiling and a prioritized matrix of potential acquisition targets and alliance partners.
- Supply-chain risk maps and procurement levers to manage storage and component cost volatility.
- Commercial negotiation templates for licensing, data rights, and recurring-revenue arrangements.
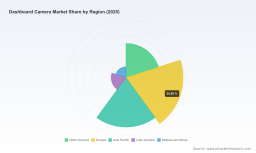
We intentionally omit granular regional and application share tables from this preview. Those detailed segmentations, priced models, and downloadable data sets are included exclusively in the full report and interactive dashboard — because the highest-value decisions depend on precise, proprietary splits and scenario-calibrated unit economics.
Immediate next steps for leaders
- Use the next 60–90 days to finalize your monetization position and prioritize product compliance features aligned to your target markets.
- Audit supplier contracts for storage and optical components; implement hedges where exposure is highest.
- Identify at least one strategic partnership or OEM engagement to pilot built-in solutions or managed-service bundles in 2026.
- Request the full PW Consulting Dashboard Camera Market report for executable playbooks, vendor scorecards, and the granular forecasts needed to build FY-2027 budgets and capex plans.
PW Consulting’s 2026 market intelligence is designed to move you from insight to action. The macro trajectory — sustained mid-single-digit-to-high single-digit CAGR through 2032 — creates meaningful upside, but translating that growth into sustainable profits will require explicit choices around product architecture, channel economics, and data ownership. Our full report supplies the segmented data and operational tools your team needs to make and implement those choices with confidence.
For detailed analysis of this topic, please visit the official page: Dashboard Camera Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


