



PW Consulting: Spherical Activated Carbon Market to Hit USD 201.5M by 2032 at 6.2% CAGR

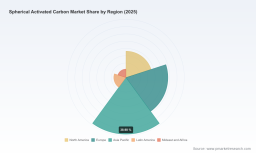
Spherical Activated Carbon Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive primer on our new Spherical Activated Carbon (SAC) market study — a focused, action-oriented body of work designed to inform high-stakes commercial and investment decisions in 2026. The sector is at a structural inflection: demand across environmental remediation, ultrapure processes and advanced materials is rising, input-cost volatility is creating margin pressure, and a concentrated supplier base is shaping competitive dynamics. This article summarizes the strategic takeaways and explains why our study should be on the desk of every CEO, Chief Procurement Officer, and M&A lead weighing SAC exposure this year.
Spherical Activated Carbon Market
Market trajectory and what it means for 2026 planning
Our market model — built on a validated historical series and forward-looking scenario analysis — shows steady expansion through the coming decade. After recovering from early-decade variability, the SAC market reached a solid position in our base year (2025) and is forecast to continue growing at a mid-single-digit compound annual growth rate (CAGR) through the 2026–2032 horizon. By 2032 the market is meaningfully larger than in 2025 under our central case, driven by persistent demand in industrial adsorption, advanced water and gas purification, and specialty electronic and biomedical uses.
Spherical Activated Carbon Market
For 2026 strategic planning, the implication is clear: companies must balance near-term operational resilience with medium-term capacity and product strategy. Cost shocks and regulatory tightening in certain applications will compress margins for commodity-oriented products, while high-value niches — particularly those requiring ultra-low dust, controlled particle distribution, and certified purity — will offer asymmetric return profiles for firms that can execute technically and commercially.
Spherical Activated Carbon Market
How this study helps you act — a practical content map
- Robust market sizing & scenario modeling: A base-year calibration and multiple demand scenarios through 2032 that permit sensitivity testing against input-cost swings and adoption curves.
- Segment-level analysis (by type, application, and region): Deep diagnostic of end-market drivers and adoption dynamics. Note: while this primer highlights directional trends, detailed segment tables and model outputs are available in the full report.
- Supply chain and raw material risk assessment: Granular coverage of feedstock sources (coal, petroleum pitch, resin, bio-precursors), pricing volatility, and alternative sourcing strategies.
- Competitive landscaping: Comparative profiles, capability mapping, and a commercial scorecard of leading producers — focusing on product tech, scale, end-market focus, and strategic moves.
- Commercial playbooks and investment thesis: Actionable guidance for procurement, product roadmap prioritization, strategic partnerships, and M&A scenarios with illustrative valuation sensitivities.
- Regulatory & standards matrix: Practical implications of evolving environmental and purity regulations for product design, certification, and capital planning.
Competitive landscape: who matters and why
The SAC market is neither a fragmented cottage industry nor a closed oligopoly — it sits in the middle. Our concentration metrics show that the top three players capture a material share of supply, and the top five increase that concentration further. That structure creates both opportunity and risk: scale advantages in cost and distribution exist, yet niche technical differentiation remains achievable for agile specialists.
- Kureha Corporation (Tokyo, Japan) — A technology-focused supplier whose petroleum pitch–based spherical grades emphasize high purity, low dust and flowability. Kureha’s strengths are in process control and end-market credibility for environmental applications; it is well-positioned where regulatory requirements penalize dust-prone or variable-grade products.
- Osaka Gas Chemical Group (Tokyo, Japan) — Known for coal-based spherical carbons tailored for gas and liquid phase adsorption. The company’s product engineering and longstanding relationships in gas-treatment make it a pivotal player in industrial gas recovery and emission-control segments.
- Kuraray Co., Ltd. (Osaka, Japan) — Offers low-pulverization spherical products and is part of a broader family with historical ties to larger activated carbon players. Kuraray’s differentiation is technical consistency and access to cross-sector distribution channels via its corporate group.
- Shanxi Xinhua Chemical (Taiyuan, China) & Jining Carbon Group (Jining, China) — Representative of China-based suppliers scaling pitch- and coal-derived spherical grades for air purification and industrial recovery. Their cost-competitive production and proximity to regional demand centers give them logistical advantages, though customers increasingly require third-party certifications for export-grade applications.
- Acro Chemical Corporation (United States) — A niche pitch-based supplier serving specialty chemical and material applications where bespoke particle characteristics matter.
- Xiamen All Carbon Corporation (ACC) (Xiamen, China) — A notable growth story: ACC has broadened commercial availability of next-generation resin-based spherical products targeting semiconductor, ultrapure water, supercapacitors and hemoperfusion. This product expansion is illustrative of the premium opportunities available to companies that can deliver tight specs at scale.
Taken together, the competitive map suggests two viable strategic postures for companies in 2026: (1) invest behind premium, specification-driven offerings that command higher margins and resilient demand, or (2) compete on cost and supply assurance for larger, more price-sensitive industrial uses. Many firms will combine both via product-tier segmentation and selective partnerships.
Raw material and regulatory dynamics shaping 2026 decisions
Three interlocking external dynamics should be at the top of every boardroom agenda:
- Feedstock volatility: Prices and availability for key raw materials — Australian coking coal for certain coal-based grades, coconut shell for bio-based activated carbons, and petroleum pitch for pitch-based SAC — have shown episodic volatility. Recent commodity movements and weather-related supply disruptions highlight the need for multi-sourcing strategies, hedging where feasible, and contract clauses that balance risk across the value chain.
- Product specification trends driven by regulation: Environmental and public-health regulations increasingly favor spherical grades with low pulverization and predictable flow properties. Gas-phase and wastewater treatment standards are trending toward performance requirements that effectively penalize low-quality or high-dust carbons.
- Technology-led demand pockets: Semiconductor fabs, ultrapure water systems, supercapacitors and medical devices (e.g., hemoperfusion) are growing end-markets for specialized spherical carbons. These applications reward suppliers that can demonstrate consistent particle size distributions, low ionic contamination and validated production control systems.
For procurement and product teams, the strategic implications are immediate: prioritize qualified supplier portfolios for critical feedstocks; invest in process controls and certification capabilities; and design commercial contracts that reflect asymmetric risks in feedstock and logistics.
Strategic actions for 2026 — a pragmatic checklist
- Run a rapid stress-test of your SAC-exposed P&L versus commodity and regulatory scenarios using the study’s model framework.
- Assess whether your product portfolio is aligned to high-margin niches (ultrapure, medical, electronic) and what incremental CAPEX or R&D would be required to up-spec existing lines.
- Build redundancy into feedstock sourcing; evaluate nearshoring or strategic backward-integration where long-term supply tightness is probable.
- Prioritize certification and quality documentation for export markets and regulated end-uses — compliance can be a commercially differentiating asset.
- Consider M&A and JV plays to secure technology, distribution or regional manufacturing footholds; concentration metrics indicate that well-targeted consolidation can accelerate scale benefits.
Why PW Consulting’s study is different
Our study is tailored for decision-makers who need to act in 2026. It combines a transparent, auditable market model with qualitative diagnostics and executable playbooks. Beyond high-level forecasts, the report includes supplier scorecards, regulatory heatmaps, contract-risk templates, and scenario-driven valuation workups — the tactical materials that procurement, corporate development and product leadership can use immediately.
We intentionally maintain a “trailer” approach in this primer to preserve the strategic utility of the complete analysis: detailed segment tables, company-level revenues, split-by-application forecasts, and the full sensitivity matrix are available in the main report and interactive model. These deliverables are essential for market-entry sizing, target prioritization in M&A, and contractual negotiation simulations.
Call to action
If your 2026 plan touches activated carbon — as a producer, buyer, investor or technology partner — this is a moment to upgrade insight to action. Use the study to stress-test your assumptions, prioritize investments, and design resilient supply chains and premium product strategies. Contact our research desk to access the full report and the underlying model so your team can run customized scenarios and extract the precise segment-level intelligence needed to seize value in the evolving SAC market.
For detailed analysis of this topic, please visit the official page: Spherical Activated Carbon Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


