



PW Consulting: Silage Corn Seed Market to Reach USD 344.8 Million by 2032 at 7.21% CAGR

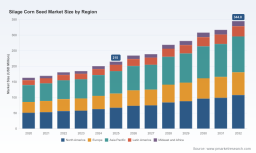
Silage Corn Seed Market — Strategic Preview for 2026 Decision-Makers
As global dairy and livestock systems face mounting pressure to improve feed efficiency, lower production costs, and mitigate climate risk, the silage corn seed market stands at a strategic inflection point. Our latest PW Consulting study — built on a 2020–2025 historical base and forward-looking to 2032 — shows the market expanding at a compound annual growth rate of 7.21%. The research synthesizes macro sizing, scenario-driven forecasts, supplier positioning, cost and regulatory shocks, and practical playbooks that companies must adopt to convert growth into profitable share gains in 2026 and beyond.
Silage Corn Seed Market
Why this report matters for 2026
-
Timing: 2026 is the first full planning year after multiple 2025 product launches and regulatory updates that materially affect seed development, risk management, and field economics. Boards and commercial leaders must translate these near-term changes into 3–5 year plans now.
Silage Corn Seed Market -
Market trajectory: The market’s steady historical growth combined with an above-average forecast trajectory implies both continued demand and heightened competitive intensity. Strategic moves in R&D, channel coverage, and pricing executed in 2026 will disproportionately shape outcomes for the remainder of the decade.
Silage Corn Seed Market -
Concentration dynamics: Market concentration at the top tier remains high, creating asymmetric opportunities. Established leaders can leverage scale and trait portfolios, while challengers can win by narrowing focus and exploiting gaps in innovation or service.
What the PW Consulting report delivers (practical, executable content)
-
Robust market architecture: a clear articulation of demand drivers, cost pressures, and adoption levers across the value chain, with modeled scenarios that stress-test pricing, yield, and trait-penetration assumptions.
-
Actionable commercial playbooks: segmented go-to-market options for seed houses and distributors, including prioritized channel investments, differentiated product messaging for dairy vs. beef systems, and farm-level ROI calculators to increase adoption.
-
R&D and product strategy guidance: a diagnosis of trait gaps and breeding priorities (e.g., digestibility, drought tolerance, BMR variants, and gene-edited traits), recommended investment pacing, and partnership archetypes for co-development or licensing.
-
M&A and partnership scorecards: framework for evaluating targets by asset type (germplasm, trait stack, distribution footprint), with sensitivity analyses showing how different deal structures affect short- and long-term return profiles.
-
Commercial risk matrix: regulatory and insurance shifts, supply-chain fragilities, and farm economics translated into contingency playbooks for price shocks, seed shortages, or rapid trait adoption.
Competitive landscape — what to watch in 2026
The market is dominated by a small number of global R&D leaders with deep hybrid pipelines, broad distribution networks, and the capital to commercialize advanced trait packages. That said, a vibrant mid-market and regional specialist cohort remain strategically important — both as customers (through licensing or distribution partnerships) and as acquisition targets.
-
Bayer CropScience: Continues to push breeding advances and has moved into gene editing for drought resilience. Expect Bayer to lean into trait differentiation and stewardship programs that help translate genetic advances into demonstrable on-farm value.
-
Corteva Agriscience: With a broad hybrid portfolio and strong channel relationships, Corteva’s pathway to growth emphasizes integrated trait stacks and farm-centric data services that increase stickiness across the growing season.
-
Syngenta: Focused on digestibility-optimized lines and energy-efficient hybrids; Syngenta’s near-term bets will be on partnerships and co-branded products that accelerate adoption in dairy-intensive geographies.
-
KWS, Limagrain, Brevant, Maizex, Hybrid85 and other regional players: These firms compete on niche specialization — forage-centric breeding, non-GMO portfolios, or value pricing and direct shipping. Their agility and local knowledge make them credible challengers in defined segments.
Recent 2025–early-2026 developments reflect this dynamic: new hybrid launches across multiple firms, drought-tolerant gene-edited lines coming to market, and distribution partnerships that increase route-to-farm reach. Taken together, these signals point to faster product turnover and a higher premium on commercialization excellence.
Cost, regulation and operational dynamics shaping 2026 choices
-
Input cost pressure: Field-level economics are shifting. For 2026, industry averages show a step-up in per-acre planting costs compared with 2025. Management teams must account for this when designing price-pack structures and farmer financing offers.
-
Insurance and regulatory flux: The USDA Risk Management Agency’s updated standards and new pilot insurance programs approved in late 2025 change the risk calculus for both farmers and seed firms. Companies should model the impact of these programs on adoption risk and stocking strategies.
-
Seed unit economics: Kernel-level breeding and scaling efficiencies, including cost per 1,000-kernel metrics in major production geographies, are now core inputs to pricing models and inventory decisions.
Strategic implications and recommended 2026 priorities
Companies that treat 2026 as a pivot year — aligning portfolio, go-to-market, and capital allocation decisions to a mid-term (2028–2030) value capture view — will outperform. Below are prioritized actions for executive teams.
-
Prioritize product-to-market velocity. Compress the commercialization funnel for proven trait packages by reallocating marketing and trial resources toward the highest-response geographies and channels. Fast-follower models that shorten shelf-to-farm time will capture disproportionate share.
-
Rebalance pricing and packaging. With farm-level planting costs elevated, experiment in 2026 with conditional pricing (e.g., performance rebates, split-payment structures, bundled agronomic services) to reduce perceived adoption risk while protecting margins.
-
Make targeted R&D bets plus external leverage. Divide R&D spend between core long-lead breeding and near-term gene-editing or trait-acceleration investments. Complement internal work with structured licensing and co-development to derisk time-to-market.
-
Strengthen distribution economics. Reassess distributor incentives and direct-to-farm capabilities; investments in digital ordering, logistic optimization, and seed-finance products can materially increase farmer loyalty and margin capture.
-
Use M&A strategically. Pursue tuck-ins that enhance trait breadth or regional coverage, and consider bolt-on acquisitions that instantly upgrade commercial capacity rather than purely germplasm consolidation.
-
Plan for regulatory and insurance permutations. Build scenario models that incorporate the updated crop-insurance standards and pilot programs, and design commercial offers that align with farmer risk-management choices.
How this preview is designed to spark action — and what is reserved for the full study
This article is intentionally structured as a strategic “trailer”: it surfaces the key directional forces, competitive moves, and executive-level recommendations that should shape 2026 planning. The full PW Consulting Silage Corn Seed Market report contains the granular inputs and proprietary models that drive these conclusions — including regional demand curves, type- and application-level adoption scenarios, company benchmarking scorecards, investor-ready financials, and downloadable ROI tools for field trials.
Concretely, the full study provides:
-
Model spreadsheets that allow users to run their own sensitivity tests against price, yield, and trait-penetration assumptions.
-
Detailed competitor dossiers and GTM mapping that uncover white-space opportunities within and between geographic clusters.
-
Step-by-step commercialization templates for launching new hybrid lines, including trial design, farmer engagement, and distributor incentive mechanics.
Final note to executives
As the silage corn seed market scales, the window to secure advantaged positions narrows. 2026 will reward companies that combine disciplined capital allocation, sharper commercialization, and flexible risk-management solutions for farmers. Our research quantifies the market’s trajectory, unpacks the near-term shocks, and prescribes the operational moves that convert macro growth into durable competitive advantage. For teams preparing budgets, M&A pipelines, or product roadmaps for 2026, this study is the strategic backbone that turns insight into implementation.
PW Consulting remains available to walk leadership teams through a tailored briefing of our findings, run custom scenarios on your portfolio, and co-develop a 90–180 day execution plan aligned to your ambition in this evolving market.
For detailed analysis of this topic, please visit the official page: Silage Corn Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


