



MALDI-TOF Market Poised for 6.98% CAGR — PW Consulting Insight

MALDI-TOF Mass Spectrometer Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I prepared this market briefing to orient senior executives, corporate development teams, and institutional buyers on why our 2026 MALDI-TOF Mass Spectrometer Market study is a practical must-read for near-term strategy. The market is both mature in core clinical applications and rapidly evolving at the intersection of diagnostics, research, and environmental analysis. Our study synthesizes historical performance (2020–2025), establishes a rigorously modeled 2026–2032 forecast horizon, and translates those inputs into actionable decision frameworks that preserve optionality while accelerating value capture.
MALDI-TOF Mass Spectrometer Market
Headline market context — growth, scale, and concentration
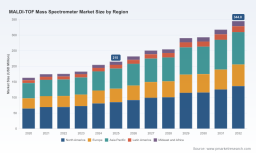
Key quantitative takeaway: the global MALDI-TOF market shows a sustained recovery and expansion phase. From a documented base in 2020, the market rose steadily through 2025 and is forecast to continue growing through 2032 at a compound annual growth rate (CAGR) of 6.98%. In practical terms, this trajectory underpins a multi-year runway for suppliers and service partners to scale revenues, invest in adjacent workflows (software, consumables, and assays), and pursue international reimbursement and regulatory strategies.
MALDI-TOF Mass Spectrometer Market
Market concentration is moderate: the leading three vendors account for a meaningful share of market revenue, while the top five widen that reach further — a structure that creates oligopolistic dynamics for instrument pricing but open fields for differentiated consumables, software, and application-specific service models.
MALDI-TOF Mass Spectrometer Market
Why this study matters for 2026 strategy
- Risk‑calibrated investment planning: The report’s 2026–2032 forecast (base year 2025) and scenario stress-tests quantify upside and downside cases tied to reimbursement shifts, regulatory milestones, and capital procurement cycles. This enables CFOs and portfolio managers to align CAPEX commitments to probabilistic revenue pathways rather than single-point estimates.
- Commercial prioritization: Rather than a static market map, our assessment layers competitive positioning, product maturity, and service economics so commercial leads can prioritize segments where early margin expansion is plausible within the next 18–36 months.
- Regulatory and reimbursement playbooks: The report translates regulatory changes and reimbursement signals into tactical actions — from timeline-driven CE-IVD adoption in EU markets to the operational implications of newly established CPT codes in the U.S. — helping market participants accelerate clinical acceptance while managing compliance risk.
- M&A and partnership intelligence: By combining market size trajectories with concentration metrics and vendor profiles, corporate development teams can identify acquisition sweet spots — bolt-on service providers, niche consumables manufacturers, and software firms that materially improve lifetime customer value.
What the report contains — practical deliverables
- Comprehensive market sizing and validated historical series (2020–2025) with a 2026–2032 forecast model and sensitivity scenarios.
- Vendor benchmarking and competitive scorecards that go beyond product lists to evaluate go-to-market models, installed base health, service economics, and channel strategies.
- Regulatory and reimbursement impact matrix with country-level milestones, expected adoption curves, and decision triggers for market entry or withdrawal.
- Consumables and services economics: unit economics, margin pools, and sample throughput models that convert instrument sales into recurring revenue forecasts.
- Procurement playbooks for hospitals, public agencies, and private labs — including specification checklists, validation timelines, and total cost of ownership (TCO) templates calibrated to realistic throughput bands.
- M&A heatmaps and integration checklists oriented to scale efficiencies in manufacturing, R&D, and service delivery.
- Appendices with methodology, primary interview transcripts, and a gated dataset for clients who require the raw figures behind segmentation and scenario inputs.
Competitive landscape — what to watch among incumbent and emerging suppliers
Our analysis profiles established instrument vendors and emergent specialists, assessing not only product roadmaps but also business model resilience (services, reagents, and software). Key players covered include:
- Bruker Corporation — A market stalwart with a strong clinical portfolio focused on systems tailored to microbiology and translational research. Their installed base in clinical settings makes them central to any interoperability or lifecycle service play.
- bioMérieux — A leader in clinical microbiology with product positioning that leverages rapid microbial ID workflows. Expect continued emphasis on validated clinical assays and laboratory automation partnerships.
- SCIEX — A player emphasizing advanced MALDI-TOF/TOF capabilities for proteomics, tissue imaging, and specialized surface profiling. Their offerings are attractive to translational and academic research customers willing to pay for high-end analytical performance.
- JEOL Ltd. — Focused on imaging and broad analytical applications; their spiral TOF architectures and instrumentation variants are positioned toward research and specialized industrial analytics.
- Shimadzu Corporation — A broad-spectrum supplier whose product range targets routine laboratory workflows. Notably, Shimadzu’s MALDI-8000 Series earned an industry-first environmental certification in 2025, an early indicator that sustainability credentials are becoming a commercial differentiator.
- Agena Bioscience — A niche player with platforms optimized for nucleic acid analysis and genetic testing; attractive as a bolt-on for molecular diagnostics routes-to-market.
Our vendor profiles look beyond product specs to analyze installed-base dynamics, service revenue potential, strategic partnerships, and provenability — i.e., how effectively an OEM can demonstrate clinical utility and cost-savings to hospital procurement committees.
Regulatory, reimbursement, and procurement dynamics shaping 2026
- Reimbursement shifts: The establishment of dedicated CPT codes for MALDI-TOF-based pathogen identification in the U.S. removes a historical billing barrier and is expected to accelerate hospital adoption where ROI is demonstrable.
- Regulatory inflection points: Full implementation of the EU IVDR framework and national approvals (e.g., new clinical assay panels in Japan) create both hurdles and commercial opportunities; vendors with CE-IVD or equivalent-clearance roadmaps will gain first-mover adoption in regulated clinical environments.
- CapEx signals: Public-sector procurement forecasts and bench-top procurement cycles (including government forecasts for replacement/maintenance spend) indicate windows where enterprise sales teams should intensify RFP engagement.
- Operational economics: Consumable spend is non-trivial for busy clinical labs and should be included in TCO assessments. Our study provides ranges and sensitivity models to help procurement teams quantify recurring spend and to help vendors design consumables bundles that improve retention.
Strategic imperatives for 2026
- Design for recurring revenue: Instrument sellers who sharpen their consumables, software, and service bundles will materially outpace those relying on one-time equipment sales. Our modeling shows sizable margin lift from even modest consumable attach rates.
- Regulatory-first commercialization: Prioritize clinical validations and CE-IVD/IVDR alignment in your product roadmap. Where reimbursement pathways exist, be ready with health-economic dossiers demonstrating shortened time-to-result and cost-per-diagnosis benefits.
- Channel and partnership engineering: Build partnerships across lab automation vendors, clinical informatics platforms, and regional distributors to lower adoption friction. Consider service franchises or certified third-party maintenance as a competitive lever in regions with price-sensitive purchasing.
- Sustainability as competitive edge: Certifications and lower lifecycle environmental impact are increasingly visible procurement criteria. Early adopters of certified “green” hardware or consumables will convert new buyer segments in public institutions and pharmaceutical partners.
- M&A selective playbook: Target acquisitions that accelerate access to recurring revenue (reagents, software) or fill critical gaps in assay libraries and clinical validations.
Uncertainties and scenario planning
Key upside drivers include faster-than-expected adoption in high-throughput clinical labs and expanded reimbursable indications. Downside risks include protracted regulatory timelines in major markets, material-cost inflation impacting consumable margins, and competitive pressure from alternative analytical platforms. Our report provides scenario layers that map these risks to P&L impacts across multiple timelines.
Next steps — how to use this briefing in 2026 planning
This briefing is intended to orient your executive team and set priorities for strategic planning cycles. For teams preparing 2026 budgets, procurement strategies, or M&A pipelines, our full study contains the granular segmentation tables, vendor financial proxies, and a gated dataset required to finalize investment memos and RFP responses.
PW Consulting’s full report couples the qualitative insights summarized here with the detailed figures that matter in boardroom decisions — from unit economics and regional adoption curves to product-level forecasts and sensitivity analyses. To access the full dataset, vendor scorecards, and the procurement playbooks referenced above, please consult the report page on our site.
For detailed analysis of this topic, please visit the official page: MALDI-TOF Mass Spectrometer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


