



Wireless Broadband to hit USD 404M by 2032 at 13.5% CAGR — PW Consulting

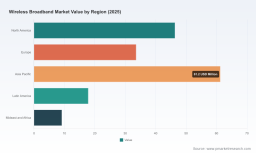
Wireless Broadband Market — Strategic Outlook for 2026
As organizations recalibrate connectivity strategies in an era defined by private 5G, fixed wireless access, and spectrum reshuffling, PW Consulting’s Wireless Broadband Market study is designed to inform the high-stakes decisions you will make in 2026. The market’s macro trajectory is clear: having expanded from roughly USD 96.7 million in 2020 to USD 168.0 million in 2025, the sector is expected to continue a sustained growth path — reaching an estimated USD 195.3 million in 2026 and accelerating to about USD 404.0 million by 2032 at a compound annual growth rate (CAGR) of 13.5% over the forecast horizon. This briefing explains why those headline numbers matter for strategy, what the research delivers, and how to translate insight into action — while intentionally reserving the report’s granular segment-level intelligence for the full publication.
Wireless Broadband Market
Why this study is strategically material for 2026
-
Investment timing and capital allocation: With a mid-teens CAGR and clear inflection points across 2026–2032, executives need market-backed scenarios to prioritize capex vs. opex, spectrum investments, and infrastructure rollouts.
Wireless Broadband Market -
Vendor and partner selection: The ecosystem spans global infrastructure vendors, CPE manufacturers, and service providers; nuanced vendor profiles and competitive dynamics determine negotiation leverage and partnership architectures.
Wireless Broadband Market -
Regulatory-driven opportunities and risks: Policy changes and auctions scheduled in 2026 materially affect access to spectrum and deployment economics for utilities, enterprise campuses, and service providers.
-
Use-case prioritisation: From critical communications to remote monitoring and consumer FWA, selecting which applications to prioritize determines technology roadmaps and monetization strategies.
Reading the macro numbers — what the trajectory implies
The market’s expansion from 2020–2025 and the projected doubling through the early 2030s reflect several converging forces: accelerated private and public 5G deployments, broader adoption of Fixed Wireless Access (FWA) in underserved geographies, and densification through small cells and mmWave trials. The uplift between the 2025 base year and 2026 indicates that near-term catalysts — including spectrum reallocations, successful operator mid-band deployments, and enterprise trials — are already translating into commercial momentum. For strategic planners, the 13.5% CAGR signals both robust addressable demand and intensifying competitive pressure, requiring earlier clarity on go-to-market models and differentiated service propositions.
What this report delivers — practical, decision-ready outputs
-
Robust market sizing and trend maps (historical 2020–2025; forecast 2026–2032), with scenario variants to stress-test conservative, base, and aggressive adoption paths.
-
Probability-weighted forecasts and a sensitivity toolkit to quantify how spectrum availability, permitting reforms, or a major vendor win/loss could change outcomes.
-
Actionable go-to-market frameworks for operators, system integrators, and enterprise IT teams — including market-entry checklists, partner archetypes, and procurement playbooks.
-
Investment-grade vendor dossiers and a competitive scorecard that synthesizes capabilities across radio, core, CPE, systems integration, and managed services.
-
Deployment case studies and trial summaries that translate technical performance into commercial KPIs and total cost of ownership (TCO) models.
-
Regulatory impact assessment and an advocacy roadmap that links policy shifts to practical deployment pathways for critical infrastructure and enterprise campuses.
-
Risk matrices, adoption inhibitors, and mitigation strategies for supply chain constraints, interoperability gaps, and security/operational resilience.
Note: The full report contains the detailed regional, type, and application splits that underlie the headline forecasts. Those granular datasets and proprietary segment models are intentionally not disclosed in this preview and are available in the full publication.
Competitive landscape — positioning and implications
The market shows a moderate level of concentration, with the top three players accounting for a meaningful portion of commercially-active deployments and the top five nearing half of the competitive footprint. This structure creates room for both scale-driven incumbents and specialist challengers to capture value through differentiation.
-
Ericsson (Stockholm) : Strong in 5G FWA hardware, radio and core. Recent mmWave extended-range trials and strategic private 5G partnerships demonstrate Ericsson’s push to convert proof-of-concept momentum into enterprise-grade offerings. Expect Ericsson to continue leveraging operator relationships to scale FWA and private network projects across both consumer and enterprise verticals.
-
Nokia (Espoo) : Focused on CPE and network platforms for both residential and enterprise deployments. Nokia’s recent private 5G deployment for a municipal utility underscores its positioning in grid modernization and industrial verticals — an area where long-term service and lifecycle revenue can be captured.
-
Huawei Technologies (Shenzhen) : Offers integrated RAN and core platforms globally. While market access varies by geography, Huawei’s breadth of product capability keeps it competitive where regulatory conditions allow, particularly in large-scale infrastructure projects.
-
Cisco Systems (San Jose) : Targets enterprise use cases with private 5G platforms and integrated IoT services. Cisco’s strength in networking and enterprise services positions it to hybridize wireless and wired ICT architectures for large enterprises.
-
Major US operators — T-Mobile US, Verizon, AT&T : These operators have operational 5G FWA offerings and continue to use mid-band spectrum to densify capacity. Recent large-scale site upgrades and spectrum deployments indicate an ongoing strategic bet on consumer and small-business fixed-wireless monetization.
-
Inseego (San Diego) : Focused on CPE devices for FWA. Device manufacturers like Inseego are critical enablers of deployment economics and user experience — areas where differentiation impacts adoption speed and churn.
Strategic takeaway: incumbent vendors will continue to compete on scale, ecosystem breadth, and operator relationships, while smaller specialists and systems integrators will win by focusing on verticalized solutions and integration-led services.
Regulatory and market dynamics you must factor into 2026 plans
-
Policy shifts: The reclassification of broadband internet access and subsequent regulatory clarity reduced one axis of uncertainty, but new rulemaking and auction timelines create fresh decision points for spectrum-dependent strategies.
-
Spectrum access: Expansions of access in bands like 900 MHz for utilities and the imminent AWS-3 auction (commencing June 2, 2026) materially influence private network feasibility and long-haul wireless economics.
-
Permitting and infrastructure: Federal proposals to streamline tower and small cell permitting accelerate deployment timelines for densification strategies, improving the business case for mmWave and small-cell heavy architectures.
-
Operational readiness: Utilities and critical infrastructure actors are being explicitly enabled via regulatory channels — making energy/utility verticals attractive early-adopter targets for private wireless solutions.
Use cases and technology enablers to prioritize
Operational planners should prioritize solutions that map clearly to near-term monetizable use cases: critical communications, remote monitoring and surveillance, and enterprise connectivity for distributed sites. Technology enablers — private 5G, mmWave extended-range, advanced CPE, and integrated edge compute — should be evaluated not as isolated line items but as bundled platforms that convert performance into measurable business outcomes (reliability, latency, security, and TCO).
How to use the report in 90 days
-
Week 1–2: Align executive stakeholders on macro scenarios and validate which adoption path (conservative/base/aggressive) matches your risk appetite.
-
Week 3–6: Use the vendor scorecards and procurement playbooks to shortlist partners and test commercial models with realistic ROIs from the report’s financial templates.
-
Week 7–12: Run a pilot informed by the deployment case studies, measure against the report’s KPIs, and commit to scale or iterate based on performance and regulatory developments.
Next step — get the full intelligence
This briefing has surfaced the strategic levers and market context that should shape 2026 decisions. For procurement-grade models, full regional and application-level splits, vendor benchmarking detail, and the proprietary scenario engine that underpins the forecast, access to the complete report is required. PW Consulting’s full Wireless Broadband Market study provides those datasets and actionable tools to convert the market’s growth trajectory into defensible, revenue-generating strategy.
For detailed analysis of this topic, please visit the official page: Wireless Broadband Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


