



PW Consulting: Variable Optical Attenuators Market to Reach USD 2,039M by 2032 at 9.8% CAGR

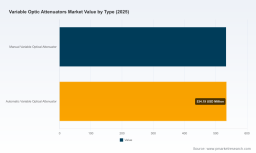
Variable Optic Attenuators Market — Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a strategic primer designed to orient executive teams, corporate development groups, and product planners to the critical inflection points shaping the Variable Optic Attenuators (VOA) market as they prepare plans for 2026. This preview synthesizes the quantitative market trajectory, the technology and supply‑chain forces at play, and the competitive moves that will determine who captures value in the next wave of optical networking and sensing investments. It intentionally highlights analytical depth while reserving detailed segment-level figures for the full market study — a deliberate “trailer” to encourage deeper read‑through of our complete report.
Variable Optic Attenuators Market
Macro snapshot: growth profile and market scale
Through methodical modeling using a 2025 base year and a historical window that spans 2020–2025, PW Consulting projects the VOA market to continue expanding robustly through the 2026–2032 forecast horizon at a compound annual growth rate (CAGR) of 9.8%. The industry has moved from early recovery into structural growth driven by several converging trends in telecommunications, data centers, sensing and test equipment. By 2026 the market steps into a new growth band that accelerates investment in higher‑precision and integrated attenuation solutions, and by the latter part of the forecast horizon the market crosses the multi‑billion dollar threshold (USD, revenue unit: Million). This is not a fad: the growth path is broad‑based across use cases and geographies, even as competitive intensity and supplier strategies differ by sub‑segment.
Variable Optic Attenuators Market
Why this matters for 2026 strategy
- Timing of capital allocation: With near‑double‑digit CAGR, VOAs are transitioning from commodity peripherals toward higher‑margin, system‑integrated components. Product roadmaps and R&D budgets in 2026 should reallocate toward MEMS, PIC‑compatible VOAs, and embedded power‑metering capabilities to capture outsized returns.
- Supply‑chain and sourcing playbooks: MEMS chips and specialized fiber materials remain critical inputs with concentrated supply routes. Procurement teams must implement multi‑tier sourcing, buffer strategies, and supplier development programs in 2026 to hedge geopolitical and tariff risk.
- M&A and partnership timing: Given the market’s measured consolidation (moderate top‑tier share concentration), 2026 is an opportune window for strategic tuck‑ins and technology acquisitions that close gaps in electrostatic MEMS, LNOI/PIC integration, or multi‑channel attenuator capabilities.
- Regulatory and compliance readiness: New reliability testing standards and rising tariff noise necessitate compliance and scenario planning. Certification investments in 2026 can serve as points of differentiation.
What the full PW Consulting report delivers (practical, actionable content)
The full study is built for operators and investors who need executable intelligence, not just descriptive charts. Key deliverables include:
Variable Optic Attenuators Market
- Granular market model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario‑based sensitivity runs that isolate demand drivers and tariff/regulatory shocks.
- Demand drivers map and use‑case deep dives (telecom evolution, data centers, fiber sensing, test & measurement), aligned to procurement and product requirements by customer archetype.
- Supply‑chain heat maps and supplier dependency diagnostics highlighting critical inputs (MEMS chips, specialty fiber) and recommended dual‑sourcing architectures.
- Vendor benchmarking and scorecards combining technology, product breadth, manufacturing footprint, and commercialization strength — tailored for buy/sell/partner decisions.
- Go‑to‑market playbooks for suppliers in three tiers: incumbent OEMs, emerging MEMS/PIC startups, and precision test‑equipment providers — including channel strategies and value‑pricing tactics.
- Regulatory and standards matrix with action plans to align product validation to emerging test/qualification frameworks and to anticipate tariff scenarios.
- M&A screening framework with prioritized targets and valuation multipliers adjusted for integration risk and supply‑chain exposure.
Competitive landscape — strategic positions and implications
The VOA competitive set remains populated by specialized instrumentation firms, MEMS innovators, and optical components houses. Our analysis profiles a cross‑section of vendors to illustrate how capability sets map to end‑market demand:
- Santec Corporation (Japan): Known for high‑accuracy, repeatable modules optimized for transport networks and lab validation. Their recent wins in 400G/800G network supply chains underscore strength in carrier engagements and large‑volume qualification processes.
- VIAVI Solutions (United States): Broad portfolio across field, lab, and manufacturing applications. Their modular approaches and field‑ready devices make them a go‑to for operators requiring ruggedization and test‑automation integration.
- EXFO (Canada): Differentiates with precise multi‑channel attenuators and self‑adjusting mode features — attractive for manufacturing and automated test environments where channel count and repeatability matter.
- OZ Optics (Canada) and Thorlabs (United States): Serve the experimental, lab, and niche industrial segments with compact, rugged, and cost‑efficient offerings that prioritize flexibility and speed to deploy.
- Quantifi Photonics (MATRIQ) & Sercalo: MEMS‑centric players offering fast attenuation speeds, low insertion loss, and hermetic packaging — well positioned as MEMS becomes the dominant actuator technology for embedded VOAs.
- Lumentum Holdings (United States): With a recent introduction of an Electrostatic MEMS VOA (ESVOA), they signal a move toward high‑speed, integrable devices aligned to agile photonic components strategies.
- Optilab (United States): Focused on programmable, high‑resolution modules tailored for lab testing and DWDM/EDFA scenarios — important for customers seeking repeatable calibration and automation features.
Strategic implication: buyers should map vendor strengths to their critical use cases (speed, insertion loss, channel count, environmental ruggedness, and integration with PICs or automated testbeds). Suppliers should prioritize clear value props (e.g., integrated power metering, hermetic MEMS packaging, multi‑channel scalability) to move beyond price competition.
Recent industry developments and their strategic import
- New product introductions: The ESVOA announcement from a major component house signals commercial momentum for electrostatic MEMS that balance speed and integrability — a capability that will be table stakes for high‑speed network and PIC applications.
- Academic breakthroughs: Demonstrations of VOAs on thin‑film lithium niobate (LNOI) platforms point to medium‑term disruption: compact, low‑loss PIC‑compatible attenuators could rework product architectures and drive consolidation between photonic foundries and attenuator vendors.
- Large contracts: Carrier procurement of wide‑range VOA modules for next‑generation 400G/800G deployments validates the demand pull for high‑dynamic‑range and carrier‑grade qualification.
- Standards and regulation: The publication of new reliability testing standards for VOAs and the reintroduction of tariff uncertainty are governance dynamics that will reshape qualification cycles and sourcing strategies.
Risk profile and scenario considerations
Key risks that should be embedded into 2026 planning:
- Geopolitical and tariff volatility: Heavy reliance on Asian‑sourced MEMS components creates susceptibility to trade policy shifts. Scenario planning in our full report quantifies revenue impacts under alternate tariff and localization assumptions.
- Technology substitution: PIC‑based attenuators and advances in LNOI threaten to displace discrete MEMS VOAs in some applications. Roadmaps should therefore balance product lifecycles and optionality toward photonic integration.
- Standards and qualification: New IEC testing standards increase time‑to‑market for suppliers without structured testing and certification pipelines, advantaging incumbents with robust validation infrastructures.
- Supply‑chain concentration: Single‑source dependencies for MEMS chips or specialized fibers create downstream production and margin risk unless addressed proactively.
Recommended 2026 playbook (prioritized actions)
- Immediate (0–12 months): Freeze dual‑sourcing strategies for MEMS inputs, establish tariffs contingency pricing, and fast‑track compliance to the latest reliability standards.
- Near term (12–24 months): Invest or partner in MEMS and PIC integration capabilities, add embedded telemetry (e.g., in‑built power metering) to differentiate, and pilot multi‑channel product variants for manufacturing partners.
- Medium term (24–36 months): Execute targeted M&A for niche MEMS or LNOI competencies, consolidate vendor relationships where scale advantage exists, and deploy field trials with anchor customers to validate integrated solutions.
Closing: how PW Consulting helps
Our full Variable Optic Attenuators Market report provides the quantitative backbone and executable frameworks to convert the strategic takeaways above into board‑level decisions. It contains the complete market model (2020–2025 historic, 2026–2032 forecasts), segment and regional breakdowns, vendor scorecards, acquisition target lists, and scenario simulations that translate market growth and shocks into P&L and balance‑sheet impacts. If you are positioning for product launches, negotiations with carriers, or evaluating strategic M&A in 2026, the detailed intelligence in the complete study will supply the data‑driven confidence and operational playbooks you need.
To access the full set of segment‑level forecasts, regional splits, and the vendor due‑diligence matrices that we intentionally withhold here, please visit our report page or contact PW Consulting’s advisory desk for a tailored briefing and model access.
For detailed analysis of this topic, please visit the official page: Variable Optic Attenuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


