



PW Consulting: Diffraction Gratings Market to Hit USD 367.1 Million by 2032

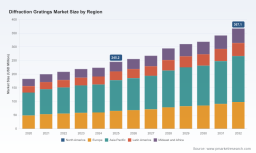
Diffraction Gratings Market 2026: Strategic Imperatives for Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused primer on the Diffraction Gratings market to inform executive strategies during 2026. This note synthesizes our latest market modeling (base year 2025), competitive landscaping, technological inflection points, and regulatory constraints—framing clear actions for procurement, R&D investment, and M&A prioritization. The analysis that follows signals the strategic value of our full report: deep, executable intelligence designed to reduce risk and accelerate time-to-value. Sensitive segment-level tables and granular regional breakdowns are intentionally withheld in this preview to preserve the actionable premium of the full study.
Diffraction Gratings Market
Macro trajectory and what it means for 2026 decisions
From a macro perspective, the market has expanded steadily from the early 2020s into 2025, and our base-year modeling quantifies that upward trajectory. Between 2020 and 2025 the sector demonstrated resilient growth, and our forecast through 2032 projects continued expansion—underpinned by a compound annual growth rate of 5.98% for the 2026–2032 horizon. By design, our projections integrate supply-side constraints, adoption lags in high-spec space/defense programs, and accelerating demand from quantum sensing, advanced spectroscopy, and high-energy laser systems.
Diffraction Gratings Market
For 2026 planning cycles, the implications are straightforward: demand is growing, but opportunity is concentrated in technically demanding subsegments and mission-critical programs that value performance, qualification pedigree, and supply security over commoditized cost competition. Procurement teams should therefore prioritize supplier qualification and long-lead strategic contracts; R&D and product teams should orient roadmaps to tolerance-driven performance (efficiency, polarization ratio, wavefront error); and business development should align GTM resources to a smaller set of high-value end-markets.
Diffraction Gratings Market
Where the growth is driven (high-level)
- Advanced sensing and instrumentation: continued upgrades of laboratory, aerospace, and defense spectroscopy platforms demand gratings with tighter efficiency and stray-light control.
- Quantum and photonics subsystems: transmission and holographic solutions tailored to wavelength stability and low scatter are emerging as a high-value vertical.
- Space and astronomy programs: mission timelines and payload qualification cycles create premium, low-volume opportunities that reward suppliers with heritage and process documentation.
- Laser and high-energy applications: robustness against high fluence, polarization insensitivity, and thermal stability are differentiators.
Note: detailed application- and region-level forecasts are part of the full report. This preview intentionally omits those granular splits to preserve commercial exclusivity.
Market structure and concentration
The market demonstrates moderate concentration: our concentration metrics indicate that leading suppliers collectively control a meaningful share of revenue and technical supply capacity. This dynamic creates both opportunity and risk. For established vendors, concentration supports pricing discipline and margin stability in specialized segments. For new entrants, barriers include capital-intensive tooling, certified cleanroom capacity, and the ability to demonstrate parentage on high-stakes programs.
In 2026, procurement managers and corporate development teams must read concentration as a lever: strategic partnerships or minority stakes can secure capacity without the multi-year CAPEX cycle required to build world-class facilities in-house.
Competitive landscape: capabilities that matter
Our company-level review in the full study profiles suppliers across manufacturing method (ruled, holographic, ion-etched, replicated), substrate materials (silica, Zerodur, SiC, ULE), and certification posture. Highlights from public and proprietary sources:
- OPCO Laboratory (United States): recognized for precision ruled gratings produced with ruling engines and diamond tooling, serving spectroscopy, defense, aerospace, and semiconductor inspection markets. Their ITAR registration and heritage in reflective-coated substrates make them a common partner on defense contracts.
- Ibsen Photonics (Denmark): a leader in transmission gratings for quantum sensors and pulse compression; ISO 9001/13485 certification supports high-volume, high-qualification medical and quantum sensing programs.
- Thorlabs and Edmund Optics (United States): broad product portfolios covering ruled and holographic gratings across UV–IR bands, with solutions geared to instrumentation and applied research markets where catalog availability and lead time are decisive.
- HORIBA (Japan / France): deep expertise in custom holographic and ion-etched gratings for space and astronomy, with demonstrated production for mission hardware and large-format replicas on ULE/Zerodur substrates.
- RP Photonics (Switzerland): an authoritative resource on grating physics and efficiency optimization—valuable as a technical reference and collaborator on performance modeling.
- Omega Optical, Holographix, LightSmyth Technologies: niche specialists in replication, UV deep-transmission variants, and polarization-insensitive designs respectively—each representing potential partners for scaling production or solving high-energy laser challenges.
Our vendor scorecards evaluate capability along five decision-critical axes: optical performance (efficiency, scatter, polarization), manufacturing scale (substrate sizes, groove density range), program qualification (cleanroom class, documentation, heritage), export/compliance posture (ITAR/Export Control), and commercial flexibility (lead times, MOQ, replication options). These scorecards are included in the full report and are constructed to support RFP and supplier selection workflows.
Technology and production dynamics
Technological progress is not uniform across the market. Key trends we monitor include:
- Manufacturing hybridization: combination of ruling-engine capability and ion-etch or holographic replication to deliver both high performance and scalable volumes.
- Large-format competence: suppliers are expanding capability for gratings approaching meter-scale with ISO 6-class process controls to maintain wavefront error targets—critical for astronomy and Earth-observation instruments.
- Materials engineering: increased use of ULE, Zerodur, and SiC for thermal stability in space optics, and polymer replication for cost-effective VUV–LWIR coverage.
- Specialty coatings and blazed geometries: necessary to meet efficiency and polarization specifications for laser vs. spectroscopy applications.
These capabilities translate directly into procurement and product design decisions. For systems integrators pursuing space or high-energy laser contracts, supplier proof of process control (including cleanroom class, polarization tolerance records, and test data) is as important as quoted price.
Regulatory and compliance guardrails
Regulatory constraints materially affect market access and program execution. Relevant dynamics include:
- Export controls: ITAR and national export screening apply to suppliers and transactions involving defense- or high-energy-laser-related gratings; non-compliance risks program disruptions.
- Quality standards: ISO 9001 and, where medical or quantum sensor production is involved, ISO 13485 certification are often contractual prerequisites.
- Tolerance-driven requirements: space missions and specialized UV devices demand tight polarization and efficiency tolerances; suppliers must demonstrate measurement traceability and process capability.
Companies entering or scaling in this market must build compliant supply chains and documentation processes early to avoid costly rework and procurement disqualifications.
Strategic recommendations for 2026
Based on our modeling and supplier assessments, we advise executives to prioritize the following actions in 2026 planning cycles:
- Secure qualified capacity: enter multi-year purchase agreements with suppliers who demonstrate both technical pedigree and export-compliant processes. For mission-critical programs, prioritize dual-sourcing strategies that combine heritage suppliers and niche specialists.
- Invest selectively in upstream capability: firms with recurring demand profiles should evaluate targeted vertical integration—either through replication capability or strategic minority investments in suppliers—to shorten lead time and protect margins.
- Align product roadmaps to high-value specifications: reprioritize R&D toward polarization-insensitive designs, deep-UV transmission, and large-format grating performance that command premium pricing.
- Operationalize certification early: accelerate ISO/quality and export-control readiness as part of bid qualification, not as a post-award activity.
- Use M&A as a capability accelerator: given moderate market concentration, acquisitions of niche engineering houses or replication capacity can yield rapid capability and customer access—our full study includes an M&A playbook with valuation heuristics and integration risks.
What the full PW Consulting report delivers
The full Diffraction Gratings Market study is structured for practical execution. It contains:
- Demand-side TAM and bottom-up forecasts by type, application and region (historical 2020–2025, forecast 2026–2032), with sensitivity scenarios tied to aerospace mission timelines and quantum adoption curves.
- Supplier scorecards and comparative capability matrices, including lead-time benchmarking and manufacturing footprints.
- Pricing and margin analysis across production methods (ruled, holographic, ion-etched, replicated) and substrate categories.
- Regulatory checklist and compliance playbook for ITAR, ISO pathways, and export controls.
- Go-to-market and procurement playbooks: RFP templates, qualification gates, and contract structures aligned to long-lead, high-spec procurements.
- Case studies: mission support engagements, replication scale-up, and failure-mode remediation examples.
Because segment-level splits and client-ready spreadsheets are material to tactical decision-making, those detailed tables are reserved for the full report and accompanying client deliverables.
Final short-term actions for leadership
- Procurement: begin supplier pre-qualification against the five-axis scorecard and commence export-control diligence on shortlist candidates.
- R&D/Product: prioritize one development sprint to prototype polarization-insensitive or deep-UV grating variants aligned to a prioritized customer use case.
- Corporate Development: identify 2–3 buy/build targets—specialists with either replication scale or unique substrate expertise—to evaluate against the M&A playbook in our report.
- Risk & Compliance: perform an export-control exposure map tied to targeted programs and suppliers to quantify mitigation costs and lead-time impacts.
In an expanding but technically demanding market, competitive advantage accrues to organizations that combine technical rigor, certified manufacturing, and disciplined supply-chain strategy. PW Consulting’s full Diffraction Gratings Market study provides the applied intelligence to convert market growth into defensible, profitable initiatives in 2026 and beyond. For the complete dataset, supplier scorecards, and the full set of tactical playbooks referenced above, access the full report and client portal.
For detailed analysis of this topic, please visit the official page: Diffraction Gratings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


