



PW Consulting: In-pipe Inspection Robot Market Eyes 8.45% CAGR to 2032

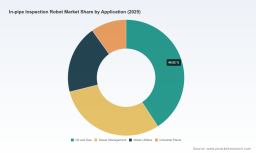
In-Pipe Inspection Robot Market: Strategic Outlook for 2026 — A PW Consulting Preview
Executive summary
The in-pipe inspection robot market is entering a phase of sustained, technology-driven expansion. Our proprietary topline analysis shows the global market expanding from USD 1,020 Million in 2020 to USD 1,330 Million in the 2025 base year, and we forecast growth to USD 2,185 Million by 2032 — an implied compound annual growth rate (CAGR) of 8.45% across the 2026–2032 forecast window. For companies making 2026 strategic choices — from product roadmaps and channel investments to M&A and procurement strategy — the question is no longer whether to engage with in-pipe robotics, but how to position for differentiated value capture as the market professionalizes.
In-pipe Inspection Robot Market
Why this research matters for 2026 decision-makers
-
Capital allocation with conviction. With mid-single-digit to high-single-digit CAGR dynamics and a market that more than doubles over the coming decade, 2026 is a pivot year for allocating R&D and deployment capital. Buyers must balance the economics of longer-range, higher-cost multi-sensor platforms against the operational benefits of lower-cost, task-specific crawlers. Our analysis frames that trade-off in ROI terms so CFOs can prioritize investments across portfolio cohorts.
In-pipe Inspection Robot Market -
Regulatory-driven demand windows. New and evolving regulations (e.g., ATEX Zone 1 requirements for explosion-proof devices in hazardous sectors and U.S. PHMSA mandates for internal inspections of unpiggable gas mains) are creating defined procurement cycles and accelerated replacement needs in regulated end markets. Companies that align product certification timelines and approval strategies with these regulatory windows will secure advantaged procurement pipelines in 2026–2027.
In-pipe Inspection Robot Market -
Supply chain and unit-economics sensitivity. Advanced in-pipe robots increasingly depend on specialized components — high-performance Li-ion cells, ruggedized imaging arrays, and ATEX/IECEx-rated enclosures. Our field interviews and supplier mapping highlight that lithium-ion component disruptions and battery supply constraints are material near-term risks that inflate per-unit costs and delay deployments; many advanced platforms carry substantial upfront costs, which in turn shapes buyer selection and financing models.
-
Competitive positioning in a consolidating but not concentrated market. The landscape is characterized by a handful of established platform providers and a growing set of specialized entrants. The top three suppliers collectively command a meaningful share of commercial deployments, while the top five approach a near-majority presence — a dynamic that rewards differentiated technology, reseller networks, and strong after-sales service ecosystems.
Report contents — what you will get (practical, decision-ready deliverables)
-
Executive decision framework — a one-page playbook for 2026 capital and procurement choices, mapping use-case severity to platform class and payback windows.
-
Market model and topline forecasts — end-to-end revenue curves and sensitivity scenarios across our 2026–2032 forecast horizon, plus upside/downside stress tests driven by regulatory adoption and component scarcity.
-
Vendor scorecards — standardized evaluation matrices covering technology maturity, certification readiness (ATEX/IECEx/PHSMA alignment), service footprint, and GTM strength for the leading vendors.
-
Go-to-market playbooks — channel strategies (direct, distributor, OEM embed), pricing archetypes (capex sale vs. as-a-service), and recommended field-support models to maximize installed-base lifetime value.
-
Procurement and piloting templates — RFP language, test acceptance criteria, benchmark inspection runs, and KPIs to validate performance claims during vendor pilots.
-
Supply-chain risk matrix and mitigation options — alternative sourcing paths, strategic component bundling, and inventory strategies to reconcile Li-ion shortages and certification lead times.
-
Deployment case studies and ROI calculators — anonymized, real-world deployment economics across municipal, industrial, and hazardous-sector scenarios to support business case sign-off.
-
Regulatory and standards annex — a concise mapping of regional certification regimes, critical compliance milestones, and recommended product-certification roadmaps.
Competitive landscape — who to watch and how they differ
The vendor ecosystem combines established platform vendors, specialty manufacturers, and integrators. Below is a strategic snapshot of the primary companies covered in our study (selected profiles are illustrative of the full vendor analysis contained in the report):
-
Envirosight LLC (United States) — Known for robust wheeled and tracked inspection platforms optimized for municipal sewer and industrial pipeline maintenance; strong emphasis on rugged CCTV and multi-sensor modularity. URL: https://envirosight.com
-
CUES Inc. (United States) — Provider of in-pipe crawlers and rehabilitation equipment with deep relationships in water and sewer utilities; strong aftermarket and operator training capabilities. URL: https://cuesinc.com
-
RedZone Robotics (United States) — Focused on tracked platforms with integrated sensing suites for condition assessment; notable for utility-focused analytics and deployment services. URL: https://redzonerobotics.com
-
Fiberscope (United States) — Brings ATEX-certified, explosion-proof inspection robots to hazardous industries; recent product introductions expand viability in oil, gas, chemical and pharmaceutical pipelines. URL: https://fiberscope.net
-
Nexxis (United States) — Modular crawlers and tractors built for long-range industrial inspection; emphasis on customization and integration with NDT sensors. URL: https://nexxis.com
-
ULC Technologies (Canada) — Specialist in live-gas deployment systems and structural integrity platforms; known for solutions that reduce disruption during gas-main inspection activities. URL: https://ulctechnologies.com
-
Pipe Trekker (United States) — Portable, battery-operated crawlers targeting smaller-diameter municipal and stormwater systems with an emphasis on ease-of-use and low mobilization cost. URL: https://www.pipetrekker.com
-
Deep Trekker (Canada) — Battery-powered crawlers and underwater-capable platforms for small-diameter and partially submerged environments; strong sell-through in inspection-for-hire operators. URL: https://deeptrekker.com
-
Eddyfi Technologies / Inuktun brand (Canada) — Integrates advanced nondestructive testing (NDT) capabilities into in-pipe robotics, enabling higher-fidelity condition assessments for critical infrastructure. URL: https://www.eddyfi.com
Recent industry developments and regulatory dynamics
Key events that are reshaping the competitive and operational environment include:
-
Product certification and launches: The market is seeing focused product introductions for hazardous environments; for example, an ATEX Zone 1 certified inspection robot was announced that materially expands opportunities in oil, gas, and chemical sectors.
-
Public-sector deployments: Multiple municipal and regional authorities have recently piloted or deployed advanced inspection robots — including long-range, high-resolution video inspection projects — which are pushing performance expectations for commercial providers.
-
Regulatory tailwinds: PHMSA and similar regulators globally are formalizing inspection expectations for unpiggable pipelines, creating sustained procurement schedules and certification prerequisites that favor vendors with demonstrated compliance pathways.
-
Supply and cost pressures: Persistent lithium-ion supply-chain disruptions and the higher upfront price points of multi-sensor robots are constraining smaller utilities and accelerating interest in as-a-service and leasing offerings.
-
Standards fragmentation: Divergent regional certification frameworks (e.g., ATEX in Europe vs. North American equivalents) extend approval timelines and introduce interoperability challenges for global suppliers.
High-level strategic actions for 2026
-
Hedge supply chain risk now. Secure key components through multi-sourcing agreements, strategic inventory positions, or contract manufacturing alliances to mitigate Li-ion and imaging supply volatility.
-
Pursue targeted certification investments. For vendors, prioritizing ATEX/IECEx and regionally equivalent certifications will unlock hazardous-sector revenues; for buyers, require vendor roadmaps that include certification milestones in procurement contracts.
-
Deploy pilot-to-scale pathways. Structure tiered pilots with explicit acceptance criteria (imaging quality, autonomy, mean time to repair, data integration) and pre-negotiated purchase or leasing terms to reduce procurement friction.
-
Bundle software and services. Differentiate via analytics, predictive maintenance modules, and field-service SLAs; subscription and managed-service models can lower adoption barriers for smaller utilities.
-
Evaluate M&A selectively. Buyers and platform vendors should consider acquisitions that fill gaps in certification, NDT integration, or service coverage to accelerate market access without diluting core R&D.
What we intentionally withhold in this preview
In keeping with our “trailer” approach, this introduction conveys the market scale, growth trajectory, regulatory vectors, and practical implications for 2026. Detailed segment-level tables, regional and application-specific revenue breakdowns, granular vendor market shares, and underlying primary-research appendices are reserved for the full PW Consulting in-pipe inspection robot market report. Those granular datasets and procurement-ready artifacts are where the real execution value resides.
Next steps — how to use this insight
For executives and procurement leads preparing 2026 budgets: treat this analysis as the strategic framing to inform scenario planning. For product and commercial leaders: use the vendor and certification insights to accelerate product-certification roadmaps and channel alignment. And for investors and M&A teams: the market’s medium-term growth and measured consolidation dynamics indicate windows for targeted acquisitions, particularly where certification or service footprint can be acquired to shorten time-to-revenue.
PW Consulting’s full report contains the actionable models, vendor scorecards, pilot templates, and scenario-sensitive market tables you need to convert strategic intent into executable programs. Contact our research team or visit the full study to access the complete dataset and practitioner toolkits.
For detailed analysis of this topic, please visit the official page: In-pipe Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


