



PW Consulting: Active Vibration Isolation Market to Hit USD 447.0 Million by 2032 at 6.9% CAGR

Active Vibration Isolation Market: Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, this briefing synthesizes the most consequential, decision‑grade takeaways from our full Active Vibration Isolation Market study — designed to inform capital allocation, product road‑mapping, sourcing, and M&A choices through 2026 and beyond. Treat this piece as a high‑calibre trailer: it surfaces the analytical spine, commercial implications, and competitive dynamics you need to frame strategy — while reserved, granular tables and segment‑level revenue detail are available in the full report.
Active Vibration Isolation Market
Why this market matters in 2026
Active vibration isolation (AVI) is increasingly mission‑critical across advanced manufacturing, metrology, and research instrumentation. From sub‑nanometer lithography stability to microscopy and photonics testbeds, precision end users view vibration control not as a peripheral purchase but as a capital enabler. That shift is visible in the market’s trajectory: the sector expanded from roughly USD 200 million in 2020 to about USD 280 million in our 2025 base year, and is projected to continue advancing through the 2026–2032 forecast window at a compound annual growth rate of approximately 6.9%, reaching a materially larger market size by 2032.
Active Vibration Isolation Market
For corporate strategists, that combination of steady volume growth and rising product sophistication creates three immediate opportunities in 2026: (1) differentiate through integrated systems and services rather than hardware alone; (2) secure resilient supply chains for specialized polymers and steels; and (3) align product roadmaps with tightening industry vibration standards and the accelerating cadence of high‑precision applications.
Active Vibration Isolation Market
Market dynamics you must internalize
-
Demand quality is shifting. Buyers are moving up the value chain — from isolated component purchases to platform‑level solutions (hardware + control software + integration services). This increases average deal size for vendors that can deliver predictable system performance, validated by settling time, controllability and service guarantees.
-
Technology bifurcation is normalizing. Piezoelectric, pneumatic, electromagnetic and hybrid approaches coexist, each with trade‑offs across frequency bands, footprint, power consumption and integration complexity. Innovation is focused on faster settling times, broader 6‑DoF control and reduced lifecycle power needs.
-
Standards and compliance matter operationally. Manufacturers and end‑users must design and validate systems against ISO 14839 and VDI 2038 vibration criteria. Compliance is increasingly a procurement prerequisite in semiconductor and high‑precision OEM supply chains.
-
Supply risk is concentrated in specialty materials. Pneumatic mounts and housings use specialized polymers and engineered steels; lead times and cost volatility for those inputs materially affect margins and delivery schedules for mid‑sized suppliers.
Competitive landscape — what the leader set tells us
The competitive field is characterized by a mix of specialized manufacturers, precision optics and metrology incumbents, and engineering‑focused SMEs. Market concentration is meaningful but not prohibitive — our assessment places the combined revenue share of the top three to five players at just over half of the market. That profile produces a competitive logic where scale and domain depth both confer advantages, yet pockets remain for focused competitors with differentiated technical capability or strong OEM relationships.
-
Technical Manufacturing Corporation (TMC) — notable for the STACIS family of piezoelectric isolation systems tailored to floor platforms, SEMs and OEM integration. They exemplify a high‑engineering, productized approach for semiconductor and metrology applications.
-
MKS Instruments / Newport — combines pneumatic stabilizers and S‑2000 series systems with optical tables and workstation integration. Their strength is in tightly coupling isolation hardware with established photonics and research workflows.
-
Herzan LLC — focuses on piezoelectric platforms delivering 6‑DoF sub‑1 Hz isolation for imaging and microscopy, emphasizing lab‑grade performance and instrument pairing.
-
Integrated Dynamics Engineering (IDE) — provides active pneumatic systems for semiconductor metrology and lithography; their portfolio underscores the importance of vacuum‑compatible and high‑stability solutions for fabs and research centers.
-
Other noteworthy specialists include Kinetic Systems Inc., Accurion (Halcyonics), Minus K Technology, Bilz, Table Stable and Daeil Systems. Collectively these firms demonstrate varied strategic postures: some compete on ultra‑low frequency performance and compact form factor; others on integration, service, or OEM partnerships.
Recent product activity underscores where R&D is converging. For example, Halcyonics’ i4 series introduced enhanced 6‑DoF control with settling times below 0.3 seconds — an incremental step that signals industry emphasis on rapid stabilization for high‑throughput measurement. Similar releases and iterative product improvements are recurring themes across incumbent portfolios.
Strategic implications for product, commercial and M&A leaders
-
Product strategy — system mindset. Vendors that bundle isolators with control software, analytics (for predictive maintenance) and installation/validation services win larger, recurring contracts. Roadmaps should prioritize faster settling, simplified integration APIs, and footprint reductions compatible with OEM assembly lines.
-
Go‑to‑market — align with end‑user procurement cycles. Semiconductor and life‑science customers buy to a high bar of compliance and long validation cycles. Sales strategies that invest in application labs, onsite validation, and shared risk pilots shorten procurement timelines.
-
Supply chain — secure critical specialties. Locking multi‑year agreements for specialized polymers and treated steels — and qualifying second‑tier suppliers — will be decisive for vendors aiming to scale without margin erosion as demand grows.
-
M&A and partnership playbook. Given the market’s moderate concentration and technical fragmentation, bolt‑on acquisitions that add complementary control software, vacuum‑compatible platforms, or regional service networks can rapidly expand addressable capability and improve win rates in large OEM bids.
-
Risk management. Regulatory alignment (ISO/VDI), supplier diversification, and post‑sales service guarantees (including defined performance SLAs) reduce commercial friction and protect reputation in precision customer segments.
What our full report delivers — practical contents
The full PW Consulting study is engineered for operational decision‑making. Highlights include:
- Market sizing and forecast for 2020–2032 with scenario analysis calibrated to adoption rates across major end‑use clusters and technology pathways.
- Competitive profiles and capability maps for leading vendors, including product roadmaps, patent trends, and channel strategies.
- Technology deep dives comparing piezoelectric, pneumatic, electromagnetic and hybrid solutions on performance, lifecycle costs and integration complexity.
- Supply‑chain diagnostics emphasizing critical raw materials, single‑source risks, and mitigation levers.
- Regulatory and standards compendium focusing on ISO 14839 and VDI 2038 implications for product claims and procurement acceptance criteria.
- Commercial playbooks: pricing benchmarks, contract structures, and pilot‑to‑scale deployment templates tailored for semiconductor fabs, photonics OEMs, and research institutions.
- Investment and M&A scoring model to evaluate targets on technology fit, service footprint and customer overlap.
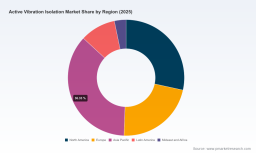
Note: This preview intentionally omits full regional, type and application split tables and underlying transactional data — those granular layers (region/application/type revenue breakdowns, vendor revenue by product line, and segmented CAGR sensitivities) are available in the full report and database package.
Action checklist for 2026
-
For product leaders: accelerate integration of control software and user diagnostics into next generation platforms — differentiate on measurable settling time and validated 6‑DoF performance.
-
For procurement and operations: initiate multi‑year sourcing conversations for specialty polymers and treated steels; qualify redundancy in pneumatic component suppliers.
-
For corporate development: prioritize targets that add vacuum‑capable platforms, OEM interfaces, or regional service networks to improve total addressable market and defensibility.
-
For sales and partnerships: invest in application labs and co‑validation programs aligned with ISO/VDI standards to compress customer validation timelines.
Conclusion
The Active Vibration Isolation market in 2026 is a growth market with clear technical differentiation points and procurement disciplines that favor integrated, verifiable solutions. Strategic players will be those that combine product innovation (settling time, 6‑DoF control), robust supply‑chain management for specialty materials, and commercial models that reduce customer validation friction. PW Consulting’s full study delivers the datasets, vendor matrices and executable playbooks necessary to convert this structural opportunity into measurable revenue and market share gains. For the complete segmented intelligence, vendor scorecards, and downloadable databases referenced above, please consult the full report.
For detailed analysis of this topic, please visit the official page: Active Vibration Isolation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


