



PW Consulting: Medical Thermometers Market to reach USD 370.18 Million by 2032 (8% CAGR)

Medical Thermometers Market 2026: Strategic Imperatives from PW Consulting
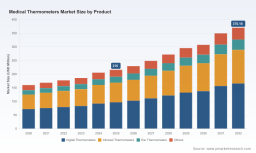
As healthcare delivery models and technology vectors converge in 2026, the medical thermometers market is shifting from commodity hardware toward integrated clinical workflows and value-based monitoring. Our latest market study—anchored on a 2025 base year and a detailed historical view from 2020–2025, with forward-looking forecasts to 2032—identifies the macro forces that will determine winners and losers over the next planning cycle. The global market is set to expand at an 8.0% compound annual growth rate (CAGR) over the forecast window, moving from an estimated USD 216.0 Million in 2025 to a materially larger market by 2032 under the scenarios we tested. These top-line dynamics create discrete strategic opportunities for device OEMs, healthcare systems, distributors, and new entrants pursuing both clinical and consumer channels.
Medical Thermometers Market
Why this study matters for 2026 decisions
-
Regulatory regime changes are immediately actionable. The FDA’s June 2025 final order exempting certain class II clinical electronic thermometers (without telethermographic or continuous measurement functions) from 510(k) premarket notification lowers time-to-market and cost for incremental product updates and private-label introductions. Organizations that re-prioritize their product roadmaps and submission pipelines in response can capture faster commercial windows in clinical procurement cycles.
Medical Thermometers Market -
Reimbursement shifts create new service revenue vectors. Effective January 1, 2026, Medicare’s updated Physician Fee Schedule introduced new remote physiologic monitoring (RPM) codes applicable to short-duration monitoring (examples include codes with monthly rates in the roughly $26–$52 range). Thermometer manufacturers and digital health integrators that design RPM-enabled devices and evidence packages can monetize temperature monitoring as a billable service in post-acute care, chronic disease management, and infection surveillance programs.
Medical Thermometers Market -
Market concentration and competitive posture matter. The market shows mid-level concentration among incumbent medtech suppliers; the three- and five-firm concentration metrics indicate leading players retain substantial share while leaving room for focused challengers that combine differentiated tech, channel strategy, or cost-advantaged disposable models.
Macro trends we analyze (and why they change strategy)
-
From device to data: Thermometers are no longer one-off point instruments. Buyers increasingly evaluate devices for interoperability, security of telemetry, and integration with RPM workflows and EMRs. Product roadmaps that pair accurate sensing with robust data pipelines unlock higher lifetime value via software subscriptions and analytics.
-
Single-use versus reusable economics: Single-use Phase Change Technology (PCT) disposables and hygienic designs address staffing, infection control, and throughput in high-volume settings. Our field work and supplier interviews indicate labor cost optimization and infection-prevention protocols are major drivers for procurement in hospitals, long-term care, and mobile clinics.
-
Non-contact adoption and clinical validation: Non-contact infrared devices remain attractive for screening and triage, but clinical acceptance depends on validated accuracy across use cases and protocols for cleaning and reprocessing. ISO 17664:2021 continues to inform hospital procurement criteria by clarifying low-risk reprocessing expectations for non-critical devices.
-
Supply chain and raw material resilience: Disposable thermometers leveraging proprietary, non-toxic PCT chemistries (explicitly free from natural rubber latex) mitigate allergy and sterilization constraints, but supply continuity for those chemistries and associated components is a supplier-risk vector we quantify in this report.
What the full report delivers (operational takeaways)
We designed this study as a strategic playbook for 2026 decision-makers. The deliverables are built to be operational rather than academic—organized to enable rapid execution across product development, commercial strategy, regulatory planning, and M&A diligence:
-
Market sizing and methodology: Transparent, reproducible topline market model calibrated to 2020–2025 historicals and scenario-driven forecasts to 2032. (Note: this executive preview omits detailed sub-segment tables; full breakouts are available in the subscription report.)
-
Demand drivers and elasticity analysis: Quantified sensitivity of device demand to hospital procurement cycles, consumer adoption curves, and RPM reimbursement penetration.
-
Regulatory & reimbursement playbooks: Step-by-step impact assessment of the FDA’s 2025 exemption and CMS RPM code adoption, including a decision matrix that maps product features to required evidence and expected time-to-revenue.
-
Competitive heatmap and capability audit: Profiling incumbent and challenger firms—product breadth, clinical validation depth, digital integration, and channel strength—with practical counters and partnership targets.
-
Supply chain & component risk dashboard: Supplier concentration indices, critical-component lead-time simulations, and contingency sourcing recommendations for both reusable and single-use chemistries.
-
Commercial playbooks: Tailored go-to-market templates for hospitals/clinics, home-care OEM partnerships, and pharmacy retail channels—each including pricing levers, bundling strategies, and sales-scripting for value-based conversations.
-
M&A and partnership screening tools: A scoring model for bolt-on acquisitions and joint ventures that accelerate access to RPM, disposables, or validation data required by key customers.
-
Operational toolkits: RFP response templates, clinical validation study protocols, and a buyer-ready checklist for procurement teams evaluating vendors against infection-control and reprocessing standards.
Competitive landscape — who to watch
The market features a mix of established medtech players and specialized innovators. Our strategic profiles focus on where each player is likely to compete and how partners or acquirers should position themselves.
-
Welch Allyn (Skaneateles Falls, NY — https://www.welchallyn.com/): Strong clinical footprint with the SureTemp series and non-contact infrared options; well-placed for hospital channel consolidation and clinical workflow integration.
-
Medical Indicators (Hamilton, NJ — https://www.medicalindicators.com/): Specialist in single-use Phase Change Technology disposables (e.g., Tempa-DOT, NexTemp). Recent product introductions emphasize fast, hygienic, transportable solutions tailored to high-volume clinical settings and mobile care.
-
Omron Corporation (Kyoto, Japan — https://www.omron.com/global/): Broad consumer and clinical portfolio with non-contact forehead thermometers; strengths lie in global retail reach and brand recognition in home monitoring.
-
Microlife Corporation (Widnau, Switzerland — https://www.microlife.com/): Offers a mix of clinical and non-contact devices with diagnostic monitoring integration—well-positioned where multi-parameter suites are requested.
-
3M Company (St. Paul, MN — https://www.3m.com/): Focused single-use Curos thermometers aimed at infection prevention in institutional settings; brings distribution scale and procurement relationships in acute care.
-
Beurer (Ulm, Germany — https://www.beurer.com/): Consumer and clinical-grade products with strong retail channels in Europe and a value-focused product set for home care and outpatient monitoring.
Recent developments that change the calculus
-
FDA Regulatory Clearance (June 2025): The agency exempted certain clinical electronic thermometers from 510(k) premarket notification when they lack telethermographic or continuous measurement functions. This materially reduces regulatory drag for incremental device revisions and private-label programs.
-
Medical Indicators Product Launch (Dec 2024): NexTemp Go, a transportable single-use thermometer optimized for hospitals, urgent care, mobile clinics, and elder care, highlights the move toward operational simplicity and infection control—factors that directly impact procurement selection criteria.
-
Reimbursement Update (Jan 1, 2026): New RPM codes introduced in Medicare’s Physician Fee Schedule open per-patient monthly revenue opportunities for short-duration physiologic monitoring including temperature. Early movers that align device telemetry and clinical workflows can capture incremental revenue and create stickier customer relationships.
-
Standards & Reprocessing: ISO 17664:2021 continues to codify low-risk reprocessing requirements for non-critical medical devices, shaping hospital purchasing decisions where reprocessing burden is a decisive factor.
Recommended actions for 2026 strategic plans
-
Short term (0–12 months): Re-score your product roadmap against the FDA exemption and CMS RPM codes. Prioritize low-complexity product updates that can be commercialized faster and pilots that validate billing workflows with early-adopter health systems.
-
Medium term (12–24 months): Invest in telemetry and interoperability. Partnerships with digital health integrators that can manage RPM billing and secure data flows will materially increase device value and differentiation.
-
Long term (24–36 months): Consider capability M&A or licensing deals to secure single-use chemistry supply, expand validated clinical endpoints, or scale an analytics offering that turns temperature data into actionable clinical signals.
How to use this preview
This executive brief is a strategic trailer: it outlines the market dynamics, competitive contours, and regulatory inflection points you need for 2026 planning. The complete PW Consulting report includes full sub-segment breakouts, regional and application-level demand models, supplier-level risk scores, and downloadable operational toolkits. If your team is preparing product roadmaps, negotiating distribution agreements, or building an RPM revenue thesis for 2026, the full dataset and playbooks will accelerate your path from strategy to execution.
Contact PW Consulting or visit our report page to access the full Medical Thermometers Market study and the proprietary models that underlie these recommendations.
For detailed analysis of this topic, please visit the official page: Medical Thermometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


