



PW Consulting: Electric Power System Analysis Software to Hit USD 5,731.3M by 2032 (8.5% CAGR)

Electric Power System Analysis Software Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior strategy advisor and head industry analyst, I prepared this executive preview to orient utility executives, investor teams, technology buyers, and M&A sponsors on the strategic stakes of the Electric Power System Analysis Software market as they make resource-allocation decisions in 2026. The full market research package contains granular segment, regional, vendor and scenario detail; this preview surfaces the analytic framework, key structural signals, and practical imperatives — while intentionally withholding the granular splits and proprietary scorecards that you will find in the full study.
Electric Power System Analysis Software Market
Market framing: pace, scale and the shape of growth
The market for electric power system analysis software has entered a sustained growth phase. Using 2025 as the base year and a historical window from 2020–2025, our topline is straightforward: the market is expanding at an expected compound annual growth rate of 8.5% across our forecast horizon (2026–2032). After steady recovery and reinvestment during the early 2020s, the global market moves from a multi‑billion dollar base in 2025 to materially larger levels through the early 2030s, reflecting a shift from episodic tool purchases to continuous platform investments underpinning grid operations, planning and resilience.
Electric Power System Analysis Software Market
Three quantitative touchpoints anchor the trajectory we model: the 2025 base, the opening forecast year (2026) when many utility programs move from pilots to scale, and the 2032 horizon where the combined effects of electrification, DER integration and advanced analytics reshape fundamentals. These macro markers underscore the difference between tactical software refreshes and strategic digital transformation programs that now dominate vendor roadmaps and buyer considerations.
Electric Power System Analysis Software Market
Structural drivers and nonlinear demand vectors
- Decarbonization + electrification: Accelerating renewable penetration and electrification of transport and industry increase the complexity of steady‑state and transient studies. Planning models must now account for variability, storage and active power electronics at scale.
- DER aggregation and market reforms: Policy actions like DER aggregation mandates and updated reliability standards compel utilities and grid operators to adopt software capable of modeling heterogeneous, highly dynamic asset fleets.
- Large, concentrated loads and interconnection pressure: New scenarios (including updated EPRI projections) show rapid growth in high‑density, energy‑intensive consumers such as data centers, creating interconnection and stability challenges that require higher‑fidelity modeling.
- Operationalization of planning: Buyers increasingly require solutions that bridge planning, operations and market functions — digital twins, real‑time analytics and closed‑loop workflows are now procurement validators, not optional features.
- Cloud, AI and model interoperability: Migration to cloud architectures and the integration of machine learning for anomaly detection and scenario reduction are redefining vendor differentiation and the total cost of ownership calculus.
Market structure and competitive implications
The market exhibits moderate concentration. A handful of vendors hold meaningful scale, but a sizeable portion of value remains distributed among specialized suppliers, regional integrators, and independent research houses. That structure creates three predictable competitor behaviors: horizontal incumbent expansion (platforms bundling simulation with automation or asset management), focused specialist innovation (high‑fidelity solvers, visualization, and digital twins), and services‑led differentiation (integrators converting licenses into long‑term contracts).
For executives, this means supplier selection is as much about architectural fit and ecosystem compatibility as it is about immediate feature parity. Consolidation risk and opportunities for tuck‑ins are real: incumbents are buying capabilities to bridge cloud, analytics and DER orchestration, while specialized vendors remain acquisition targets for larger automation and software houses.
What the full report delivers — practical, transaction‑ready intelligence
PW Consulting’s full Electric Power System Analysis Software report is designed for decision cycles that span procurement, investment, product strategy and M&A. Highlights include:
- Transparent market sizing and scenario methodology: detailed assumptions, sensitivity runs and back‑tested historical fit for 2020–2025 with forecasts through 2032.
- Demand‑side mapping: buyer personas, procurement cadences for utilities, TSO/ISO, IPPs, industrials and large commercial loads, plus budget timing and TCO models.
- Vendor scorecards and capability matrices: feature, deployment model (cloud/SaaS vs on‑prem), integration readiness, support footprint and roadmap alignment (note: proprietary scorecards are not published in this preview).
- Use cases and implementation playbooks: templates for pilots, scale‑up, data ingestion, and organizational change management tested in multiple utility environments.
- Regulatory and standards impact assessment: mapping NERC, FERC and other policy levers to buying triggers and compliance timelines.
- M&A and partnership playbook: valuation multiples observed, consolidation scenarios, and diligence checklists specific to software + services combinations.
- Cyber and resilience lens: scenario planning for extreme weather, cascading failures and targeted cyber incidents, including recovery and verification procedures.
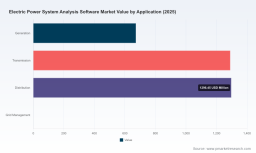
To preserve the teaser nature of this preview, the full regional, type and application split tables and the vendor scorecards are available only in the paid report. That detailed intelligence is the actionable content buyer teams use to prioritize pilots, budget requests, and RFP requirements.
Competitive landscape — how leading vendors position themselves
- PowerWorld Corporation (Champaign, Illinois) — Known for highly visual simulation capabilities and interactive platforms that scale to large transmission models. Their strength lies in operator‑facing visualization and scenario playback that accelerate stakeholder alignment in planning exercises.
- ETAP / Operation Technology Inc. (Irvine, California) — A leader in the digital twin narrative, ETAP emphasizes end-to-end modeling across design, operations and maintenance. Buyers value their integrated stacks for lifecycle management and dynamic/transient capabilities.
- PSI AG (NEPLAN) (Küsnacht, Switzerland) — NEPLAN’s modular architecture targets planners who need flexible, composable toolchains for transmission, distribution and industrial networks, making it attractive for complex, multi‑vector projects.
- OATI / Open Systems International (Bloomington, Minnesota) — Focused on grid modernization, OATI combines energy management with DERMS and market tools that are compelling for utilities seeking operational modernization rather than point‑tool replacement.
- ABB, Siemens, GE — Large automation and systems integrators that embed analysis tools into broader T&D solutions. Their advantage is portfolio breadth and procurement simplicity for large utilities that prefer one‑stop suppliers.
- Eaton, Schneider, DIgSILENT, Bentley — A mix of distribution‑focused modeling vendors and established simulation houses. These firms often win on depth of modeling, regional sales networks and domain‑specific integrations (e.g., distribution automation, industrial microgrids).
Five priority strategic actions for 2026
- Design modular roadmaps, not rip‑and‑replace projects: prioritize modular APIs, data standards and staged migrations from desktop to cloud‑enabled digital twins.
- Align procurement with regulatory timelines: incorporate compliance windows for DER aggregation and interconnection studies into procurement and pilot schedules to avoid implementation lags.
- Run outcome‑focused pilots: evaluate vendors under operational load — interconnection studies, contingency analysis and automated protection coordination workflows — to validate model fidelity, not just feature lists.
- Pursue hybrid vendor strategies: combine scale incumbents for core operational integration with specialist best‑of‑breed tools for advanced simulation and real‑time analytics where needed.
- Embed commercial and technical KPIs into contracts: TCO, model convergence rates, time‑to‑insight, and integration SLA clauses reduce vendor risk and improve delivery predictability.
Using this preview — next steps
This preview is intentionally diagnostic rather than prescriptive. It highlights market direction, vendor postures and the critical questions that procurement, engineering and corporate strategy teams must resolve in 2026. For teams preparing budget submissions, RFPs, or M&A diligence, the full report includes: complete regional/type/application splits, proprietary vendor scorecards, scenario‑weighted demand curves, and detailed case studies with implementation timelines and cost models.
Contact PW Consulting or visit our report page to access the complete dataset and tools that operationalize the analysis in this preview. The granular breakdowns and vendor matrices are the working products that convert this high‑level intelligence into awardable RFPs, board memoranda and investment memoranda.
Conclusion
In 2026 the Electric Power System Analysis Software market is no longer a niche corner of engineering departments: it is a strategic technology stack that underwrites system reliability, market participation, and the integration of renewable and distributed assets. Our research shows consistent growth supported by policy, asset mix change and new load patterns; the key decision for enterprises this year is how to convert market momentum into durable, interoperable capability without locking into brittle point solutions. Use the full PW Consulting study as the operational playbook for that conversion — the preview above provides the strategic orientation, the full report provides the execution map.
For detailed analysis of this topic, please visit the official page: Electric Power System Analysis Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


