



PW Consulting: Indoor DAS Market to Grow at 8.45% CAGR (2026–2032)

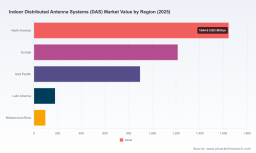
Indoor Distributed Antenna Systems (DAS) Market — Strategic Preview for 2026 Decision-Makers
Executive summary
As enterprises, venue operators, and neutral-host providers plan capital and operational investments for 2026, Indoor Distributed Antenna Systems (DAS) are transitioning from a connectivity commodity into a strategic platform. Our PW Consulting market study — base year 2025, forecast 2026–2032 — projects the global indoor DAS market to accelerate meaningfully over the coming investment cycle, driven by 5G in-building requirements, neutral-host deployments at high-density venues, and convergence with next‑generation Wi‑Fi. The market is forecast to grow at a compound annual growth rate (CAGR) of 8.45% through 2032, rising from a mid-single‑billion USD (Million) market in 2025 to a substantially larger market by the end of the forecast window. This briefing highlights the strategic value of the full report for executives making procurement, partnership, and capex allocation decisions in 2026 — deliberately omitting detailed segment-level figures to preserve proprietary insights available in the complete study.
Indoor Distributed Antenna Systems (DAS) Market
Why this matters for 2026 planning
-
Timing of network modernization: 2026 is a tipping point for organizations that deferred 5G-ready indoor upgrades during earlier economic cycles. Choosing the right architecture now (active, passive or hybrid DAS) will lock in performance and TCO outcomes for a multi-year horizon.
Indoor Distributed Antenna Systems (DAS) Market -
Neutral-host economics: Increasing preference for neutral-host models at airports, stadiums, and mixed-use developments fundamentally changes procurement criteria — landlord/owner economics, multi-operator agreements, and long-term service-level commitments become as important as upfront hardware costs.
Indoor Distributed Antenna Systems (DAS) Market -
Regulatory and compliance filtering: For government or regulated procurements, domestic manufacturing and specific compliance regimes (including public safety DAS standards and procurement rules) will eliminate many otherwise-competitive suppliers — creating scarcity in qualified vendor pools.
-
Technology convergence: DAS decisions are now inseparable from fiber backhaul design, small-cell strategies, and Wi‑Fi 7 integration. The right system choice reduces power, cooling, and space requirements across the property lifecycle.
Market trajectory — what the headline numbers tell us
Historic adoption shows steady recovery and expansion in in‑building wireless investment from 2020 through 2025 as mobile operators and enterprise owners resumed large-scale projects. Between 2026 and 2032 the market is projected to expand at an 8.45% CAGR, reflecting the combined impact of 5G densification, venue modernization (airports, stadiums, campuses), and the rise of neutral-host business models. For executives, this translates into growing supplier choices, increasing integration complexity, and the need to move from one-off projects to platform-based, lifecycle procurement strategies.
Key demand drivers and supply-side dynamics
-
5G readiness and multi-band support: Enterprise and venue owners are seeking solutions designed for evolving spectrum allocations and carrier coordination to avoid early obsolescence.
-
Energy and OPEX pressures: Integrating DAS with fiber and small-cell strategies systematically reduces site power and cooling, improving operational economics for large-scale deployments.
-
Compliance and public-safety requirements: Meeting NFPA/IFC public safety DAS mandates and related inspection protocols increases project complexity and vendor servicing requirements, extending delivery timelines and elevating installation costs.
-
Standardization for interoperability: Multi-operator coordination is increasingly governed by industry standards to ensure cross-carrier compatibility; adherence to the latest multi-carrier frameworks is now a procurement must-have.
Competitive landscape — who matters and why
The vendor field remains commercially diverse: established fiber and connectivity incumbents, specialized DAS hardware manufacturers, neutral‑host system integrators, and software-centric players each play distinct roles. The market’s competitive character is best described as fragmented with pockets of consolidation emerging around platforms that solve multi-operator, multi-technology use cases.
-
Amphenol — Following its strategic acquisition of a legacy fiber-based DAS business, Amphenol has consolidated its position in fiber-centric, in‑building platforms. Expect Amphenol to push integrated passive/active fiber solutions and to target large multi-site rollouts where supply-chain resiliency matters.
-
Corning — With an emphasis on fiber-first platforms engineered for 5G readiness, Corning is positioned for enterprise and carrier deployments that prioritize long-haul, low-loss backhaul and future-proof cabling architectures.
-
JMA Wireless — The company’s domestic manufacturing and active/hybrid platforms represent a compelling choice for procurements constrained by local sourcing rules and NDAA-like compliance. Their active DAS and xRAN solutions are attractive where integration with operator RAN functions is required.
-
SOLiD — A focused DAS specialist, SOLiD’s recent product introductions target the 5G era with software-enabled platforms that support digital signal processing and neutral-host models; this makes them a flexible bidder on venue and multi-operator contracts.
-
Comba Telecom — With an established footprint in neutral-host and indoor venue solutions, Comba competes strongly on turnkey deployments in dense commercial and public environments, emphasizing multi-carrier orchestration.
-
Boingo Wireless — Boingo’s convergence strategy — integrating DAS with advanced Wi‑Fi solutions — positions the company as a systems integrator for airports and high-traffic venues. Recent contract awards underscore demand for converged connectivity platforms.
-
Nextivity — Focusing on intelligent signal processing and in‑building optimization, Nextivity offers high-value functionality for environments that prioritize seamless cellular coverage with lower hardware footprints.
Recent strategic moves worth watching
-
Consolidation around fiber-based DAS platforms is intensifying, with incumbents acquiring specialized DAS divisions to offer end‑to‑end solutions and scale installation networks.
-
Product launches aimed specifically at 5G and beyond demonstrate a migration from analog/distributed architectures towards software-defined, centrally managed platforms that simplify multi-operator orchestration.
-
Neutral-host and convergence projects — converging DAS with Wi‑Fi 7 and other services — are being used as showcases for platform capabilities and as commercial proofs for broader deployment strategies.
What the full report delivers — practical, decision-oriented content
PW Consulting’s report goes beyond high-level forecasting. For procurement teams, network architects, real estate owners, and CIOs, it offers a suite of operational tools and models designed for immediate use in RFPs, capital planning, and vendor selection:
-
Validated market sizing and scenario forecasts by architecture and adoption pathway (presented in a way that supports sensitivity testing for your portfolio).
-
Vendor capability matrices and non‑financial bidder scorecards to streamline RFP shortlisting under common compliance and technical thresholds.
-
Total cost of ownership (TCO) and ROI templates calibrated to real deployment profiles (capex, installation, power, maintenance, and lifecycle replacement costs).
-
Deployment playbooks and milestone templates that incorporate regulatory checkpoints, public-safety testing requirements, and carrier coordination processes to reduce schedule risk.
-
Integration checklists for fiber backhaul, small-cell coexistence, and Wi‑Fi convergence — including recommended monitoring and fault‑management KPIs.
-
Negotiation playbooks for neutral-host commercial terms, SLAs, and multi-operator revenue-sharing models.
Implementation playbook & primary risks (summary)
-
Procurement sequencing: Prioritize compliance and interoperability pre-qualification during vendor shortlisting to avoid late-stage disqualifications.
-
Phased deployment: Adopt modular rollouts with centralized management to enable rapid scaling while controlling initial capital outlays.
-
Risk register highlights: Extended permitting and testing for public-safety systems, carrier integration delays, and supply-chain constraints for specialized optical components.
-
Mitigations: Use hybrid contracting (fixed-price + performance milestones), hold-back clauses tied to carrier acceptance, and staged acceptance gates aligned with tenant/operations cycles.
How PW Consulting’s report creates decision advantage
The complete study synthesizes macro forecasting with practical procurement artifacts to reduce time-to-decision and execution risk. It uniquely aligns vendor capability assessments with operational templates so leadership teams can move from strategy to contract negotiations in weeks rather than months. For 2026 capital planning, this translates into clearer budgeting, defensible vendor shortlists, and accelerated path-to-service with measurable KPIs for coverage, throughput, and availability.
Next steps for enterprise leaders
-
Use the report’s RFP templates to pre-qualify suppliers against compliance and interoperability standards before issuing tenders.
-
Run TCO sensitivity scenarios provided in the report to determine whether a CapEx‑heavy platform or an opex-first neutral-host partner fits your financial model.
-
Engage with vendors who demonstrate both platform roadmaps for 5G evolution and proof of neutral-host deployments to minimize both technical and commercial surprises.
Conclusion — a strategic inflection, not just incremental spend
Indoor DAS in 2026 represents a strategic inflection for connectivity-dependent organizations. Decisions taken this year will shape in‑building experience, operational costs, and vendor relationships across the next equipment lifecycle. PW Consulting’s full report provides the granular vendor comparisons, risk-adjusted financial models, and implementation artifacts necessary to convert market opportunity into repeatable deployment success. For the complete segment-level breakdowns, regional and application-level insights, and downloadable procurement templates, consult the full report on our site.
For detailed analysis of this topic, please visit the official page: Indoor Distributed Antenna Systems (DAS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


