



PW Consulting: Light Sheet Microscopy Market to Expand at 8.41% CAGR Through 2032

Light Sheet Microscopy Market: Strategic Intelligence Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a targeted briefing that frames our full Light Sheet Microscopy Market study for executives who must make decisive investments and go‑to‑market choices in 2026. This briefing highlights the market’s macro trajectory, competitive dynamics, and near‑term strategic imperatives — while preserving the granular segmentation and proprietary models reserved for subscribers. Use this as a high‑resolution preview to assess whether the full intelligence set should inform your 2026 CapEx, M&A, product, or partnership decisions.
Light Sheet Microscopy Market
Market trajectory at a glance (what the numbers mean)
Our base year is 2025. From 2020 through 2025 the light sheet microscopy market expanded consistently, reaching a 2025 market size of USD 119.75 Million (USD, revenue unit: Million). Under our central scenario, the market continues to scale at a compound annual growth rate (CAGR) of 8.41% across a 2026–2032 forecast window, producing a projected market approaching USD 209.32 Million by 2032. Market concentration is material but not monopolistic: the top three vendors account for roughly half of current industry revenue (CR3 ≈ 48.6%) and the top five approach two‑thirds (CR5 ≈ 65.0%).
Light Sheet Microscopy Market
What this implies for 2026 decisions:
Light Sheet Microscopy Market
- Growth is sustained and predictable enough to justify targeted CapEx for core academic imaging facilities, translational centers, and firms pursuing clinical pathology pilots.
- Concentration metrics indicate scale advantages for incumbents, but substantial share remains accessible to innovators and niche specialists — especially those that bundle hardware with software, AI, or specialized consumables.
- Investment timing matters: players that move in early 2026 to secure partnerships, validation sites, or pilot customers will capture disproportionate share as adoption accelerates.
Principal demand drivers and risk vectors
Demand is being driven by three converging forces: (1) methodological advantages for volumetric, live and cleared‑tissue imaging across developmental biology, neuroscience, immunology and clinical translation; (2) falling practical barriers to deployment — lower price entry tiers, modular platforms and shortened delivery lead times; and (3) rapid integration of analytics (AI/ML) that turns volumetric datasets into actionable biology and pathology insights.
Key risk vectors for 2026:
- Regulatory and reimbursement shifts as microscopy moves closer to clinical workflows — new CPT codes and evolving pathology reimbursement models can materially change ROI calculus for clinical deployments.
- CapEx sensitivity in smaller labs and emerging markets: although lower‑cost systems and attractive financing options are emerging, procurement cycles remain long and influenced by institutional budgets.
- Technology fragmentation: multiple architectural approaches (single‑objective, dual‑view, theta configurations, and lattice systems) create buyer confusion and slow enterprise standardization unless vendors offer clear migration pathways and software standardization.
Why this PW Consulting report matters to 2026 strategy
Executives tell us they want two things: confidence in the macro opportunity and playbooks that translate that opportunity into prioritized actions. Our full study supplies both. Highlights of the actionable content included:
- Robust market sizing and scenario models (base year 2025; historical series 2020–2025; forecast 2026–2032) with transparent assumptions and sensitivity analyses that quantify outcomes under alternate reimbursement, pricing, and adoption curves.
- TAM / SAM / SOM frameworks for product planners and commercial leaders, with customizable dashboards you can parameterize for target geographies, buyer types, and channel strategies.
- Competitor benchmarking that combines public product portfolios, patent activity, shipment estimates, and go‑to‑market positions to generate defensible share projections and identify whitespace for new entrants or extensions.
- Commercial playbooks — channel models, pricing reference architecture, and buyer persona maps — tailored for OEMs, imaging core facilities, CROs and clinical labs contemplating in‑house capability vs. service procurement.
- Investment and M&A screening tools: valuation proxies, three‑year integration roadmaps, and diligence checklists focused on software/IP, sample‑prep consumables, and service agreements that most influence post‑acquisition value capture.
- Regulatory & reimbursement impact matrix and an actionable checklist for clinical translation pilots that compresses time‑to‑value while managing payer and lab accreditation risk.
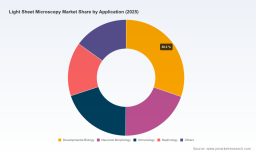
To honor the “trailer” principle: we intentionally do not disclose granular region, type, or application share tables here. The full report contains those splits, empirical data points and downloadable models for licensed users.
Competitive landscape — snapshot and strategic implications
-
ZEISS (Jena, Germany) — Offers lattice‑style and clinical‑oriented platforms and is forging strategic partnerships to move light sheet into pathology workflows. Strategic implication: leadership by platform breadth and an emerging play into AI‑enabled clinical pathology. Partnerships that couple hardware with validated analytics could reshape adoption by hospital pathology departments.
-
Bruker (Billerica, MA, USA) — A major SPIM systems provider with strong ties to research institutions. Strategic implication: solid institutional installed base and service networks provide resilience; competitive moves should focus on tighter integration of clearing workflows and turnkey packages for translational labs.
-
MBF Bioscience (Williston, VT, USA) — Recently commercialized platforms (e.g., SLICE and ClearScope) with award recognition and shortened lead times. Strategic implication: an aggressive product cadence and accessible procurement options reposition the mid‑market; incumbents should defend by accelerating their lower‑cost offerings and consumables ecosystems.
-
Evident Scientific (Tokyo, Japan) — Portfolio targeting sharp optical sectioning and large specimen imaging. Strategic implication: strengths in robustness and application depth make Evident a partner of choice for multi‑site research consortia; collaborations on standardization could expand addressable market.
-
Applied Scientific Instrumentation (Eugene, OR, USA) — Focused on single‑objective light sheet and high‑speed volumetric imaging. Strategic implication: niche technical advantages in speed and live imaging create entry points into functional imaging and pharma screening pipelines.
Recent industry milestones reinforce the strategic picture: ZEISS announced a partnership to co‑develop an inverted light‑sheet plus AI bioinformatics pipeline aimed at clinical pathology; MBF Bioscience has achieved product recognition and rapid fulfillment for SLICE and launched a sub‑micron ClearScope platform in early 2026. These moves illustrate two critical shifts — increasing clinical intent and product commoditization at accessible price tiers — which should be central to 2026 strategies.
Strategic playbook for 2026 (prioritized actions)
Below are recommendation tiers for different stakeholders with suggested near‑term actions (0–12 months) and medium‑term (12–36 months) moves.
-
OEMs & platform vendors
- Near term: finalize 1–2 strategic partnerships (AI, pathology labs, clearing vendors); pilot bundled offerings with fast ROI metrics for translational customers.
- Medium term: modularize product lines to serve both premium research and lower‑cost clinical tiers; develop certification pathways for clinical use where applicable.
-
Imaging core facilities & academic centers
- Near term: prioritize procurement decisions based on total cost of ownership and downstream analytics; pilot multi‑user scheduling and remote access models to justify investment.
- Medium term: negotiate consortia purchasing and shared service agreements to amortize CapEx and expand access.
-
Pharma/CROs and translational labs
- Near term: evaluate light sheet imaging for specific pipelines (e.g., organoid screening, 3D toxicity assessment) using a rapid pilot + ROI template provided in our report.
- Medium term: integrate light sheet datasets into drug discovery analytics stacks to realize productivity gains; consider strategic supplier relationships with joint warranty and data service SLAs.
-
Private investors & M&A teams
- Near term: use the report’s diligence checklists to prioritize targets that combine hardware with proprietary analytics or recurring consumable revenue.
- Medium term: seek bolt‑on acquisitions that fill software/AI gaps and accelerate clinical validation pathways.
Operational signals to watch in 2026
- Acceleration of clinical pilots and any payer guidance that clarifies reimbursement for microscopy‑driven diagnostics.
- New product announcements that reduce delivery lead times or substantially lower purchase price or support cost — these compress procurement cycles.
- Partnerships that package hardware, cloud analytics and pathology workflows; such vertical integrations materially change buyer preferences.
Methodology and access
Our analysis draws on a blend of primary interviews with users and channel partners, product pipeline tracking, pricing and CapEx benchmarking, patent and publication analytics, and proprietary adoption models. Base year is 2025 with historical coverage 2020–2025 and a forecast horizon of 2026–2032 (CAGR 8.41%). Detailed region/type/application tables, model workbooks, and vendor scorecards are available only in the full PW Consulting report and subscription portal.
For leaders who must make 2026 allocation decisions, this preview should clarify the strategic stakes: light sheet microscopy is a growth market with accelerating clinical intent and product democratization — an environment that rewards decisive, well‑timed investments and partnerships. To obtain the full, data‑rich report, customizable modeling files and a vendor‑level playbook, contact PW Consulting or visit our report landing page to license the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Light Sheet Microscopy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


