



PW Consulting: Protective Helmet Market USD 3,525M in 2025, 6.25% CAGR

Protective Helmet Market 2026: Strategic Preview for Decision-Makers
Executive snapshot
The Protective Helmet market is no longer a niche safety segment — it is a maturing, innovation-driven medical-device and personal-protection industry with clearly visible commercial inflection points. Using 2025 as our base year, PW Consulting’s latest analysis shows the global market has expanded from roughly USD 2.6 billion in 2020 to about USD 3.525 billion in 2025, and is projected to reach roughly USD 5.38 billion by 2032, growing at a compound annual growth rate (CAGR) of approximately 6.25% across the 2026–2032 forecast window. These headline numbers matter because they convert fragmented clinical needs, technology shifts and regulatory pressure into tangible commercial opportunities for corporates, investors and health systems planning in 2026.
Protective Helmet Market
Why this research matters for 2026 strategic planning
- Actionability in a consolidation-ready market: Market concentration metrics indicate a sector with room for scale-driven winners. The three- and five-firm concentration ratios point to meaningful leader advantages, but also unexploited pockets where mid-size players can capture outsized returns through specialty positioning, enhanced outcomes or channel innovation.
- Technology-driven differentiation: Additive manufacturing (3D printing), digital scanning and data-enabled treatment monitoring have transitioned from “proof of concept” to operational levers that materially affect unit economics, clinical outcomes and payer conversations. Buyers and partners in 2026 will prioritize vendors who can evidence outcome delta from these technologies.
- Regulatory and reimbursement inflection: With cranial remolding orthoses regulated as Class II medical devices and specific billing codes governing coverage, companies must orchestrate regulatory strategy, clinical evidence generation and payer engagement as a single go-to-market program rather than sequential tasks.
Market dynamics to prioritize
Several macro and micro dynamics converge to shape strategic choices for 2026:
Protective Helmet Market
- Clinical evidence is the new currency. Recent outcomes data demonstrate measurable clinical advantages from 3D-printed cranial remolding orthoses versus traditional thermoformed devices — a difference that can be translated into reimbursement discussions, premium pricing, and hospital procurement preferences. Commercial leaders will invest in prospective outcomes studies and real-world evidence to displace legacy alternatives.
- Channel innovation reduces friction and expands addressable demand. Mobile evaluation platforms and clinic networks that offer low-friction access to assessments materially expand conversion rates from referral to treatment. Newer models, including no-cost screening vans and integrated clinic pathways, lower patient acquisition costs and support earlier intervention windows.
- Payer and coding complexity is non-negotiable. Cranial molding helmets are billed under specialized HCPCS coding and often face exclusionary coverage unless strict clinical criteria are met. Commercial teams must build reimbursement playbooks that combine evidence thresholds, coding compliance and case-level advocacy to protect revenue realization.
- Cost structure sensitivity remains acute. Raw-material and custom-device manufacturing costs vary significantly and are a dominant driver of unit economics. The range of per-device material and production costs necessitates focused sourcing strategies and manufacturing optimization to protect margins as competition intensifies.
Competitive landscape — what to watch in 2026
The competitive field combines dedicated cranial-orthosis specialists, clinical networks and pediatric care providers. Each archetype brings different strategic assets:
Protective Helmet Market
- Device innovators and clinic operators (example archetype): Companies that combine proprietary devices with a distributed clinic footprint can control both product margins and patient pathways, enabling faster data capture and iterative product improvement. Recent product and service launches that expand mobile or clinic-based access exemplify this vertical advantage.
- Orthotic manufacturers focused on pediatric solutions: Manufacturers with a portfolio of modular, prefabricated and custom helmets can pursue scale via channel partnerships (hospitals, orthotics networks) while selectively investing in 3D capabilities for high-margin cases.
- Academic and pediatric healthcare providers: Centers of excellence provide clinical credibility and often lead outcomes publications; they can act as demand hubs for novel devices and influence payer policies through published evidence.
Recent market events emphasize these dynamics: manufacturers launching mobile evaluation clinics to grow early-stage referrals, clinical networks publishing comparative outcomes favoring 3D-printed devices, and device developers securing regulatory clearances that enable market entry into high-opportunity geographies. These events are not isolated — they signal a strategic playbook where access, evidence and regulatory footholds combine to unlock growth.
Regulation, reimbursement and supply — three levers for value creation
- Regulatory sequencing and market access: With cranial orthoses regulated as Class II devices, product development timelines must be synchronized with 510(k)/equivalent filings, clinical follow-up requirements and labeling that supports durable reimbursement. Firms entering new geographies should plan regulatory submissions in parallel with local payer engagement to avoid timing mismatches between clearance and commercial launch.
- Payer engagement and coding strategy: Billing codes and coverage criteria materially affect unit uptake. Organizations that develop payer-friendly clinical protocols, documentation templates and case adjudication support reduce denial rates and accelerate cash collection — a key competitive advantage for 2026.
- Supply chain and cost engineering: Given wide product cost dispersion, targeted investments in additive manufacturing, lean post-processing and supplier consolidation can compress cost per device while improving quality and customization speed. For many players, a hybrid model — in-house 3D printing for complex cases and outsourced thermoforming for commoditized SKUs — will be the optimal near-term approach.
What PW Consulting’s full report delivers — practical, implementable content
Our comprehensive market study goes beyond headline numbers to provide operational tools that leadership teams can deploy immediately. Highlights include:
- Strategic scenario models: three market-growth scenarios with revenue, margin and cash-flow implications for M&A, greenfield expansion and R&D prioritization.
- Go-to-market playbooks: channel segmentation, customer journey mapping, and a 90–180 day commercial acceleration plan focused on referral conversion and payer approvals.
- Clinical-evidence roadmap: recommended study designs, KPIs for comparative-effectiveness claims, and a template for real-world evidence programs that support reimbursement upgrades.
- Manufacturing and cost benchmarks: a build-versus-buy decision framework for 3D printing, supplier scorecards, and cost-sensitivity analyses to inform pricing and margin targets.
- Regulatory and reimbursement playbooks: step-by-step timelines for FDA-class II filings, international clearance sequencing and payer negotiation playbooks tied to clinical thresholds.
- M&A and partnership target lists: prioritized candidate profiles, valuation heuristics and integration checklists for acquiring manufacturing scale, clinical networks or IP.
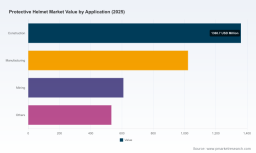
Importantly, while this preview highlights the strategic themes and operational levers, the full report includes the granular regional and application splits, detailed revenue models, and pricing curves that commercial teams and investors use to build board-level plans. We intentionally reserve those segmented datasets for the complete deliverable to preserve their commercial utility — they are the crucible in which your 2026 operating plan should be forged.
Immediate recommendations for executives planning in 2026
- Invest selectively in 3D capabilities tied to evidence generation: Prioritize clinical studies that demonstrate outcome differentials alongside a pilot manufacturing roadmap to scale successful devices rapidly.
- Build payer coalitions early: Engage payers with staged evidence dossiers and pilot reimbursement agreements in target markets to reduce adoption friction at launch.
- Deploy access innovations to expand conversion: Mobile clinics, integrated screening programs with pediatric networks and telehealth-enabled follow-ups can increase case capture and reduce CAC.
- Re-evaluate channel economics: Optimize the mix between direct clinic operations and partnerships with orthotics networks to balance margin, patient access and data capture.
- Use M&A to close capability gaps: Target acquisitions that deliver either manufacturing scale, proprietary IP (e.g., scanning and modeling algorithms) or embedded clinical networks that accelerate evidence collection and market penetration.
Closing — why PW Consulting’s study is the 2026 planning asset you need
As the Protective Helmet market enters a phase where clinical evidence, manufacturing innovation and payer alignment jointly determine winners, strategy without granular, validated market modeling is a risky bet. PW Consulting’s research translates the macro trajectory — a mid-single-digit CAGR from an already multi-billion-dollar base — into specific commercial plays, regulatory roadmaps and operational tactics that can be executed within 12–24 months.
For leadership teams preparing budgets, prioritizing R&D spend, or evaluating M&A in 2026, the full report supplies the segmented market maps, pricing matrices and scenario models that turn strategic intent into executable plans. To access those datasets, proprietary models and company-level benchmarking, request the complete Protective Helmet Market report and the accompanying strategic playbook from PW Consulting.
For detailed analysis of this topic, please visit the official page: Protective Helmet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


