



PW Consulting: Educational Furniture Market to Reach USD 7.07M by 2032 (5.8% CAGR)

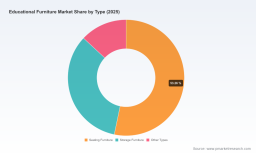
Educational Furniture Market: Strategic Imperatives for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a concise, decision-focused briefing on the educational furniture market that senior leaders must use to calibrate strategy in 2026. This briefing synthesizes long‑run market momentum, competitive posture, regulatory inflection points and raw‑material innovation to surface the practical choices procurement, product and M&A teams will face over the coming 18–36 months. The intent: demonstrate the report’s analytical depth and operational value while preserving the granular segment data and scorecards that are available only in the full PW Consulting study.
Educational Furniture Market
Executive snapshot
The global educational furniture market is on a steady expansion pathway. After a recovery period in the early 2020s, the market reached approximately USD 4.75 Million in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of roughly 5.8% over the forecast period (2026–2032), reaching around USD 7.07 Million by 2032. Market concentration is moderate: the top three players account for about 42.5% of revenue and the top five for roughly 52.3%, indicating room for scale consolidation but also significant opportunities for focused product and service differentiation.
Educational Furniture Market
Why this matters for 2026 corporate decisions
-
Timing and resource allocation: With mid‑single‑digit CAGR and steady expansion through 2032, investment choices now should prioritize durable value creation (product differentiation, after‑sales services, and modular platforms) over speculative geographic plays that require extensive local infrastructure.
Educational Furniture Market -
Portfolio positioning: Buyers and specifiers in education environments increasingly demand research‑backed ergonomics, durability under heavy use, and sustainability credentials. Successful 2026 launches will pair validated pedagogy-driven design with lifecycle cost narratives.
-
Competitive dynamics: The market’s moderate concentration signals that scale matters, but so does specialization. Mid‑sized manufacturers can defend and grow by owning distinct product niches (e.g., flexible seating, outdoor learning spaces, STEM furniture) backed by service propositions.
Market dynamics that will drive decisions in 2026
-
Regulatory acceleration and procurement impact: New and updated standards—most notably recent updates to furniture surface guidelines from recognized standards bodies and national school furniture requirements in major markets—are already shifting specifications for safety, durability and ergonomics. These changes affect procurement cycles, product certification timelines and the claims companies can make in RFPs.
-
Sustainability as a procurement filter: Adoption of recycled composites and engineered materials (for example, solid blocks of recycled plastics used for durable table tops) is no longer niche. Buyers increasingly ask for verifiable recycled content, end‑of‑life pathways and embodied carbon reporting. That changes product sourcing and cost modeling.
-
Outdoor and flexible learning spaces: Guidance on outdoor furniture and the growth of hybrid learning programming are expanding the TAM for durable outdoor and multi‑use furniture. Vendors who can demonstrate weather resistance, low maintenance and compliance with new outdoor standards will win incremental tenders.
Competitive landscape — strategic reads on the core players
The report’s competitive module profiles manufacturers and suppliers across scale, channel reach, technical capabilities and R&D orientation. A brief strategic read on marquee players follows to illustrate how different positioning translates into competitive advantage:
-
Virco — A traditionally strong K‑12 manufacturer with deep distribution in North America. Strengths: scale in classroom staples, OEM-level manufacturing. Strategic angle: leverage existing relationships to bundle services (installation, warranties, refresh programs) and explore lifecycle selling to lock recurring revenue.
-
School Specialty — Strong in early childhood and classroom solutions with an emphasis on distribution and integrated offer sets. Strategic angle: expand value-added services and digital specification tools to reduce friction in large tenders and become the default one‑stop vendor for school districts.
-
HNI Corporation (HON) — Durable, scaled production and a reputation for reliability in institutional channels. Strategic angle: invest in modularity and configurable systems to capture higher-margin, specification-led campus renovation work.
-
Herman Miller — Research-driven design and campus solutions orientation give a premium positioning. Strategic angle: continue to monetize knowledge through consulting, design services and evidence‑based product roadmaps for higher education and research facilities.
-
Smith System & VS America — Innovators in flexible seating and movement‑oriented classrooms. Strategic angle: capitalize on ergonomics trends and outdoor line extensions (following recent product launches in durable outdoor furniture) to address new use cases beyond traditional classrooms.
-
Smaller specialists (Allied USA, K‑Log, Artcobell, Columbia, SAFFE, Alumni Educational Solutions) — These firms often compete on craftsmanship, regional service and niche educational use cases. Strategic angle: partnerships or white‑label agreements with larger distributors, or laser focus on high-margin specialty categories such as STEM lab furniture.
Across suppliers, recent industry activity (product launches, trade show innovations and cross‑category exhibitions) demonstrates that market leaders are attacking both product and channel layers to secure specification wins. Firms that combine product innovation with friction‑reducing procurement support will gain share without requiring deep price cuts.
Regulation and materials: the twin engines re‑shaping product roadmaps
-
Standards and procurement compliance: The recent refresh of furniture surface guidelines and outdoor furniture whitepapers create new certification windows. Companies that pre‑emptively test and certify against the updated standards will shorten supply lead times and reduce rework risk in public‑sector tenders.
-
Material innovation: Use of recycled plastics and engineered composites—materials offering impact resistance, waterproofing and lower cost volatility—are entering standard spec sheets. Firms should evaluate supplier partnerships for these materials and adjust BOM (bill of materials) and warranty policies accordingly.
-
Market entry and localization: National standards in large markets (for example, recent requirements in major Asian jurisdictions) create both barriers and opportunities. Localized production or distribution arrangements may be required to meet mandated product features while maintaining cost competitiveness.
Practical playbook for 2026 (five immediate moves)
-
1) Prioritize standards compliance audits now: Run a prioritized gap assessment of your product portfolio against the latest surface and outdoor furniture standards. Fast followers pay certification costs and lose specification windows.
-
2) Re‑engineer BOMs toward recycled composites where lifecycle advantages are clear: Conduct supplier pilots with recycled solid plastics for tabletops and test endurance metrics. Create a pricing premium narrative based on total cost of ownership.
-
3) Build a specification playbook for tenders: Develop templated performance specs, test reports and certificate packages that procurement teams can drop into RFP responses to reduce procurement friction and shorten sales cycles.
-
4) Monetize services: Introduce design consultation, phased refresh plans and extended warranties as bundled offerings to increase recurring revenue and improve customer retention.
-
5) Pursue targeted partnerships rather than broad geographic expansion: Use joint ventures, licensing and distribution agreements to enter markets with stringent local standards instead of building full manufacturing footprints immediately.
What the full PW Consulting report provides (teaser)
Our full Educational Furniture Market report delivers the operational intelligence procurement, product and M&A teams need to act in 2026:
-
Granular demand maps by product family, application and country-level forecasts across 2020–2032 (note: to drive procurement and commercial tactics we deliberately keep these tables in the full report).
-
Vendor scorecards and competitive benchmarking that combine financial strength, product breadth, R&D investments and channel reach to quantify acquisition targets and partnership fits.
-
Pricing elasticity models and tender‑win probability matrices to optimize bid strategies for public and private education procurement.
-
Operational playbooks for material transition (e.g., recycled composites), certification timelines and supply‑chain risk mitigation plans tied to actual lead‑time and cost scenarios.
We intentionally limit the high‑level briefing to maintain strategic signals while steering readers to the full analysis for segment‑level numbers, regional shares and the proprietary vendor scores that will directly drive procurement and investment decisions.
Concluding perspective
For 2026, the educational furniture market presents a mix of predictable growth and accelerated structural change. Macro growth—anchored by a mid‑single‑digit CAGR and steady market expansion—supports investment. Simultaneously, regulatory updates and a shift to recycled, high‑durability materials are compressing time‑to‑market windows for certified products. The companies that will outpace peers next year are those that translate evidence‑based design into procurement‑ready packages, couple product innovation with services, and treat standards and material transitions as strategic assets rather than compliance costs.
PW Consulting’s full report equips executive teams with the granular models, vendor scorecards and tactical playbooks necessary to convert these market dynamics into defensible 2026 plans. For access to the complete dataset and actionable segment-level directives, please consult the report landing page linked in our release materials.
For detailed analysis of this topic, please visit the official page: Educational Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


