



PW Consulting: SMS Medical Nonwoven Market at USD 402.46M in 2025 — 5.75% CAGR Ahead

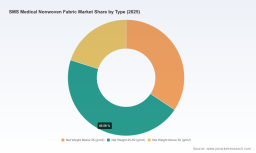
SMS Medical Nonwoven Fabric Market — Strategic Outlook and Decision Playbook for 2026
Executive preview
As healthcare systems, PPE manufacturers, and hospital procurement teams recalibrate for a post‑pandemic steady state, the SMS (spunbond–meltblown–spunbond) medical nonwoven fabric market is entering a phase defined by steady growth, concentrated supply, and a new set of regulatory and sustainability pressures. Our PW Consulting market study — based on a 2025 base year with historical tracking from 2020–2025 and forward projections through 2032 — shows a resilient market trajectory underpinned by a compound annual growth rate (CAGR) of roughly 5.75% over the forecast horizon. Global revenue has expanded meaningfully over the past five years and is expected to continue its upward climb through 2032.
SMS Medical Nonwoven Fabric Market
Why this research matters for 2026 decisions
- Timing: 2026 is the inflection year when incremental demand drivers (elective procedures rebound, routine PPE procurement normalization, and renewed focus on biodegradables) meet the cyclical effects of capacity additions announced in 2024–2025. The study translates those interactions into decision-ready scenarios.
- Capital allocation: Companies considering greenfield lines, capacity upgrades, or converting existing meltblown assets to SMS lines need forward‑looking demand curves and utilization sensitivity models — not just historical size figures. Our model provides scenario-based utilization thresholds tied to price and raw‑material volatility.
- Regulatory readiness: With recent FDA clarifications and 510(k) clearances relevant to SMS constructions, 2026 procurement and compliance strategies must change. The report maps regulatory pathways and the risk/reward of pursuing classification changes or exemptions.
Market trajectory and macro drivers
From a macro standpoint, the SMS medical nonwoven segment has moved from emergency-driven spikes to predictable, healthcare-driven growth. The study quantifies that transition: after the rapid demand shocks of the early 2020s, annual market revenues have expanded and are projected to continue growing at mid-single-digit rates through the end of the decade. This is driven by a confluence of forces:
SMS Medical Nonwoven Fabric Market
- Structural healthcare demand — routine surgeries, outpatient care growth, and expanding access in developing markets.
- Product innovation — manufacturers are introducing SMS variants that balance barrier performance with breathability and comfort, widening the addressable applications beyond traditional gowns and drapes.
- Sustainability and circularity — biodegradable blends and recyclable constructions are becoming procurement differentiators, influencing both OEM selection and premium pricing potential.
- Regulatory de‑risking — clearer FDA guidance on exemptions for certain nonwoven medical devices and recent 510(k) clearances reduce time‑to‑market uncertainty for modification of SMS constructions.
Competitive landscape — what the market structure means for strategy
The market exhibits moderate concentration with the top three players controlling a substantial share and the top five an even larger portion. That structure produces distinct competitive dynamics:
SMS Medical Nonwoven Fabric Market
- Scale advantages: Large global producers have the balance-sheet capacity to invest in multi‑regional capacities and sustainability R&D, enabling them to capture enterprise OEM contracts and hospital system frameworks.
- Regional specialist plays: Mid‑sized and local producers compete by offering customization, faster lead times, or lower cost bases in localized markets.
- Collaborative innovation: The trend toward co‑development partnerships and cross‑licensing (notable between multinational material suppliers and performance‑fabric specialists) is accelerating differentiated product launches.
Key players profiled in the study include established global integrators and regional specialists. The report assesses each on dimensions that matter for strategic counterpart selection and competitive response: manufacturing footprint, product portfolio breadth (including SMMS and reinforced laminates), sustainability roadmap, regulatory clearances, and customer segmentation focus.
Recent industry moves and regulatory context — implications for 2026
- Strategic partnerships and product launches: Several strategic collaborations and new product introductions in 2024–2025 signal a shift from capacity‑race tactics to capability‑led competition. Notably, collaborations targeting sustainable SMS formulations and high‑performance barrier fabrics suggest that technical differentiation — not purely price — will drive premium procurement decisions.
- Capacity expansions: Announcements of manufacturing expansions by leading firms point to upcoming capacity additions that will moderate raw‑material inflation pass‑throughs but will also pressure utilization for smaller producers unless demand growth accelerates as forecasted.
- Regulatory clarity: Recent FDA notices and 510(k) activities have reduced some approval risk for specific SMS constructions, while regional certifications (e.g., CE conformity of blood/biological sample collection materials) open adjacent market opportunities for material suppliers. Commercial teams need to align product claims, testing packages, and submission strategies to exploit these windows.
Strategic playbook for 2026
For executives planning actions in 2026, the study translates macro forecasts and competitive intelligence into a set of prioritized strategic moves. Examples include:
- Capacity and footprint decisions: Use our utilization-trigger matrix to decide between incremental capacity (module expansion), asset retrofits (converting meltblown to SMS lines), or contract manufacturing partnerships. The matrix highlights breakpoints where internal capacity becomes accretive versus outsourcing.
- Product portfolio and differentiation: Prioritize investment in SMS variants that offer validated barrier-breathability trade-offs and in biodegradable/polyolefin blends that meet hospital sustainability procurement criteria. The study includes concept-to-commercial timelines and cost implication models.
- Partnerships and M&A targets: Identify targets that fill capability gaps — whether raw‑material resilience (regional polymer supplies), specialty meltblown technology, or validated regulatory dossiers — and use our valuation overlay to size accretive deals under multiple demand scenarios.
- Regulatory and quality readiness: Align R&D and regulatory teams to the simplified entry pathways for select SMS device classes; prepare 510(k) or equivalent dossiers for high‑value product extensions to minimize launch delays.
- Procurement and supply resilience: Rebalance supplier mix and contract tenors to mitigate polymer feedstock volatility; consider vertical integration or strategic long‑term offtakes for meltblown intermediates where scale advantages justify CAPEX.
What’s in the full report (practical, executable content)
The full PW Consulting report is structured to support immediate decision-making and phased strategy execution. Highlights include:
- Bottom‑up market sizing and validated growth scenarios through 2032, including sensitivity to adoption rates for biodegradable and reinforced SMS constructions.
- Utilization and capacity maps incorporating announced expansions and plausible new builds, with breakeven and payback analyses for different capex pathways.
- Competitive benchmarking across manufacturing footprint, product capabilities, regulatory clearances, and sustainability credentials — enabling prioritization of partners and competitors.
- Segment playbooks (go‑to‑market, pricing, and procurement strategies) for hospital systems, OEMs, and national health agencies — presented as executable 90‑, 180‑, and 360‑day plans.
- M&A screening tool: a short list of target archetypes and valuation ranges tied to synergy and integration complexity.
- Regulatory navigators: step‑by‑step guidance for leveraging recent FDA clarifications and CE conformity precedents to accelerate market entry.
Note: To preserve strategic advantage and respect commercial sensitivity, our public executive summary intentionally omits detailed sub‑segment revenue splits, regional share tables, and explicit pricing ladders. These are included in the full dataset and interactive dashboards available on our report portal.
How to use these insights in boardroom conversations
- Frame capital requests with scenario‑tested utilization outcomes: present conservative, central, and aggressive demand cases derived from the study.
- Use competitive profiles to justify partnership versus build decisions: show how capability gaps will impact time‑to‑contract for large health systems.
- Prioritize regulatory investment: align 510(k) and certification timelines to product launch windows where margin recovery is highest.
- Embed sustainability metrics into procurement negotiation: leverage hospital ESG mandates to capture premium pricing for certified biodegradable or recyclable SMS options.
Closing — a call to action for 2026
The SMS medical nonwoven fabric market is no longer a pure-volume play — it has evolved into a multi‑dimensional battleground where technology, sustainability, regulatory positioning, and regional footprint determine who captures value. Our analysis shows a clear path for companies that can synchronize capacity deployment with differentiated product offerings and regulatory readiness. For executives preparing 2026 plans, the immediate priority is to convert market visibility into executable roadmaps: align capex, partner selection, and compliance investments to the demand scenarios that best fit your risk appetite.
For full access to the detailed breakdowns, sub‑segment forecasts, regional demand analytics, and our interactive scenario tools, request the complete PW Consulting SMS Medical Nonwoven Fabric Market report and dataset.
For detailed analysis of this topic, please visit the official page: SMS Medical Nonwoven Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


