



PW Consulting: Elastomeric Infusion Pumps to hit USD 1.38B by 2032 at 6.98% CAGR

Elastomeric Infusion Pumps Market — Strategic Outlook for 2026 Decision‑Makers
As health systems, payers, and device manufacturers prepare budgets and strategic roadmaps for 2026, the Elastomeric Infusion Pumps Market presents a clear, actionable growth story — but one that requires nuanced interpretation. PW Consulting’s latest industry study (base year 2025; historical series 2020–2025; forecast 2026–2032) quantifies and contextualizes that story: the market reached approximately USD 885.0 Million in 2025 and is projected to expand to roughly USD 975.8 Million in 2026, continuing on a compound annual growth path of 6.98% through the 2026–2032 forecast window, culminating in a market environment materially larger by 2032.
Elastomeric Infusion Pumps Market
Why this study matters for 2026 decisions
-
It converts headline growth into operational choices. The mid-single-digit-plus CAGR translates into concrete implications for manufacturing scale, inventory strategies, and reimbursement negotiations — particularly for players deciding whether to prioritize ambulatory/home infusion versus inpatient channels.
Elastomeric Infusion Pumps Market -
It exposes strategic inflection points. Recent regulatory shifts, reimbursement clarifications, and raw‑material dynamics mean that a “business-as-usual” playbook will underperform. Companies that align product development, quality assurance, and go‑to‑market tactics with these inflection points will capture outsized value.
Elastomeric Infusion Pumps Market -
It equips investors and M&A teams. The market’s structure and growth trajectory are sufficient to support bolt-on acquisitions, contract manufacturing expansions, and niche product entries — but target selection must be informed by clinical use cases, regulatory readiness, and durable reimbursement coding.
Market trajectory — what the numbers imply (not just enumerate)
Across 2020–2025 the market showed resilience through pandemic disruption and shifting care pathways. The 2025 market size (USD 885.0 Million) reflects recovery and adoption of ambulatory infusion paradigms. The forecast baseline (2026) and the 6.98% CAGR through 2032 reflect accelerating demand driven by outpatient surgery, home-administered antibiotic and chemotherapy regimens, and escalating interest in simplified infusion modalities that reduce hospital bed days.
For operators, the implication is straightforward: modest but sustained growth enlarges the economic runway for incremental product investments, while also increasing competitive pressure on manufacturing capacity and component sourcing.
Key dynamics shaping the market
-
Regulatory tightening and device assurance: The FDA’s Infusion Pump Improvement Initiative has raised the bar for documentation, safety assurance cases, and real‑world testing. Manufacturers must now build defensible, traceable risk mitigation dossiers — a nontrivial investment that favors companies with established engineering and quality systems.
-
Reimbursement stability matters more than headline rates: Recent policy actions have reaffirmed separate payment pathways for specific infusion therapies in outpatient settings, preserving access economics for ambulatory devices. The practical effect for manufacturers and hospital purchasing groups is that sustained payer recognition reduces commercialization risk, but success still depends on local coding strategies and contracting execution.
-
Raw‑material and formulation innovation: Advances in medical‑grade elastomers — silicone blends with polyurethane and polyisoprene variants — are materially altering flow stability characteristics and shelf behaviour. These materials choices influence device performance (flow precision, relaxation time), sterilization workflows, and supply‑chain complexity.
-
Cost and capital patterns: Elastomeric devices retain an up‑front cost advantage relative to reusable electronic pumps, particularly for single‑use clinical pathways in ambulatory care. That cost profile makes them attractive in low‑resource and home care settings, but also compresses margins for commodity suppliers.
-
Safety signals and market trust: Isolated malfunction reports and MAUDE entries underscore the reputational sensitivity of infusion devices. Transparent post‑market surveillance and rapid corrective‑action capacity are now a commercial necessity as much as a regulatory one.
Segmentation and what we deliberately withhold here
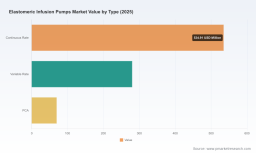
The full report contains granular segmentation by region, device type (continuous vs. variable vs. patient‑controlled), and clinical application (e.g., pain management, antibiotic therapy, chemotherapy), together with multi‑scenario forecasts. In keeping with the “trailer” principle of this executive summary, we demonstrate analytical depth while intentionally withholding the fine‑grained split figures and regional/application-level revenue tables. This is to ensure clients rely on the complete dataset and methodology inside the paid report before making high‑stakes capital or M&A decisions.
Competitive landscape — profiles and strategic implications
-
Baxter International Inc. — Offers SimplFusor ambulatory systems that emphasize mobility and reduced device weight versus electronic alternatives. Strategic view: Baxter’s strength in hospital procurement and established home infusion channels makes it a natural partner for integrated therapy bundles; its risk is slower iteration on next‑gen elastomer materials versus agile niche players.
-
Avanos Medical, Inc. — Producer of the ON‑Q system focused on post‑surgical pain management and disposable components. Strategic view: Avanos’ continued reimbursement recognition for ON‑Q improves its commercial defensibility; competitors should monitor payer coding stability and consider complementary products that broaden procedural applicability.
-
B. Braun Melsungen AG — Offers continuous and variable‑rate systems; recently an EasyPump device had a reported over‑infusion event in early 2026. Strategic view: Quality governance and transparent post‑market response will determine whether the incident becomes a transient reputational issue or a lasting competitive liability.
-
Fresenius Kabi AG — Supplies integrated home infusion solutions; strategic position strengthened by global home care penetration and product breadth. Strategic view: Large OEMs can leverage scale to absorb regulatory and testing costs, but must avoid commoditization of core disposable components.
-
Nipro Corporation & Terumo Corporation — Japanese OEMs with strong ambulatory and hospital ties. Strategic view: Regional manufacturing agility and supply‑chain integration make these players attractive partners for localized rollouts and regulatory filings.
-
ICU Medical, Smiths Medical, Leventon, First Medical Source (InfuLife) — A mix of component specialists, AI‑enabled product developers, and cost‑focused suppliers. Strategic view: The market’s middle tiers are where consolidation and vertical integration will accelerate; companies with differentiated clinical evidence or lower total cost of ownership will be acquisition targets.
Recent developments — catalytic events to watch
-
Early 2026: A reported over‑infusion event associated with a major OEM’s elastomeric device highlighted the need for robust post‑market surveillance and faster communication channels between manufacturers and clinicians.
-
Early 2026: Reimbursement policy updates reaffirmed separate outpatient payment pathways for certain ambulatory pumps, reducing short‑term commercial uncertainty for established products.
-
March 2026: New product introductions (e.g., disposable smart elastomeric pumps) signal a move toward multifunctional devices that address intermittent and continuous therapy needs — a potential vector for differentiation if paired with clinical evidence and payer engagement.
What’s inside the full PW Consulting study (practical contents)
-
Market sizing and forecasting models (2020–2032) with downloadable datasets and sensitivity scenarios.
-
Segment deep dives: methodology, assumptions, and market drivers for device type, clinical application, and region (granular tables and heat maps available in the report).
-
Supply‑chain analysis: raw material sources, test protocols for elastomer blends, supplier concentration risks, and cost pass‑through sensitivities.
-
Regulatory and reimbursement playbook: mapping of FDA expectations, coding pathways, and payer engagement strategies tailored to outpatient and home infusion rollouts.
-
Competitor benchmarking: strategic profiles, capability matrices, recent M&A and product moves, and a strategic 2x2 for go‑to‑market positioning.
-
Commercialization checklists: clinical evidence requirements, field training templates, and pricing scenarios tied to payer negotiations.
-
M&A and partnership playbook: valuation heuristics, integration risks, and three investment cases (bolt‑on, platform expansion, disruptive entry).
Actionable recommendations for 2026
-
Prioritize regulatory readiness now. Prepare robust safety assurance dossiers aligned to the FDA’s guidance — this reduces time‑to‑market risk and enhances buyer confidence.
-
Lock in supply of medical‑grade elastomer formulations and qualify secondary sources. Material performance now differentiates flow stability and shelf life.
-
Design payer engagement around outpatient coding stability. Preserve economic access by documenting total cost of care benefits (reduced inpatient days, readmission avoidance) rather than only device price.
-
Invest selectively in product features that translate to clinical adoption: simple dosing verification, ease of use for home caregivers, and integration with telehealth follow‑up tools.
-
For investors: target mid‑tier suppliers and specialty technology companies with validated clinical use cases — these are the most likely consolidation candidates.
How to use this research
Use the full PW Consulting report to convert macro growth (USD 885.0 Million in 2025, USD 975.8 Million in 2026, 6.98% CAGR through 2032) into tactical plans: determine manufacturing scale‑up timelines, prioritize R&D investments, and shape payer conversations. The executive summary you are reading is a strategic preview; the full dataset, scenario models, and competitor dossiers are required to execute with confidence.
For procurement teams, product leaders, M&A groups, and private equity investors preparing 2026 plans, this study offers a rigorous, executable roadmap — demonstrated methodology, complete transparency on assumptions, and the specific operational checklists you need to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Elastomeric Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


