



PW Consulting: BPO Business Analytics Market to Reach USD 55B by 2032 at 14.2% CAGR

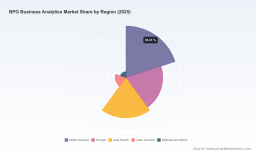
BPO Business Analytics Market: Strategic Imperatives for 2026
As enterprises sharpen their focus on operational resilience and customer intimacy, BPO Business Analytics has moved from a back-office efficiency play to a board-level strategic lever. This PW Consulting briefing introduces our full market research (base year 2025; forecast 2026–2032) and explains why the findings will materially affect vendor selection, sourcing strategy, and investment priorities in 2026. Below we surface the high-level trajectories, competitive dynamics, regulatory headwinds, and actionable priorities—while deliberately reserving the granular segment tables for the full report to encourage deeper engagement with our datasets and models.
BPO Business Analytics Market
Executive snapshot
-
The global BPO Business Analytics market expanded rapidly through the early 2020s—growing from a multi-billion USD market in 2020 to an estimated USD 22.0 Billion in 2025—and is on a path to approximately USD 55.0 Billion by 2032, reflecting a compound annual growth rate (CAGR) of about 14.2% over the forecast period.
BPO Business Analytics Market -
Market concentration is modest: the top three providers account for roughly a quarter of market value, and the top five capture just over a third, indicating sustained opportunity for both large-scale integrators and nimble specialists.
BPO Business Analytics Market -
For 2026 planning cycles, this implies an expanding supplier ecosystem, rapidly evolving product portfolios, and heightened need for disciplined vendor due diligence.
Why this research matters for enterprise decisions in 2026
-
Budget allocation: With near-term budgets pressured by macro uncertainty, procurement teams must justify investments in analytics-enabled BPO by linking spend to measurable financial and non-financial KPIs. Our study provides the ROI frameworks and benchmarking protocols buyers need to model multi-year payoff curves.
-
Vendor selection and partnership design: As vendors shift from transactional outsourcing to co-managed models anchored in analytics, enterprises must evaluate not only cost and scale but data governance, cloud integration, and AI model stewardship. The report profiles capability gaps and partnership archetypes that will influence RFP structures in 2026.
-
Risk and compliance: Increasing regulatory complexity—GDPR, HIPAA, and sector-specific rules—changes the calculus around nearshore vs. offshore delivery, anonymization techniques, and contractual safeguards. Our operational checklists and compliance decision trees are built to inform 2026 contracting and service-level negotiations.
Macro trajectory and what it signals
The market’s expansion—from the early 2020 baseline through a pronounced 2020–2025 acceleration to USD 22.0 Billion, and continuing to a projected USD 55.0 Billion by 2032—signals three structural shifts:
-
Analytics embedded into standard BPO offerings: Analytics is no longer an add-on; it is becoming embedded across process layers and delivery footprints.
-
AI and automation as differentiators: Investments increasingly prioritize predictive and prescriptive analytics tied to automation to reduce cycle times and escalate outcomes.
-
Platformization and partnerships: Cloud-native stacks and strategic cloud partnerships are reshaping how analytics capabilities are bundled with BPO services.
For corporate planners, the implication is clear: 2026 is a year to convert pilots into governed scale, and to embed analytics KPIs into outsourcing contracts rather than treating them as separate initiatives.
Dynamics, constraints and the “noise” shaping decisions
-
Regulatory pressure increases operational complexity. Data protection regimes such as GDPR—and sector-specific controls—raise the cost and process overhead for analytics outsourcing. We model the margin impacts and supply-chain remedies (e.g., tokenization, sovereign clouds) in the full report.
-
Labor market tightness and cost arbitrage stay relevant. Providers are formalizing hybrid delivery architectures—mixing onshore governance, nearshore escalation hubs, and offshore analytics teams—to manage cost and continuity. We quantify trade-offs in our scenario analyses.
-
Data quality and integration bottlenecks are the practical constraint to analytics ROI. The firms that win in 2026 will excel at end-to-end data orchestration—not merely at model-building.
What the full report delivers (practical, decision-ready content)
Our research is structured for immediate operational use by sourcing, finance, and technology leadership. Key inclusions:
-
Actionable use-case playbooks that map analytics capabilities to business outcomes and typical time-to-value for BPO engagements.
-
Vendor capability heatmaps and maturity scoring across data management, model governance, automation, vertical expertise, and cloud partnerships.
-
Contract and SLA templates with embedded metrics, penalty frameworks, and governance checkpoints tailored to analytics-led BPO.
-
Implementation roadmaps and an Analytics Center of Excellence (CoE) blueprint to migrate from pilot to pervasive deployment within 12–24 months.
-
Financial models and sensitivity analyses for build vs. buy vs. hybrid sourcing decisions, including headcount delta, run-rate savings, and reinvestment timelines.
-
Regulatory compliance matrices and operational controls for cross-border data flows and sectoral requirements.
-
A concise M&A and partnership playbook highlighting when to partner with a specialist, when to acquire capabilites, and how to structure joint offerings with cloud providers.
Competitive landscape — how to read the vendor field
The vendor universe is best understood in three clusters, each with distinct implications for enterprise buyers:
-
Global systems integrators and tier-1 BPOs (e.g., Accenture, Capgemini, Cognizant, IBM, TCS). These players compete on end-to-end transformation capability, strong cloud alliances, and the ability to embed analytics into large-scale BPO contracts. They are the default choice for complex, cross-border programs where governance and integration risk are paramount.
-
Analytics-first and process-specialist firms (e.g., EXL, Fractal, Genpact, WNS). These vendors bring domain-rich predictive models and verticalized analytics assets—useful when outcomes require deep process nuance, such as finance, healthcare, or supply chain optimization.
-
Contact-center and experience specialists (e.g., Teleperformance, Concentrix, Sitel, Alorica). Their advantage lies in high-volume interaction analytics, speech/text intelligence, and real-time CX optimization—critical when customer experience metrics are the core KPI.
Across the spectrum, we observe active productization: several vendors launched or upgraded AI analytics platforms through 2025 (notable examples include major platform releases and strategic partnerships announced in mid-to-late 2025). These moves accelerate de-risking of enterprise adoption but also heighten the importance of integration and change management capability.
Strategic recommendations for 2026 planning
-
Prioritize outcome-linked commercial models: Move away from pure FTE pricing toward outcome- and value-sharing models that align incentives around predictive accuracy, automation yield, and cost-to-serve reductions.
-
Establish a vendor segmentation and tiering framework: Use a two-step RFP where the first stage validates data governance and cloud posture, and the second stage pilots the analytics use-case at scale.
-
Invest in a Federated Analytics CoE: Blend centralized standards (model governance, tooling, data security) with embedded analytics talent in the business units to accelerate adoption.
-
Lock in regulatory controls early: Require vendors to demonstrate privacy-by-design, anonymization tooling, and jurisdictional data residency options as part of baseline compliance criteria.
-
Plan for talent scarcity: Prioritize vendor partnerships that provide managed analytics talent or robust automation that reduces reliance on scarce senior data scientists.
-
Adopt phased scaling: Pilot in high-value workflows (e.g., collections, claims triage, or procurement analytics), instrument the outcomes, and then scale with contractual incentives tied to measured performance.
Short checklist for procurement and technology leaders (next 90 days)
-
Map three priority use cases where analytics can deliver measurable cash or NPS improvement within 12 months.
-
Run a quick vendor capability vetting using a 12-point governance checklist (data residency, model explainability, cloud integration, SLA measurables).
-
Secure pilot budget and define success gates that convert pilots into enterprise-wide programs upon meeting pre-agreed ROI thresholds.
-
Negotiate clauses for data portability and IP reuse to avoid long-term lock-in as platforms evolve.
Methodology and how to use the full study
The full PW Consulting study combines primary interviews, supplier financial analysis, client-side surveys, and bottom-up TAM modelling calibrated to observed vendor revenues (base year 2025) and forward-looking adoption curves through 2032. For procurement and strategy teams, the report should be used both as an input to annual planning cycles and as an evolving decision-support tool. We provide dynamic worksheets and scenario models in the full package to tailor the findings to your organization’s size, vertical exposure, and risk appetite.
Conclusion and next steps
The BPO Business Analytics market presents a window of strategic leverage in 2026—where carefully structured pilots, disciplined vendor selection, and strong governance can translate into disproportionate advantage. Our research quantifies that opportunity at a market level (noting the expansion from the early 2020s through USD 22.0 Billion in 2025 and the projected USD 55.0 Billion by 2032 at a 14.2% CAGR), and offers the playbooks, contract language, and benchmarking tools to act now.
We have intentionally summarized actionable insights here while withholding full granular segmentation and proprietary vendor scoring details to preserve the research’s decision-making value. Access the complete PW Consulting BPO Business Analytics Market report to obtain the full datasets, region- and application-level breakdowns, vendor heatmaps, and downloadable implementation tools designed to guide your 2026 strategy.
For detailed analysis of this topic, please visit the official page: BPO Business Analytics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


