



PW Consulting: HRT market hits USD 33.68 Million by 2032, 6.98% CAGR

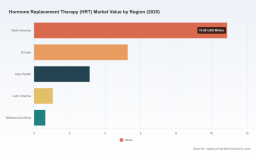
Hormone Replacement Therapy (HRT) Market: Strategic Outlook for Corporate Decision‑Making in 2026
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused, executive‑level preview of our new HRT market study — a practical intelligence product built for companies making portfolio, commercial, manufacturing, and M&A decisions in 2026. This introduction lays out the strategic implications that flow from the market’s trajectory, regulatory inflection points and competitive dynamics, while deliberately withholding the granular segment tables and product‑level financials that subscribers will find in the full report.
Hormone Replacement Therapy (HRT) Market
Macro picture: where the HRT market is now and where it’s headed
Using 2025 as the base year and tracking historical performance from 2020–2025, our modeling shows the global HRT market has expanded steadily in recent years and is positioned for sustained growth over the coming decade. The market grew from a modest base in 2020 to a larger, more commercially meaningful size by 2025, and our forecast through 2032 anticipates continued expansion at a compound annual growth rate (CAGR) of approximately 6.98% over the 2026–2032 period. Under PW Consulting’s scenarios, the market continues to benefit from improved access, evolving clinical guidance, and an active product pipeline that includes both hormonal and non‑hormonal therapeutic options.
Hormone Replacement Therapy (HRT) Market
These topline dynamics are the essential inputs for 2026 planning cycles — informing revenue run‑rates, capacity investments, pricing strategy and M&A valuation multiples. The full report contains the year‑by‑year market figures and scenario sensitivities used to stress‑test business plans; this preview focuses on what those numbers mean for strategic choices this year.
Hormone Replacement Therapy (HRT) Market
Why 2026 is an inflection year
- Regulatory and safety re‑profiling: Late‑2025 actions by the U.S. regulator — including approval of a generic version of a long‑standing conjugated estrogen product and removal of broad black‑box warnings for menopausal HRT formulations — materially change the safety narrative and the economics of the category. Those changes accelerate adoption in some patient cohorts and invite payors to reconsider coverage policy and cost‑effectiveness thresholds.
- Non‑hormonal entrants: Approval of a novel non‑hormonal agent for menopausal vasomotor symptoms in late 2025 expands treatment choice and redefines therapeutic positioning. Companies must now model cross‑elasticities between hormonal and non‑hormonal options when forecasting uptake and pricing.
- Generics and price pressure: The first generic approvals for legacy branded HRTs in decades create immediate competitive pressure on brand volumes, margins and formulary positions. At the same time, generics improve affordability and may expand addressable patient populations.
- Supply constraints and operational risk: Early‑2026 shortages of multiple estradiol transdermal patch suppliers illustrate that demand growth and manufacturing complexity can create acute availability risk. Companies with manufacturing flexibility or contract manufacturing relationships can translate scarcity into strategic advantage; those without must prepare contingency plans.
- Localized reimbursement shifts: State‑level coverage mandates for menopausal therapies that came into force in 2026 create patchworks of access that commercial teams must navigate — changing market entry sequencing and reimbursement dossiers.
Strategic implications for 2026 corporate planning
- Portfolio prioritization: Reassess launch sequencing and lifecycle investments with three lenses — clinical differentiation (safety/efficacy), payor access (coverage & prior authorization risk) and manufacturing resilience. Where regulatory actions de‑risk safety perceptions, re‑allocate promotional dollars to volume capture and adherence programs; where generics are imminent, accelerate differentiated formulations or delivery systems.
- Pricing and contracting: Expect dual pressures: downward list‑price pressure from generics and upward rebate/contracting pressure from payors seeking budget predictability. Build flexible pricing playbooks that include indication‑tiering, performance‑based agreements for symptomatic outcomes, and volume hedging in supply contracts.
- Manufacturing & supply chain strategy: Shortages in patch supply in early 2026 are a practical warning. Invest in capacity buffering, dual‑sourcing, and finished‑product inventory for critical SKUs. Evaluate near‑term investments in manufacturing scale only when backed by scenario‑specific demand forecasts and ROI thresholds in our model.
- M&A and partnership screening: The market’s moderate concentration and mixed incumbency create M&A arbitrage opportunities — from acquiring transdermal platform specialists to in‑licensing non‑hormonal assets. Prioritize targets that deliver immediate manufacturing capacity, differentiated delivery technology, or clear payor value propositions.
- Regulatory & market access preparedness: Update labeling strategies and real‑world evidence (RWE) plans to capitalize on the removal of broad safety warnings and to defend brand positioning against generics. Payers will increasingly request RWE that demonstrates symptom control, QoL benefits, and health‑economic outcomes.
- Commercial model recalibration: Hybrid channels (specialty clinics, primary care, telehealth) are reshaping access. Reallocate field force and digital spend to capture touchpoints where menopausal care is now being delivered, and design education programs for clinicians and patients aligned with the new safety narrative.
Competitive landscape: positioning and tactical moves
The HRT landscape comprises a mix of large integrated pharmaceutical companies, specialty manufacturers and aggressive generic producers. Market concentration metrics indicate a market that is neither highly consolidated nor atomized — the top three firms account for a material share but a long tail of players remain competitive. This structure favors differentiated branded products with strong clinical evidence and cost‑efficient generics competing on price and supply reliability.
- Global pharmaceutical leaders with established HRT portfolios (including major firms based in the United States and Europe) retain advantages in brand recognition, distribution networks and clinical legacy assets.
- Generic and specialty manufacturers hold critical roles in affordability and access; their operational reliability is now a procurement criterion for health systems and payors.
- New non‑hormonal entrants complicate prescribing algorithms and create headwinds for commoditized hormonal products — but also expand the treatment paradigm for patients who cannot or prefer not to take hormones.
Specific firms profiled in our research include leading multinational therapy originators, prominent generic manufacturers, and niche patch/route‑of‑administration specialists. Each profile in the full report contains an actionable assessment: revenue exposure to imminent generic erosion, pipeline roadmaps, manufacturing footprint, supply risk scores and suggested competitive countermeasures.
What the PW Consulting HRT Market report delivers — practical content for 2026 decisions
- Rigorous market sizing and forecasting model (2020–2025 history, 2026–2032 scenarios) with scenario toggles for regulatory shifts, generic entry timing and non‑hormonal uptake.
- Commercial playbooks: launch sequencing, pricing & contracting templates, payor negotiation scripts and patient support program blueprints tailored to HRT subsegments.
- Supply chain and manufacturing risk matrix with mitigation roadmaps — capacity build vs. contract manufacturing tradeoffs analyzed under multiple demand scenarios.
- Competitor and product intelligence dossiers covering clinical profiles, manufacturing capabilities, recent approvals and regulatory events; actionable SWOTs and likely moves for each major player.
- Regulatory tracker and policy impact assessment — including the late‑2025 FDA actions and state‑level reimbursement mandates — with quantified impacts on demand and price.
- M&A and partnership screening tool that ranks targets by strategic fit, valuation sensitivity and integration complexity.
- Real‑world evidence (RWE) playbook and health economic models to support coverage negotiations and formulary positioning.
Note: Consistent with our “preview” approach, this introduction highlights the frameworks and strategic implications of our analysis while withholding the granular segment tables (route of administration, gender and regional splits), product‑level revenue streams, and downloadable financial models. These are available only in the full report and client portal.
How to use this research in your 2026 decision cycle
- Board and investor briefings: use the topline forecasts and scenario summaries to set realistic top‑line expectations and capital allocation plans.
- Operating plan refresh: feed our demand scenarios into your FY‑2026 manufacturing, procurement and commercial budgets to stress‑test capacity and cash flow.
- Portfolio and R&D prioritization: re‑score projects by commercial viability under new safety and access dynamics; accelerate those with payor‑friendly outcomes or durable differentiation.
- M&A diligence: apply our target screening outputs to prioritize partners and acquisition candidates that reduce supply risk or provide differentiated delivery platforms.
- Market access campaigns: adopt the RWE and pricing templates to accelerate formulary wins and state‑level reimbursement approvals.
In short, our HRT market study is designed to be immediately operational — not just descriptive. It aligns quantitative forecasts with tactical playbooks so that commercial, supply, regulatory and corporate development teams can act with clarity in 2026.
Next steps and access
If your team is prioritizing market share defense, margin protection, manufacturing resilience or inorganic growth in HRT during 2026, PW Consulting’s full report supplies the detailed segmentations, product‑by‑product financials, and downloadable scenario models you will need. The full study also contains the proprietary segmentation breakouts and the exact route‑of‑administration, gender and regional forecasts that underpin the strategic recommendations summarized here — data we withhold in this preview to preserve the report’s commercial value.
Visit our HRT Market research page to access the comprehensive report, schedule a briefing with our analysts, or request a customized workshop that maps the findings directly to your portfolio and operating plan.
For detailed analysis of this topic, please visit the official page: Hormone Replacement Therapy (HRT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


