



PW Consulting: Mirrors Market at USD 215M in 2025, Poised for 7.82% CAGR to 2032

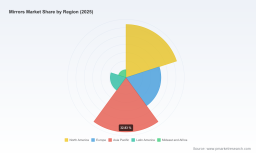
Mirrors Market — Strategic Primer for 2026 Decision-Makers
As companies plan product roadmaps, capital allocation and partnerships for 2026, the mirrors sector presents a mix of steady, technology-fueled growth and fragmentation that rewards targeted playbooks. This primer introduces the PW Consulting Mirrors Market study and explains why the research is indispensable for executives who need to convert macro momentum into actionable strategies while avoiding commoditization traps.
Mirrors Market
Snapshot: scale, trajectory and market structure
Measured on a consistent base-year (2025), the mirrors market has shown resilient expansion through the early 2020s and is entering a multi-year growth phase. The total market rose from approximately USD 163 million in 2020 to roughly USD 215 million in 2025. Under our forecast horizon (2026–2032), the market is expected to grow at a compound annual growth rate (CAGR) of 7.82%, reaching an estimated USD 345 million by 2032. These headline dynamics reflect a blend of steady end‑market demand (construction, hospitality, residential retrofit) and rapid adoption of feature-rich products (LED integration, smart displays, safety-laminated architectural glass).
Mirrors Market
Two structural features matter for strategy: first, the market concentration is low — the top 3 players account for under a quarter of the market and the top 5 still capture only slightly more. Second, growth is not uniform across product categories and channels; it is concentrated where technology, regulatory requirements, and high-performance materials intersect. Our study keeps the full set of segment-level numbers and model outputs gated — this primer surfaces the strategic implications while protecting the granular data that will guide operational decisions.
Mirrors Market
What the full report provides (practical, operational content)
- Proprietary demand model (2020–2032) with scenario toggles for raw material inflation, construction cycles, and smart-product penetration; downloadable worksheets allow CFOs to test capital plans under three macro scenarios.
- Go-to-market playbook tailored to five buyer archetypes (architectural/contracting, hospitality FF&E, residential premium, OEMs for appliances/automotive, and high-tech industrial) — each with supplier negotiation levers, margin benchmarks, and channel-mix optimization.
- Detailed supplier scorecards and capability mapping for more than twenty manufacturers and integrators; these include product technology roadmaps, manufacturing lead-time matrices, and recommended partnership types (JV, contract manufacturing, IP licensing).
- Regulatory and standards matrix highlighting current committee activity and anticipated changes in safety, optical performance, and eco-compliance—built to feed procurement and product-engineering roadmaps.
- M&A and partnership playbook with valuation multipliers calibrated to public and private transactions in related glass and smart-fixture markets.
Why this matters for 2026 choices
- Investment Prioritization — With a mid‑single digit-to-low double‑digit growth trajectory, companies must choose where to allocate scarce capex. The report’s scenario-enabled demand model turns headline CAGR into actionable capital timing.
- Product Differentiation — Margin expansion will come from functionality and system integration (embedded lighting, anti-fog, vanishing-display capability), not from basic mirror commodities. Our research shows where to prioritize R&D versus price competition.
- Supply‑chain Resilience — Raw-material costs and processing technologies (e.g., advanced silvering, laminations for safety, and optical coatings) are central to performance. The report maps supplier risk and bargaining power across those nodes.
- Compliance and Standards Exposure — ANSI-accredited U.S. Technical Advisory Groups and ISO-related committees are active in mirror-related standards; early alignment reduces late-stage redesign risk for international projects.
Competitive landscape — positioning and strategic moves
The competitive set is a mosaic of specialist innovators, architectural glass conglomerates, and regional high-volume producers. That fragmentation creates opportunity for targeted consolidation and vertical integration — but not through a one-size-fits-all approach.
- Smart and luxury integrators: Companies focused on illuminated, connected and smart mirrors have a clear premium position. These firms specialize in electronics integration, user experience and hospitality deployments. They typically excel at product design and channel relationships with premium hotel brands and high-end residential specifiers.
- Architectural and industrial glass incumbents: Large glass producers with advanced processing (edge protection, laminates, optical clarity enhancements) have the upstream scale and R&D that matter for large construction or safety‑critical projects. Their strength is materials science and production efficiency for volume or customized architectural panels.
- Local fabricators and decorative specialists: Regional players, artisan makers and mass-volume producers serve distinct niches — from oversized commercial mirrors to decorative framed products — and compete primarily on lead time, customization and local codes compliance.
- Technology disruptors: A small but notable set of firms pursue display‑mirror convergence (switchable mirrors, embedded screens, AR-capable surfaces). These players draw interest from retail, hospitality and experiential signage markets and require partnerships with electronics suppliers and software integrators.
Our company profiles in the report synthesize each player’s strategic footprint: core product offerings, go-to-market channels, geographic strengths, and technology bets. We also catalogue recent moves that matter for partnership and competitive response — product catalog updates from leading LED mirror manufacturers and highly publicized innovation projects (including experimental space-reflection initiatives that signal new demand vectors) are highlighted and analyzed for their strategic ripple effects.
Near-term growth pockets and strategic responses
- Feature-led premiumization: LED lighting, tunable color temperature, anti‑fog systems and integrated controls are now table stakes in premium segments. Suppliers should package optics, electronics and installation as bundled offerings to extract higher margins.
- Commercial retrofit demand: Hospitality and large-scale renovation projects continue to generate steady replacement cycles. Faster lead times and standardized modules reduce project friction.
- Safety and architectural applications: Laminated, distortion‑controlled mirrors for public spaces and institutional projects are growing in importance — driven by both specification standards and insurance considerations.
- High-tech industrial uses: Advanced mirrors for process environments (including sophisticated clean-room applications) require tighter tolerances and specialized coatings; these are higher-margin but require close engineering partnerships with end-users.
Key risks and mitigating actions
- Commoditization risk: Over-reliance on basic glass and commodity silvering squeezes margins. Mitigation: invest selectively in value-added features or lock in long-term supply agreements with premium processors.
- Supply volatility: Raw material shifts and processing capacity constraints can cause lead-time spikes. Mitigation: dual-sourcing strategies, regional buffering, and contract terms that index to validated cost drivers.
- Regulatory shifts: Standards activity can force product changes mid-cycle. Mitigation: engage early in standards committees and maintain a regulatory watch integrated into product development sprints.
- Channel complexity: Varying procurement practices across architectural, hospitality and retail channels increase go-to-market costs. Mitigation: develop channel-specific bundles and a dealer-partner certification program to control brand experience and margins.
Recent developments that affect near‑term strategy
- Market players continue to refresh portfolios — including updated LED and smart mirror lines — creating short windows of opportunity for distributors and installers to capture retrofit projects.
- High-visibility innovation projects (from avant-garde reflector concepts to space-based experiments) are expanding the strategic conversation about non-traditional use cases; companies should track these as potential future demand generators or PR opportunities.
- Standards committees remain active and can materially affect product specifications and procurement requirements. Firms with active standards participation reduce time-to-market friction for regulated projects.
- Operationally, some public accounts of material choices (for example shifts from metal to glass reflectors in specific institutional settings) highlight the importance of monitoring end-user safety and performance preferences — not just price.
How to use the full PW Consulting mirrors study
The full Mirrors Market report is built for busy leaders who need executable plans, not just descriptive analysis. Use it to:
- Stress-test capital projects against three macro scenarios and prioritize rollouts by expected ROI over a 3–5 year horizon.
- Design product roadmaps that assign R&D resources to features with the highest willingness-to-pay in target channels.
- Execute M&A and partnership screening using our calibrated valuation multipliers and supplier scorecards.
- Align procurement and engineering timelines with anticipated standards updates to avoid redesign penalties.
For executives who require the segment-level breakdowns, company scorecards, and the downloadable demand model that underpin these strategic recommendations, the PW Consulting Mirrors Market study provides the complete datasets and scenario tools. Access to those granular outputs is available through the report hub — where clients can also initiate a custom benchmarking or a live model workshop tailored to their portfolio.
PW Consulting has structured this study to be a decision-ready input for 2026 planning cycles. If your 2026 choices include new product investments, channel expansion, or M&A exploration, the right quarter to align strategy and budget is now.
For detailed analysis of this topic, please visit the official page: Mirrors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


