



PW Consulting: Low-Voltage DC Circuit Breaker Market to Reach USD 320.2M by 2032 at 7.0% CAGR

Low Voltage DC Circuit Breakers: Strategic Outlook for 2026 Decision-Making
Executive preview
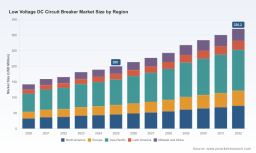
The Low Voltage DC Circuit Breaker market is transitioning from niche engineering challenge to strategic battleground for utilities, inverter makers, balance-of-system vendors and industrial OEMs. Between 2020 and 2025 the market expanded from USD 142.3 Million to USD 200.0 Million (base year 2025), and our forecast projects a continuation of that momentum to approximately USD 320.2 Million by 2032 at a 7.0% CAGR over 2026–2032. That trajectory masks important inflection points: material-cost volatility, standards updates, and rapid product evolution around higher-voltage DC distribution and solid-state protection create both risk and opportunity for firms that need to commit capital in 2026.
Low Voltage DC Circuit Breaker Market
Why this research matters to 2026 corporate plans
-
Capital allocation: With the market expanding meaningfully through the forecast horizon, companies that finalize manufacturing CAPEX, tooling spend or capacity-sharing agreements in 2026 will capture the early-adopter premium in high-growth niches.
Low Voltage DC Circuit Breaker Market -
Product roadmap timing: The convergence of higher-voltage PV strings, energy storage deployments, and faster EV DC charging protocols creates a narrow window where product specification choices made now determine certification cycles and go-to-market readiness into 2027–2028.
Low Voltage DC Circuit Breaker Market -
Supply chain posture: Raw material shocks in 2025 and the cascading cost effects on manufacturing economics mean procurement strategies and hedging approaches decided in 2026 materially affect gross margins into 2028.
Market trajectory and macro drivers
Our historical build (2020–2025) shows steady adoption across renewable and industrial applications—growth accelerated notably as storage and fast-charging use cases matured. The forecast (2026–2032) embeds a 7.0% CAGR that reflects continued end-market expansion as well as gradual migration toward higher-voltage DC topologies and greater electrification of transportation and industrial automation.
Key demand drivers evaluated in the study include the accelerating roll-out of battery energy storage systems (BESS), increasing PV string voltages and inverter architectures, and the mainstreaming of DC fast-charging. Conversely, cost-side pressures—from base commodity shifts to new certification requirements—shape practical pricing and margin outcomes for manufacturers and distributors.
Competitive landscape: who matters and why
The report profiles leading and emerging suppliers, assessing strategic positioning, product portfolios, channel models and near-term capacity moves. Market concentration is moderate: the top three suppliers account for roughly 54% of identifiable market revenue while the top five account for about 65%—enough to influence pricing dynamics but leaving space for regional specialists and innovative entrants.
-
ABB (Switzerland) — A full-spectrum provider with conventional MCBs/MCCBs and solid-state offerings tailored to solar and storage DC distribution. ABB’s portfolio is notable for broad channel reach and system integration capability (link: https://new.abb.com/low-voltage/direct-current-systems).
-
Eaton Corporation (Ireland) — A major global supplier of DC-rated molded case breakers, including solutions designed specifically for PV and BESS applications, with proven designs up to 1000 VDC (link: https://www.eaton.com).
-
Siemens AG (Germany) — Focused on modern low-voltage installations with tried-and-tested series targeting renewables, data centers and industrial use (link: https://www.siemens.com).
-
Mitsubishi Electric (Japan) — Advanced breaking technologies for machinery and electrical equipment; a supplier with deep industrial OEM relationships (link: https://www.mitsubishielectric.com/fa/products/lvd/lvcb/index.html).
-
LS ELECTRIC (South Korea) , Fuji Electric (Japan) , CHINT Group (China) , Hager Group (Germany) , and Chinese OEMs such as Beny and Chinasuntree — each brings distinct advantages, from smart-power integration and cost-competitive manufacturing to specialized enclosures and PV-focused product sets (see company sites cited in report).
Recent tactical moves matter. Fuji Electric’s 2025 investment to expand transmission & distribution capacity—with operations ramping in FY 2026—reshapes regional supply availability. Several OEMs used 2025–2026 trade shows to preview higher-voltage and IP-rated solutions (notably 1500 V capabilities), signaling intent to compete on both performance and system compatibility.
Supply chain and cost dynamics
Material composition and price volatility are no longer secondary issues. Our cost-model deep dives show copper is a dominant raw-material line item—accounting for roughly 45% of material costs in low-voltage electrical equipment—with silver and copper together representing an even larger share of critical metal exposure. Since July 2025, silver prices have surged substantially (well over 400%), while copper has also experienced steep increases (>140%). These moves have immediate margin implications for conventional contact-based breakers and even more pronounced effects for products where precious metals are used in contacts or plating.
For procurement and operations leaders, the combination of concentrated supplier base for certain specialty subcomponents, upward material pressure and long lead times for precision tooling produces three practical levers we quantify in the report: (1) design-for-material-efficiency pathways, (2) alternative contact alloys and coating strategies, and (3) inventory/forward-buy frameworks tailored to hedging costs without overexposure.
Regulatory and standards outlook
Standards evolve rapidly and directly influence product architecture and time-to-market. EN IEC 60898-3:2025 introduces clearer expectations for household DC breakers up to 440V, while industry deployments continue to require compliance with UL 489 B and IEC 60947-2 for solar PV and energy storage systems. Our regulatory risk scenarios examine certification timelines, required lab modifications, and the cost of incremental testing for higher-voltage ratings—all crucial for product managers and compliance teams planning 2026 releases.
Strategic implications and actionable recommendations for 2026
-
Prioritize modularity: Build product roadmaps that allow incremental voltage and interrupting-capacity upgrades without a full redesign. This reduces certification cycles and amortizes test costs across families.
-
Lock targeted capacity early: For companies intending to scale, secure manufacturing slots or partnerships in 2026—especially for enclosures and high-precision contacts—before 2027 demand surges.
-
Hedge raw-material exposure: Combine strategic sourcing with design choices that reduce precious-metal usage, and explore long-term offtake agreements for copper and alternative alloys.
-
Invest in standards readiness: Dedicate a certification roadmap tied to the product launch cadence—missing a standards milestone can delay market entry by quarters and hand share to more agile competitors.
-
M&A and partnership playbooks: Consider bolt-on acquisitions for system integration capabilities (e.g., relays, sensing electronics) or partnerships for manufacturing scale; the report includes diligence templates and valuation sensitivities focused on 2026 timing.
Report content: what you will find inside
The full PW Consulting study is organized to be immediately operational for strategy, product and commercial teams. It contains:
-
Market sizing (USD Million) and historical trend analysis (2020–2025) with a base year of 2025, plus a detailed forecast through 2032 with scenario sensitivity to material prices and standards adoption.
-
Competitive benchmarking across product capabilities, channel strategies, price positioning and near-term capacity events—covering both global leaders and regional specialists.
-
Supply-chain cost models that quantify exposure to copper and silver, and design trade-offs to preserve margin under high-price scenarios.
-
Regulatory and certification timelines, mapped to product architectures and time-to-market impacts.
-
Actionable go-to-market playbooks for OEMs, distributors and EPCs including pricing strategies, channel incentives and systems-integration approaches tailored to 2026 deployment windows.
-
Risk matrices and scenario planning templates designed to support 2026 board-level investment decisions—concisely mapping probabilities, impacts and mitigations.
To preserve commercial value and to respect our clients’ need for proprietary segmentation, this introduction intentionally omits granular regional, type and application splits. The full report contains those segment-level data and the underlying model that powers our forecasts.
How to use this study in 90 days
-
Month 1 — Align: Run the report’s scenario workshop with product, procurement and business leaders to align on which scenario(s) your company will prioritize.
-
Month 2 — Commit: Finalize CAPEX and sourcing decisions for critical-path components, and begin certification scheduling for planned product updates in 2027.
-
Month 3 — Execute: Implement hedging and inventory plans, initiate any targeted M&A or strategic partnership discussions, and deploy the go-to-market testing plans included in the study.
Conclusion and next steps
For firms making binding strategic choices in 2026, the intersection of robust market growth (USD 200.0 Million in 2025 to an expected USD 320.2 Million by 2032 at a 7.0% CAGR), material-cost volatility, and evolving standards creates a compressed set of decision points. The full PW Consulting Low Voltage DC Circuit Breaker Market report provides the granular segmentation, supplier-level intelligence and executable playbooks required to convert market momentum into profitable growth. For access to detailed segment splits, supplier scorecards, and our model workpapers, consult the source report page and schedule a briefing with our industry team.
For detailed analysis of this topic, please visit the official page: Low Voltage DC Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


