



PW Consulting: M-Xylylenediamine Market — USD 638.5M by 2032

M‑Xylylenediamine (MXDA) Market — Strategic Outlook to 2032
Executive preview
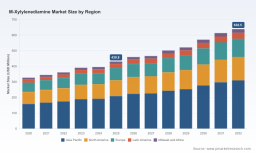
As companies finalize budgets and capital plans for 2026, a razor‑sharp understanding of the MXDA value chain — from feedstock exposure to end‑use formulation dynamics — is a strategic imperative. Our latest market study (base year 2025, forecast 2026–2032) synthesizes five years of historical performance with probabilistic forecasts and stress‑tested scenarios to support board‑level decisions and commercial playbooks. The global MXDA market has expanded materially since 2020, reaching an estimated USD 430.8 Million in 2025 and is projected to grow to the high‑six‑hundreds by 2032 under a central case CAGR of 5.8%. This research is designed to translate that macro trajectory into actionable choices for producers, buyers, investors and policymakers in 2026.
M-Xylylenediamine Market
Why this matters for 2026 decision cycles
Three market realities converge to make MXDA a boardroom issue in 2026:
M-Xylylenediamine Market
- Demand acceleration tied to downstream industrial growth (notably advanced epoxy systems and specialty polyamides) is lifting the market beyond historical cyclicality, creating medium‑term capacity questions for incumbents and entrants alike.
- Feedstock and regulatory pressure are reshaping cost structures and product positioning. MXDA manufacture remains dependent on petro‑derived intermediates (m‑xylene and ammonia), which exposed producers to volatile crude‑linked feedstock swings — a dynamic that produced spot feedstock fluctuations in recent years and continues to influence margins and commercial terms.
- Regulatory and sustainability vectors (EU REACH obligations, low‑emission directives, and scrutiny under the EU Green Deal) are accelerating demand for low‑emission and bio‑based solutions while raising compliance costs for conventional producers.
What this report delivers — practical, decision‑grade outputs
The study is built as an operator’s toolkit rather than an academic paper. Key deliverables include:
M-Xylylenediamine Market
- Top‑down market sizing (historical 2020–2025 and forward to 2032) with probabilistic scenarios reflecting oil price and regulatory shocks.
- Supply‑side forensic: asset maps, capacity trackers, and a concentration analysis that highlights high market share among the leading suppliers (three‑player concentration is material).
- Cost and pricing models that decompose margin by feedstock, conversion efficiency and freight/insurance exposures — including sensitivity analytics for m‑xylene price moves and ammonia availability.
- Commercial playbooks: channel strategies for distributors and formulators, negotiation frameworks for long‑term off‑take and tolling arrangements, and contractual templates to lock in feedstock and margin protections.
- Regulatory impact quantification: modeled scenarios for REACH compliance costs, product stewardship investments and the near‑term market impact of low‑emission directives driving waterborne/low‑VOC system uptake.
- M&A and partnership screening: valuation ranges under multiple scenarios, identification of targeted assets (high‑purity lines, regional hubs), and integration risk checklists.
- Risk matrix and mitigation roadmap: actionable steps to reduce feedstock, logistics and policy risk across procurement, operations and commercial teams.
Competitive landscape — who matters and why
The industry structure is oligopolistic: a small set of producers controls a disproportionate share of supply, creating both systemic resilience and localized scarcity risks. The report profiles the leading players, with focused briefings on strategy, asset footprints and recent strategic moves:
- Mitsubishi Gas Chemical Company, Inc. (Tokyo, Japan) — a global leader in primary MXDA production with a large Niigata facility. Their asset base supplies epoxy curing agents and polyamide resin chains worldwide. Importantly, Mitsubishi announced a multi‑year capacity expansion at Niigata in February 2026 to capture demand from EV and renewable energy applications — a development we treat as a regime signal rather than a one‑off event.
- CAC Group / CAC Nantong Chemical Co., Ltd. (Nantong, Jiangsu, China) — the second‑largest producer with a significant Shanghai‑area base; their strategy emphasizes exports to regional formulators and industrial end‑users in Southeast Asia and Europe, and they are active in markets for epoxy curing and specialty intermediates.
- INGOOCHEM (China) — a specialty supplier focused on high‑purity MXDA grades for electronics and semiconductor customers. Their pilot lines and electronic‑grade product positioning illustrate the value‑chain premium available for purity and traceability in advanced industrial segments.
Market concentration and strategic implications
Top‑player concentration is high (the top three and five suppliers collectively capture the majority of market share). That concentration produces three consequences that any 2026 strategist must internalize:
- Supply bargaining power: incumbents can defend margins through selective off‑take, minimum purchase obligations and by prioritizing long‑term customers in constrained periods.
- Barrier effects: feedstock access, regulatory compliance overhead and certified high‑purity capacities create meaningful entry barriers for greenfield entrants without partnerships or niche differentiation.
- Strategic openings: niches remain where newcomers and specialty operators can capture value (electronic‑grade MXDA, bio‑derived routes, and integrated downstream formulations with proprietary curing systems).
Regulation, feedstock and sustainability — dynamics that shape strategy
Regulatory and raw material dynamics are not background noise — they are primary drivers of investment timing and product strategy. Key points we model:
- REACH and similar product‑stewardship regimes demand registration and risk assessment commitments that raise the cost of market entry in Europe and condition product design globally. As documented in supplier safety data and regulatory notices, MXDA is subject to these compliance regimes and shifting risk thresholds for petro‑derived amines.
- Crude oil and aromatics markets continue to determine m‑xylene feedstock economics. Historical crude‑linked price swings produced feedstock cost variation exceeding 30% in recent stress events; that volatility directly translates into margin compression risk unless mitigated by hedging or contractual terms.
- Sustainability pressure under the EU Green Deal is catalyzing R&D into bio‑based MXDA alternatives. For firms with long planning horizons, allocating a portion of R&D and pilot capital to non‑petro routes is a legitimate strategic hedge and market access enabler for eco‑conscious customers.
Recommended 2026 actions — prioritized and practical
For the coming planning cycle, we recommend a prioritized set of actions, grouped by capability:
- For incumbent producers:
- Run a revised capital allocation stress test: model the Niigata expansion and similar capacity moves against low, base and high demand scenarios to time brownfield expansions and debottlenecks.
- Lock in feedstock via layered contracting (mix of long‑term supply, indexed pricing and options) and consider financial hedges on aromatics exposure.
- Invest selectively in high‑purity lines and traceability systems to capture the premium electronics segment while maintaining volume‑grade throughput.
- For new entrants and investors:
- Pursue asset light models (tolling, JV with captive feedstock) or target specialty niches where purity and formulation integration reduce head‑to‑head competition.
- Use the report’s M&A screening tool to prioritize targets with regulatory dossiers and product stewardship in place — these de‑risk go‑to‑market timelines.
- For downstream formulators and buyers:
- Negotiate multi‑tier supply agreements that combine price floors with volume commitments and flexibility clauses to deal with spot shocks.
- Accelerate qualification of bio‑based and low‑VOC systems now to avoid late‑stage reformulation costs when regulatory windows tighten.
How PW Consulting’s models support board decisions
The report’s scenario engine converts commodity and policy inputs into P&L and cash‑flow outcomes at plant and corporate level. Use cases include:
- Capex decision support — NPV and IRR sensitivity to feedstock price paths and product‑mix premiums;
- Commercial negotiation — supplier ranking and counterparty exposure maps to inform backup suppliers and contract design;
- M&A diligence checklist — rapid red flags tied to regulatory non‑compliance, feedstock concentration and market access limitations;
- ESG strategy alignment — quantified emissions and compliance cost trajectories to prioritize bio‑route pilots versus end‑of‑pipe mitigation spend.
What we intentionally withhold in this preview
To preserve the report’s value as a decision‑grade asset, this preview omits the granular regional and application‑level revenue breakdowns, detailed price decks, and company‑level financial models that underpin our recommendations. The full study contains downloadable models, plant‑level capacity tables, and step‑by‑step playbooks that translate the central scenario into contracts, capex proposals and KPI dashboards. If your team is evaluating MXDA exposure or positioning for 2026, those deliverables convert insight into executable plans.
Next steps — how to use this analysis in 2026 planning
Use this research as the backbone of three 2026 planning activities:
- Board risk review: present the report’s downside and upside scenarios to finance and commercial committees to calibrate contingency budgets and covenant tests.
- Procurement playbook: adopt the layered contracting strategies and hedging templates to reduce cost volatility in the coming 18–24 months.
- Growth and R&D sprint: allocate pilot budgets to high‑purity and bio‑derived initiatives identified in the report’s opportunity map, prioritizing projects with near‑term commercial optionality.
In an environment of concentrated supply, feedstock volatility and accelerating regulatory change, the difference between a good and great 2026 plan is the quality of scenario work and the pragmatism of execution tools. Our full MXDA market study supplies both — detailed analytics, executable playbooks and the negotiation templates you need to move from insight to impact. Access to the complete report and models is available through PW Consulting’s market research portal and advisory desk.
For detailed analysis of this topic, please visit the official page: M-Xylylenediamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


