



PW Consulting: Asia‑Pacific Holds 52.8% of the Urea Market — Outlook to 2032

Urea Market 2026: Navigating a Low-Growth, High-Volatility Landscape — Strategic Insights from PW Consulting
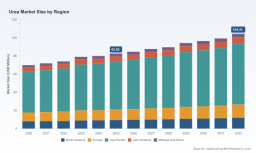
As companies set strategy for 2026, choices made this year will determine competitive positioning across the urea value chain for the rest of the decade. Our new market study — anchored on a 2025 base year and projecting through 2032 — shows a mature global market expanding at a modest compound annual growth rate (CAGR) of 3.1% from 2026 to 2032. The market size recorded in 2025 stands at USD 82.62 Million (revenue unit: Million). Under our base forecast, the market rises to USD 104.41 Million by 2032. These headline metrics frame a story of steady demand underpinned by core agricultural consumption, but punctuated by intermittent supply shocks, input-cost volatility and a fast-accelerating sustainability agenda.
Urea Market
Why this study matters for 2026 decision-makers
-
Timing: 2026 is a pivot year. Feedstock markets that eased in 2025 have shown renewed volatility, regulatory pressure on fertilizers is intensifying, and technology pathways for low-emissions urea are entering early commercialization. Strategic moves made now — investments, sourcing shifts, product repositioning — will capture value or lock in rising cost exposure.
Urea Market -
Precision: The study translates headline growth into actionable scenarios for capex prioritization, product-mix optimization, and commercial hedging. We map the implications of a 3.1% CAGR onto unit economics and cash flow sensitivities across six operational archetypes (co-located ammonia-urea complexes, seafreight exporters, mid-scale inland producers, toll processors, specialty formulators, and controlled-release innovators).
Urea Market -
Risk-to-reward clarity: The report integrates near-term disruptions and medium-term structural shifts to create decision-ready matrices — helping executives balance short-term profitability with long-term strategic resilience.
Market dynamics shaping strategy in 2026
-
Feedstock and cost volatility: Ammonia remains the dominant input and a primary driver of urea cost curves. Recent months have delivered mixed signals — production costs fell meaningfully in some markets late in 2025, yet ammonia prices rebounded into late-2025. At the same time, liquid sulfur moved sharply higher within a year, exerting upward pressure on production costs where sulfur feed is integral to routes or logistics. These movements increase the importance of flexible sourcing, long-term offtakes and hedging frameworks for producers and large buyers.
-
Supply shocks and trade flow sensitivity: The industry continues to exhibit sensitivity to localized energy and infrastructure disruptions. A major exporter experienced a temporary halt to operations in early 2026, underlining the risk of concentrated production footprints. Our modelling shows short interruptions have outsized effects on regional freight and spot pricing — a reminder that geographic and logistical diversification matter even in a modest-growth market.
-
Regulatory and trade headwinds: Trade policy moves in key markets are already reshaping commercial flows. Import barriers and targeted tariffs introduce margin risk for seaborne suppliers and elevate the value of regionalized supply. Simultaneously, regulatory scrutiny around emissions and nutrient runoff is fueling demand for premium and stabilized products, which command a price differential and require different go-to-market capabilities.
-
Product and technology inflection: 2025–2026 saw credible progress on product-level emissions claims and new application formats. Manufacturers and technology suppliers verified emissions reductions from stabilized urea formulations, and several markets scaled nano-urea production for concentrated application formats. Separately, green ammonia-to-urea routes are moving from pilot to early commercial stages with selective off-takers already contracting low-carbon volumes. These trends create a bifurcated market: commodity urea with tight margin management, and premium segments driven by sustainability and agronomic performance.
Competitive landscape — direction without the proprietary detail
The industry is neither atomized nor monopolized. Market concentration is moderate: the largest global players collectively hold a substantial share of seaborne flows and capacity, but national champions and regional producers maintain significant local dominance. This creates room for both scale-driven exporters and agile regional specialists.
-
Large integrated fertilizers and ammonia majors are leveraging scale and feedstock integration to defend margins. Their strategies emphasize reliability of supply, incremental low-carbon product offerings and control over seaborne logistics.
-
Regionally focused companies and traders compete on customer intimacy, service models and tailored product mixes (e.g., enhanced-efficiency fertilizers for specialty cropping systems).
-
Newer entrants and portfolio players are targeting premium niches — controlled-release, stabilized products, nano-formulations — where technical differentiation can translate to higher margins and customer stickiness.
Our full company profiles include detailed financial and operational benchmarking across the peer set, including plant footprints, product portfolios, recent capital projects and strategic priorities. For example, leaders in Europe and North America are advancing low-carbon urea routes and enhanced-efficiency formulations, while Gulf-region producers continue to dominate seaborne export capabilities. Major publicly listed players and state-backed groups all feature in the competitive map, and our scorecards evaluate them on scale, feedstock security, decarbonization readiness, and commercial agility.
What’s included in the PW Consulting urea study (practical toolkit)
-
Integrated forecast model (2026–2032) — top-line market trajectories and scenario variants that stress-test demand and supply under different oil, ammonia and trade assumptions.
-
Cost and margin curve analyses — plant-level cost buckets, feedstock sensitivities, and break-even maps for different operational archetypes.
-
Supply-side inventory — a validated register of major production assets (operational status, technology route, ownership structure), plus a pipeline tracker for announced projects and commissioning windows.
-
Policy & regulatory scenarios — trade-policy shocks, emissions pricing, and nutrient management regimes modelled for commercial impact through 2032.
-
Product segmentation playbooks — go-to-market guidance for commodity, stabilized and specialty urea products, including pricing strategy, channel design, and agronomic validation requirements.
-
Company scorecards and M&A decision framework — tailored diligence checklists, valuation sensitivities and integration blueprints for both bolt-on and transformational deals.
-
Operational resilience & procurement protocols — actionable measures to reduce exposure to feedstock swings and logistical disruptions, including contract templates and shortlists of risk-mitigation partners.
Strategic actions for corporate leaders in 2026
-
Stress-test your portfolio against at least three cost scenarios: commodity-soft, feedstock-shock, and premium-adoption. Use the study’s scenario engine to quantify bottom-line sensitivity and inform capex gating decisions.
-
Prioritize feedstock security: lock in long-term ammonia supply or consider co-investment in upstream capacity where scale economics justify. For trading and merchant businesses, diversify shipping and storage footprints to mitigate short interruptions that can cascade into spot price spikes.
-
Define a clear product stratification strategy. Maintain competitive pricing in the commodity core, while selectively expanding stabilized and enhanced-efficiency offerings where agronomic data and local regulation support a premium.
-
Make decarbonization decisions commercial. Select pilot customers and long-term offtakers for low-carbon urea volumes; structure offtake agreements and price premia based on verified emissions reduction claims.
-
Use M&A selectively. Small, targeted acquisitions can accelerate entry into specialty segments or improve route-to-market in high-value regions. Larger transactions should be justified by feedstock synergies or the ability to capture seaborne supply economics.
-
Embed geopolitics into procurement. Tariff and trade barriers are no longer rare events; model tariff scenarios and quantify the elasticity of your trading routes to rapid policy shifts.
Signal events and near-term monitors
-
Operational continuity at large export hubs — any extended outage can reshape spot spreads and create short-term arbitrage opportunities.
-
Ammonia cost trajectory and sulfur market behavior — these are the principal levers on the cost curve; procurement teams must have live-tracking and hedging playbooks.
-
Regulatory approvals for stabilized and nano-formulations — verification of emissions or agronomic claims materially affects premium potential and market acceptance.
-
New commissioning waves in target markets — domestic production expansion can compress imports and change regional pricing dynamics.
Closing — the value proposition of the full report
Our 2026 urea market study is designed as a decision accelerator. It combines rigorous forecasting with hands-on tools — models, scorecards, procurement playbooks and scenario generators — so executives can move from insight to action within weeks, not months. This article outlines the strategic contours and immediate implications; the full report contains the granular datasets, segmented forecasts, and company-level metrics required for transaction-level or operational planning.
For teams preparing budgets, negotiating offtake agreements, evaluating decarbonization investments, or sizing M&A targets, the difference between a prudent and a transformative decision in 2026 will be the quality of the market intelligence behind it. PW Consulting’s full study gives you that edge.
Access to the full dataset, regional and application splits, plant-level profiles and the interactive forecast model is available on our report landing page — where the detailed numbers and tools required to execute on the strategies above are provided to subscribers and clients.
For detailed analysis of this topic, please visit the official page: Urea Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


