



PW Consulting: Electron Beam Resists Market Poised for 6.5% CAGR Through 2032

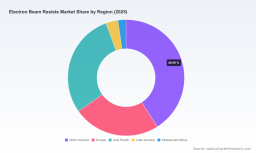
Electron Beam Resists Market: Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new Electron Beam Resists Market study delivers a market-centric, execution-ready intelligence package calibrated to the calendar year 2026. At the macro level, the market has expanded from roughly USD 280 million in 2020 to about USD 355 million in 2025 and is projected to continue its upward trajectory, reaching an estimated USD 544 million by 2032. This trajectory implies mid-single-digit compound annual growth across the forecast horizon (the model uses a 6.5% CAGR for 2026–2032), driven by continued investment in high-resolution patterning for semiconductors, advanced storage media, and emerging nanofabrication processes.
Electron Beam Resists Market
Why this report matters for decisions in 2026
- Make capital-allocation choices with confidence: the report translates forecast ranges into capital- and capacity-planning thresholds for R&D, production scale-up, and contract manufacturing.
- Prioritise product and developer chemistry investments: we show where HSQ-like chemistries and PMMA derivatives are likely to capture incremental value, and where formulation breakthroughs will re-shape adoption curves.
- De-risk supply and procurement: the research quantifies exposure to raw-material cost swings and minimum-order constraints and provides mitigation playbooks for 12–36 month procurement cycles.
- Inform M&A and partner screening: the competitive analysis and vendor scorecards isolate acquisition targets and strategic partnerships most likely to accelerate entry into advanced lithography segments.
What the research delivers — operational, decision-grade content
- Validated historical market sizing (2020–2025) and high‑granularity forecasting (2026–2032) with upside/downside scenarios tied to device demand, research funding, and regulatory shifts.
- Commercial segmentation by technology class, application family, and go-to-market channel (including channel economics and buyer behavior matrices).
- Supply‑chain stress-testing: vendor concentration maps, raw-material sourcing risk scores, lead-time elasticities, and minimum-order sensitivity models.
- Technology deep dives: performance envelopes for HSQ-based, PMMA, and hybrid resist chemistries, including process compatibility and resolution metrics.
- Competitive playbooks: vendor scorecards, pricing matrices, and capability gaps for incumbents and scale-up challengers.
- Regulatory and environmental impact assessment: developer chemistry pathways, waste management constraints, and compliance timing for major jurisdictions.
- Commercial due diligence toolkits: integration checklists, synergy calculators, and two-way earn-out model templates for potential acquisitions.
Market dynamics shaping the 2026 strategic agenda
Several structural and tactical forces will determine winners and losers over the next 24–36 months. First, demand remains anchored in semiconductor patterning and next‑generation data storage — both of which require sustained improvements in resolution, line edge roughness, and process latitude. Parallel growth pockets are emerging in nanoimprint lithography and specialized research markets, creating opportunities for premium pricing on high‑performance formulations.
Electron Beam Resists Market
Second, formulation innovation is accelerating. Recent product introductions demonstrate that commercially viable HSQ alternatives and optimized PMMA derivatives are reaching reproducible sub‑5 nm performance in production‑oriented workflows. These advances compress the timeline for adoption by foundries and advanced research fabs, increasing the premium for resist vendors that can demonstrate process robustness across temperature and storage conditions.
Electron Beam Resists Market
Third, regulatory and sustainability pressures are re-shaping process chemistry choices. A notable example is the industry move toward safer developer chemistries: choline‑based developers, presented publicly in 2025, are positioned as less hazardous and more biodegradable alternatives to traditional alkaline developers. For manufacturers and OEMs, this trend will influence procurement specifications, customer acceptance criteria, and potentially production footprint decisions in jurisdictions with tightening chemical controls.
Finally, raw-material economics matter more than ever. For certain HSQ-style formulations recently commercialized, raw‑material production costs were reported in the upper four‑digit dollar range per liter with minimum order quantities that effectively set a one‑liter commercial unit and limited shelf life to about six months. That profile creates working‑capital and inventory risks for smaller buyers while motivating larger-scale purchasers to pursue volume contracts or backward integration.
Competition and technology briefs — who to watch
- Allresist GmbH (Germany) : A focused developer and manufacturer of multiple e‑beam resist chemistries. Recent milestones include the commercial launch of a new HSQ‑category product in late 2025 that demonstrated repeatable sub‑5 nm line widths across extended sample storage conditions, and public presentation of a choline‑based developer as a safer alternative to legacy alkaline developers. Allresist’s incremental innovations — including compatibility adjustments for conductive resists used on insulating substrates — make it a technology leader in application‑specific formulations.
- EM Resist Ltd (United Kingdom) : Specialist supplier of high‑resolution HSQ negative-tone resists and positive‑tone PMMA variants. The company introduced a higher concentration HSQ formulation in early 2025 and is active in niche nanofabrication research channels, a profile that makes it both a partner for early adopters and a potential acquisition target for larger chemical houses seeking high‑resolution capabilities.
- Kayaku Advanced Materials (United States) : A broad supplier with established PMMA and mr‑EBL series resist lines targeting microelectronics and research markets. Kayaku’s scale and distribution footprint position it well for customers seeking supply security and global logistics, especially as minimum order quantities and shelf life considerations increasingly differentiate suppliers.
Market structure and consolidation outlook
The sector exhibits moderate concentration: the largest three firms account for a meaningful share of market revenue, and the top five increase that concentration materially. That structure creates a dual dynamic. On the one hand, incumbent vendors can leverage scale to absorb raw-material input volatility and to underwrite product development. On the other hand, mid‑tier and specialist suppliers exploit niche process advantages and faster innovation cycles to capture value in high‑margin applications. The competitive landscape therefore supports both bolt‑on M&A for established chemical groups and organic growth plays for agile formulators partnering with foundries and research labs.
Strategic plays for companies making 2026 decisions
- Procurement and supply: lock in multi‑year agreements for critical precursors, evaluate contract manufacturing partnerships to reduce MOQ exposure, and model inventory buffers that reflect six‑month shelf‑life constraints on some HSQ precursors.
- R&D and product positioning: prioritize formulations that balance resolution with process latitude and environmental compliance; accelerate validation trials with a small set of strategic fabs to shorten qualification cycles.
- Go‑to‑market and commercial partnerships: co‑develop application notes and process recipes with leading academic and industrial users to reduce adoption friction and create visible performance references.
- M&A and alliances: target specialist HSQ and developer chemistry teams for bolt‑on acquisitions where IP and process know‑how are the primary assets; for larger players, invest in vertical integration of high‑cost precursors that present supply risk.
- Regulatory and ESG risk mitigation: proactively transition to developer chemistries with lower occupational and environmental hazards, anticipate customer specification shifts, and incorporate compliance timelines into product launch calendars.
How PW Consulting’s deliverables translate into boardroom actions
Our report is structured to transform market insight into executable decisions. Each chapter ties forecast outputs to a specific governance action: capital-expenditure thresholds for manufacturing expansion, vendor selection rules for procurement, deal‑structuring templates for M&A, and a regulatory roadmap that links product design to compliance milestones. The suite includes downloadable financial models (sensitivity-tested), supplier heatmaps, vendor scorecards, and scenario playbooks that allow commercial teams to quantify trade-offs in minutes rather than weeks.
Next steps — where to find the depth
This article highlights the strategic contours and decision levers that matter for 2026. For operational leaders needing the underlying datasets — including regional and application splits, vendor-level revenue and pricing assumptions, technology performance matrices, and full scenario model workbooks — the complete PW Consulting report provides the granular tables, charts, and model files required to translate strategy into execution. Access to the full dataset includes custom briefing sessions and a one‑day workshop option to calibrate the findings to your portfolio or transaction thesis.
In an environment where chemistry choices, raw‑material economics, and regulatory shifts are converging to re‑price differentiation, the right intelligence — timely, specific, and operational — becomes a competitive weapon. PW Consulting’s Electron Beam Resists Market study is designed to be that weapon for 2026 decision-makers.
For detailed analysis of this topic, please visit the official page: Electron Beam Resists Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


