



PW Consulting: PVA Films Market to Grow at a 5.5% CAGR through 2032

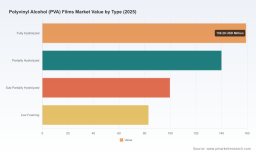
Polyvinyl Alcohol (PVA) Films: Strategic Outlook for 2026 — A PW Consulting Preview
As global manufacturers, brand owners, and investors prepare bids, alliances, and capital allocations for 2026, understanding where the Polyvinyl Alcohol (PVA) films market is heading has moved from helpful to imperative. PW Consulting’s latest market study — anchored on a 2025 base year and a seven-year forecast through 2032 — synthesizes market sizing, technology trajectories, regulatory shocks, and commercial playbooks into an actionable intelligence package. This preview outlines the strategic value of that study for 2026 decision-makers, highlights the major forces shaping the PVA films ecosystem, and signals the commercial moves that will separate winners from followers next year.
Polyvinyl Alcohol (PVA) Films Market
Market Snapshot — What the Numbers Tell Us
PVA films is a mid-sized specialty polymer market with meaningful growth momentum. From a historic base (2020–2025) the market climbed from mid-three-hundreds to just under USD 500 million in 2025 (PW Consulting base year). Our model forecasts the market expanding at a compound annual growth rate of approximately 5.5% for 2026–2032, driven by both volume growth and a premiumization trend toward specialty, certified, and performance-differentiated grades. By 2032 the market is projected to surpass the high hundreds of millions (USD, revenue unit: Million), reflecting sustained adoption in end-markets that prize water-solubility, reduced microplastic risk, and application-specific functionality.
Polyvinyl Alcohol (PVA) Films Market
Two high-level structural facts are especially relevant for 2026 planning. First, the PVA films industry is consolidated: the top three global players control roughly two-thirds of the market, and the top five hold well over four-fifths. Second, price sensitivity remains material: raw-material oscillations and trade-policy shifts can materially compress margins in commoditized grades while providing margin upside for certified, traceable, and specialty variants.
Polyvinyl Alcohol (PVA) Films Market
Key Demand Drivers and Market Dynamics
-
Sustainability legislation and brand commitments: New regulatory efforts — notably nation-level single-use plastic restrictions and regional policies aimed at plastic waste reduction — are accelerating the migration toward water-soluble and biodegradable delivery forms. Consumer-packaged-goods (CPG) brands and chemical formulators are fast-tracking qualification programs for PVA films as a route to compliant and marketable product formats.
-
Performance premiumization: End-users are demanding higher-performance PVA films (optical clarity, controlled dissolution profiles, low foaming, and tailored hydrolysis levels) for sensitive applications such as detergent pods, agrochemical delivery, and specialty industrial uses. This bifurcates the market into value-added specialty streams and lower-margin commodity segments.
-
Input-cost volatility and feedstock tightness: The cost of vinyl acetate monomer (VAM) and related intermediates has been volatile — for example, VAM spot prices spiked materially in 2025 following upstream ethylene and acetic acid rallies, and PVA regional prices saw a notable uptick in early 2026. Such swings affect contract negotiation, pass-through strategies, and the attractiveness of vertical integration or long-term offtake agreements.
-
Trade and tariff environment: Resurgent protectionist measures and tariff restorations in 2025 have introduced greater friction into global supply chains. For companies that rely on cross-border sourcing of resin, films, or machinery, nearshoring and regional capacity expansion are now strategic levers.
-
Technology and certification as differentiators: Certifications (e.g., low-carbon traceability schemes), novel coating or barrier technologies, and controlled hydrolysis chemistries are creating entry barriers and value premiums. Buyers are increasingly willing to pay for supply-chain transparency and certified lower-carbon inputs.
What the Full Report Contains — Practical, Executable Intelligence
-
Top-down and bottom-up market sizing (historical 2020–2025; forecast 2026–2032), with scenario runs for low/mid/high growth.
-
Detailed price-cost modeling that isolates feedstock, energy, and conversion contributions to margin under varying input-price scenarios.
-
Segment and application dashboards (regional demand drivers, grade-level performance requirements). Note: this preview intentionally omits the granular splits that are included in the paid study to preserve the unique commercial value of the full dataset.
-
Supplier matrix and capability assessment (manufacturing footprints, capacity maps, technology specializations, certification status).
-
Regulatory scenario analysis and fast-track compliance playbooks for major jurisdictions.
-
Commercial go-to-market playbooks for brand owners and film manufacturers, including pricing strategies, innovation roadmaps, and channel models.
-
M&A and partnership screening — a prioritized list of targets and strategic rationale for consolidation, verticalization, or capability-acquisition moves.
-
Risk heatmap and mitigation levers: supply disruptions, raw-material shocks, and demand-pull failures, with contingent action plans.
Competitive Landscape — Who’s Shaping the Market
The PVA films sector is populated by several well-capitalized incumbents and a cohort of regional specialists. Leading specialty chemical groups and dedicated PVA film houses are investing in both capacity and capability — expanding lines for optical-use films, water-soluble delivery systems, and certified low-carbon product lines. Recent strategic moves illuminate the trajectory:
-
Large integrated players have announced capacity expansions and product partnerships to capture demand from packaging and construction. These investments aim to lock in scale advantages and secure long-term supply to large converters and brand owners.
-
Manufacturers with sustainability-focused portfolios have pursued certification schemes and regional manufacturing footprints to capture premium demand for traceable, lower-carbon films.
-
Regional champions — particularly in Asia and Europe — continue to compete on tailored product solutions, price, and proximity to downstream converters, while emerging players emphasize customer intimacy and rapid customization.
Our competitive profiles in the report include leadership maps, capability scoring, and likely strategic options for each major player — from capacity redeployment to selective partnerships with CPGs and agrochemical formulators. The full study also tracks recent public moves such as capacity announcements, sustainability certifications, and targeted product launches that will reverberate through 2026 purchasing cycles.
Strategic Implications for 2026 — What Companies Should Do Now
-
Prioritize grade-mix optimization: Reassess product portfolios to tilt toward specialty, certified, and higher-margin grades. A commodity-heavy stance is vulnerable to feedstock volatility; premium grades offer margin insulation and strategic stickiness with customers.
-
Secure input-cost flexibility: Negotiate multi-year supply contracts, consider hedging for key feedstocks, and evaluate backward coordination where economically viable. Even modest reductions in feedstock exposure materially improve margin resilience.
-
Accelerate certification and traceability efforts: Investment in recognized sustainability certifications and verified sourcing can unlock shelf-space and RFP advantages with multinational customers and public-sector tenders.
-
Reconfigure supply chains for agility: Build optionality through regional production nodes or co-manufacturing arrangements to mitigate tariff and logistics shocks. Nearshoring or local partnerships in key demand corridors reduce lead times and political risk exposure.
-
Adopt a differentiated commercial model: Use value-based pricing for specialty products, bundle formulations or application engineering services, and create performance warranties for dissolution profiles where appropriate.
-
Scan for consolidation and capability buys: Given the market’s concentration dynamics, opportunistic M&A can secure capability gaps (e.g., optical films, ISCC-certified production, regional logistics hubs) more cheaply than greenfield builds in 2026.
Risk and Opportunity — Reading the Near-Term Signals
2025–2026 has proven that a single external shock (commodity rally, tariff change, or regulatory pivot) can quickly reshuffle competitive advantage. The key inference for 2026 planning is that optionality and speed of execution are as valuable as long-term strategy. Firms that can rapidly pivot capacity, secure low-cost feedstock basins, and credibly demonstrate sustainability outcomes will capture the disproportionate share of upside as premium demand grows.
Conversely, players that remain product- or regionally-constrained without certification or customer-lock mechanisms risk margin compression and displacement by certified, regionalized competitors.
How PW Consulting Helps You Act in 2026
-
We build tailored scenario models that quantify the P&L impact of feedstock swings, tariff shocks, and demand shifts for your portfolio.
-
We map the competitor moves that matter, translating public announcements into probabilistic forecasts of capacity, pricing, and customer outreach.
-
We deliver prioritized action plans — from procurement hedges to M&A targets and go-to-market scripts — that are designed for rapid execution in 2026 procurement cycles.
Next Steps — Where to Find the Full Intelligence
This preview has outlined the high-level market trajectory, the primary dynamics to watch, and the strategic implications for 2026. For buyers, producers, and investors ready to translate these insights into concrete actions, the full PW Consulting report includes the granular segmentation, scenario-tailored financial models, supplier-level benchmarking, and executable playbooks that are intentionally withheld from this teaser. Access to the complete study will enable you to quantify trade-offs, price propositions, and capacity investments with precision.
In a market where consolidation and certification are creating durable value pools, 2026 is a year for decisive moves. Use robust data and scenario planning to protect margins, accelerate into specialty streams, and build supply-chain options before competitors lock the preferred channels. PW Consulting’s full PVA films study provides the data backbone and strategic templates to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Polyvinyl Alcohol (PVA) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


