



PW Consulting: Digital Refractometers Market to Reach USD 344.8M by 2032 at 6.98% CAGR

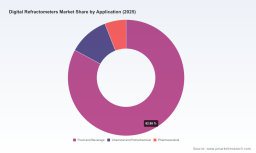
Digital Refractometers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
The global digital refractometers market is at an inflection point. After expanding from a mid‑three‑figure USD base in 2020 to USD 215.0 Million in 2025, the market is projected to grow at a compound annual growth rate (CAGR) of 6.98% across the forecast window, reaching an estimated USD 344.8 Million by 2032. That trajectory reflects steady demand from food & beverage quality control, regulated laboratory workflows, and process automation in pharmaceutical and chemical manufacturing. For corporate leaders planning investments, partnerships, or go‑to‑market pivots in 2026, this study distills the commercial, regulatory and competitive signals that will determine winners and losers.
Digital Refractometers Market
Why this study matters for 2026 strategic choices
We designed the Digital Refractometers Market report to be a decision tool, not an academic exercise. In 2026, management teams will be evaluating resource allocation across R&D, channel expansion, and compliance investments against a backdrop of moderate, but differentiated growth. The market’s steady CAGR masks important structural dynamics — regulatory runway for clinical applications, reimbursement changes in niche healthcare segments, and an industry structure that remains concentrated among a few incumbents — that materially affect M&A valuation, product roadmaps, and commercial cadence.
Digital Refractometers Market
Report scope — practical deliverables for executives
- Proprietary market sizing and forecasting model built on 2020–2025 historicals with scenario outputs through 2032, enabling rapid what‑if analysis for pricing, volume, and share assumptions.
- Technology and product taxonomy that distinguishes handheld, benchtop and inline process architectures and maps them to buyer needs and validation requirements.
- Regulatory and reimbursement playbook that consolidates global device classifications and recent policy shifts affecting clinical and blood‑bank use cases.
- Commercial playbooks with go‑to‑market options (direct, distributor, OEM), pricing levers, and packaging strategies including service, calibration and consumable attachments.
- Competitive heatmaps and vendor scorecards that evaluate technical capability, regulatory clearances, channel reach and innovation velocity.
- M&A and partnership scenarios with valuation sensitivities and integration checklists for roll‑up strategies.
- Operational risk register and supply‑chain mitigation templates to protect launches against component shortages and quality issues.
Each element contains actionable templates — slide‑ready frameworks, vendor shortlists, and validation checklists — designed to accelerate 90‑day and 12‑month plans. Note: this preview purposefully omits granular regional and application splits and detailed revenue shares; those are available in the full report.
Digital Refractometers Market
Key market dynamics shaping 2026 plays
- Regulatory clarity is a growth enabler. Refractometers intended for clinical measurements benefit from a clear regulatory pathway: in the U.S., many clinical refractometer uses fall under Class I 510(k) exempt classifications. That lowers barriers to market entry for validated devices and encourages OEM investment in clinical models.
- Reimbursement shifts create targeted demand pockets. Recent policy changes (for example, legislation authorizing reimbursement for certain total protein tests in licensed blood centers) have created a tangible commercial runway for devices tailored to blood bank and plasma center workflows.
- Data integrity and compliance are must‑have features. Demand for devices and software that support audit trails, electronic signatures and FDA 21 CFR Part 11 compliance is rising among regulated labs and pharmaceutical manufacturers, making integrated connectivity and validated software differentiators.
- Service and recurring revenue are strategic levers. As instruments commoditize, aftermarket calibration, certification, and software subscriptions become decisive margins drivers.
- Concentration and channel dynamics favor scale. With a high market concentration among top vendors, smaller players must seek niche clinical validations, strategic distribution partners, or value‑adding services to differentiate.
Competitive landscape — interpreting market concentration
The market exhibits notable concentration: the top three players account for the large majority of industry revenues, and the top five control an even greater share. This structure creates both barriers and opportunities. Incumbents enjoy scale advantages in manufacturing, compliance and global distribution, but they can be slow to pursue niche clinical or software‑centric innovations that smaller, more agile firms can exploit.
Highlighted players and strategic positioning:
- Atago Co., Ltd. (Tokyo) — Strengths: broad handheld and benchtop portfolio with clinical models and regulatory clearances that facilitate adoption in clinical and veterinary environments. Strategic implications: acquisition targets or OEM partnerships for companies seeking an immediate clinical foothold.
- Anton Paar GmbH (Graz) — Strengths: laboratory‑grade refractometers and pharma‑compliant platforms (validated for regulatory frameworks). Strategic implications: attractive partner for process‑control and high‑precision laboratory applications, particularly where Part 11 and GMP traceability are required.
- Bellingham + Stanley / Xylem Analytics (United Kingdom) — Strengths: product lines with explicit compliance features for regulated labs. Strategic implications: strong channel and systems integration capability for customers prioritizing validated electronic records.
- MISCO Refractometer (Solon, OH) — Strengths: handheld clinical scales aimed at hospitals and veterinary customers. Strategic implications: niche clinical play with established distribution in North American healthcare facilities.
- Reichert Technologies (AMETEK) (Depew, NY) — Strengths: clinical refractometer brands focused on medical and veterinary diagnostics. Strategic implications: solid installed base and service network for aftermarket monetization.
For 2026, decision‑makers should evaluate these vendors not just on device specs, but on their validation libraries, software roadmaps, OEM partnerships and service ecosystems — factors that drive adoption in regulated environments.
Three pragmatic commercial plays for 2026
- Incumbent play — defend and extend: Invest in validated software features (audit trails and Part 11), expand service contracts, and pursue targeted clinical approvals. Prioritize long‑tail revenue from calibration and consumables to offset hardware margin pressure.
- Challenger play — specialize and collaborate: Focus on a narrowly defined clinical or process niche (e.g., blood bank protein testing enabled by recent reimbursement policy). Pursue co‑development with clinical partners to build evidence and seek targeted regulatory clearances rather than broad, costly programs.
- Investor play — roll‑up and integrate: Acquire complementary manufacturers and consolidate distribution to build scale. Supplement hardware with software and service assets to increase recurring revenue multiples and de‑risk cyclical hardware demand.
Risk profile and mitigations
- Regulatory reversals or reclassification — Mitigation: maintain active regulatory monitoring, engage early with notified bodies and regulators, and design modular validation packages that can be repurposed across geographies.
- Reimbursement uncertainty — Mitigation: pursue pilot programs with payors and clinical networks to establish real‑world evidence and accelerate local reimbursement adoption.
- Component shortages and cost inflation — Mitigation: dual‑source critical components, qualify alternative suppliers, and consider near‑shoring for high‑risk subassemblies.
- Price erosion from low‑cost manufacturers — Mitigation: pivot to differentiated features (connectivity, validated software, bundled services) and lock in long‑term service agreements.
How PW Consulting’s analysis translates into 90‑day and 12‑month actions
From our experience advising instrument manufacturers and distributors, the highest ROI actions in year one are pragmatic and low friction: update product validation language and documentation to support regulated buyers; pilot a subscription‑based calibration service in two major markets; and negotiate OEM partnerships that expand clinical channel reach without large capex. Over 12 months, firms should aim to convert at least one pilot into a commercial agreement with a blood bank, clinical laboratory chain, or pharmaceutical process partner to validate demand and justify broader investment.
What we are intentionally withholding in this public preview
To preserve the “trailer” nature of this preview — designed to demonstrate rigor while driving access to the full study — we have summarized macro trends, regulatory pivots and competitive implications but have withheld the detailed quantitative splits by region, by device type and application, company‑level revenue shares, and line‑item pricing models. The full report contains the granular tables, downloadable models and vendor financial benchmarks necessary to execute acquisition diligence, product pricing decisions and market entry plans.
Next steps
For leadership teams preparing budgets and strategic roadmaps in 2026, this study is an essential input: it combines validated market forecasting, regulatory mapping, competitor intelligence and executable commercial playbooks. To obtain the full dataset, vendor scorecards, and scenario models referenced here, access the complete Digital Refractometers Market report and the accompanying Excel decision‑support models through our publication page.
For detailed analysis of this topic, please visit the official page: Digital Refractometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


