



PW Consulting: Piston Connecting Rod Unit Market — USD 5,348.6M in 2025, 2.15% CAGR (2026–2032)

Piston Connecting Rod Unit Market: Strategic Intelligence Brief for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our new market research on the Piston Connecting Rod Unit market. This briefing synthesizes the study’s strategic value for executives preparing 2026 budgets, sourcing strategies, and product roadmaps. It demonstrates the analytical depth and actionable frameworks contained in the full report while deliberately withholding detailed sub‑segment figures and proprietary scorecards to preserve the “trailer” purpose of this article. For the complete dataset, supplier scorecards, and segmented financials, please consult the full report on our website.
Piston Connecting Rod Unit Market
Where the market stands and where it’s headed
The market for piston connecting rod units has shown steady, if modest, expansion over the past half‑decade. After a recovery phase in the early 2020s, the sector settled into a measured growth trajectory. Our base‑year analysis (2025) captures the market at just over the mid‑single‑billion dollar mark, following cyclical movements in vehicle production, industrial demand and aftermarket activity. Looking outward, PW Consulting’s forecast period to 2032 anticipates a compound annual growth rate (CAGR) of approximately 2.15%, reflecting a market that is stable but exposed to structural forces—chiefly powertrain transition, raw material dynamics, and industrial end‑market demand volatility.
Piston Connecting Rod Unit Market
Key implications for 2026 planning:
- Expect a market that is not in a rapid expansion phase but one in which selective investments (capacity, alloys, process automation) can yield outsized ROI if targeted at segments maintaining demand through powertrain transition.
- Near‑term volatility should be managed through flexible sourcing and cost‑to‑serve optimization rather than aggressive capacity builds.
Piston Connecting Rod Unit Market
Market structure and competitive posture
The industry’s competitive geometry is mixed: a cluster of large, diversified suppliers with global OEM ties sits alongside a wide base of regional specialists and performance‑oriented independent producers. The market concentration metrics indicate a moderate level of aggregation—enough scale at the top to influence OEM procurement while leaving ample opportunity for competition and M&A among mid‑tier players. This structure creates distinct strategic options for incumbents and new entrants alike.
Notable supplier archetypes and strategic takeaways:
- Global OEM‑centric manufacturers: Firms with deep integration into complete engine assemblies and long OEM cycles retain pricing discipline and preferred supplier status. Their strategic advantage is scale, multi‑component bundling and multi‑regional footprint.
- Forging and heavy‑duty specialists: Companies focused on forged solutions for light to heavy engines compete on metallurgical competence and throughput economics—an edge when industrial engine demand or heavy commercial vehicle segments are robust.
- Performance and racing niche players: A set of high‑precision suppliers dominates the performance market where material choice (titanium, billet alloys) and engineering customization command premium margins.
- Regional mass‑volume producers and aftermarket suppliers: These players leverage cost structures and distribution networks to serve replacement and low‑cost OEM requirements, often driving higher parts turnover in mature ICE markets.
Competitive snapshot: what leaders are doing
Our review of representative players highlights how different strategies map to distinct risk‑reward profiles:
- Integrated OEM suppliers maintain advantage through bundled contract wins and engineering collaboration on engine platforms—a defensible position but one that requires ongoing CAPEX in process automation and alloy development.
- Forging specialists are investing selectively in advanced forging processes and heat‑treatment controls to push strength‑to‑weight ratios, responding to OEM demands for lighter engines and extended durability under higher specific outputs.
- Performance suppliers are consolidating through strategic partnerships, expanding product lines across forged steel and titanium to capture aftermarket customers who value short lead times and certified performance upgrades.
- Regional volume manufacturers and aftermarket-focused suppliers are optimizing their footprints for just‑in‑time delivery and aftermarket channel penetration—critical as ICE serviceable life becomes a more important revenue stream during the EV transition.
Recent corporate actions captured by our research provide tactical insights. Strategic partnerships and product launches in the high‑performance segment signal consolidation and technology pooling; OEM service instruction updates and targeted aftermarket product releases highlight the importance of staying current with technical specifications and maintenance cycles. These moves underscore the dual importance of innovation and aftermarket service readiness in 2026 strategies.
Raw materials, process trends and regulatory tailwinds
Forged alloy steel remains the primary production material for connecting rods in most automotive and industrial contexts, and steel market dynamics materially affect margins and sourcing decisions. The current steel price environment and structural overcapacity in some producing regions have dampened near‑term price recovery expectations, which informs procurement hedging strategies and long‑lead material contracting. Concurrently, manufacturers are accelerating investments in advanced forging processes, mixed‑alloy strategies, and powder metallurgy to achieve superior strength‑to‑weight ratios—an engineering imperative for hybrid and downsized ICE applications.
Quality and compliance continue to be non‑negotiables: global OEM supply chains demand ISO 9001 processes and tight adherence to dimensional and material standards. For 2026, regulatory and certification readiness should be accounted for in capital allocation and supplier onboarding.
What the full PW report delivers (practical deliverables)
The full PW Consulting report is designed for rapid translation into actionable initiatives. Key operative elements include:
- Top‑down and bottom‑up market sizing and a transparent forecasting model spanning 2026–2032, with scenario branches for accelerated electrification and industrial output shocks.
- Supplier scorecards and capability maps that benchmark manufacturing footprint, metallurgy expertise, aftermarket presence and customer‑segment exposure.
- Cost‑to‑produce models and raw material sensitivity analyses enabling procurement to stress‑test margin scenarios under different steel price indices and alloy mixes.
- Product and technology roadmaps highlighting trajectories for forging, powder metallurgy, and high‑performance alloy adoption.
- Go‑to‑market playbooks for OEM contracting, aftermarket channel growth, and regional expansion—complete with KPIs and implementation timelines.
- M&A and partnership candidate screening: a prioritized list of strategic targets by capability gap and geographic logic (details and target financials are available in the full dossier).
- Supply chain resilience and risk heatmaps, including single‑sourcing exposures, critical spares strategies, and nearshore alternatives.
Decision levers for 2026
From a strategic planning perspective, 2026 is a year to optimize rather than to overextend. Our recommendations for boardrooms and executive teams focus on high‑leverage moves:
- Adopt flexible sourcing with staged CAPEX: prioritize investments in automation and alloy capability that can be scaled to demand without locking in excess fixed cost.
- Hedge raw material exposure via blended contracts and regional sourcing to smooth input cost volatility.
- Prioritize aftermarket and industrial engines as income‑stabilizing streams while rebalancing OEM dependency as electrification accelerates.
- Pursue selective M&A or strategic partnerships to gain metallurgy IP or regional capacity—particularly in markets where logistics or duty regimes favor local production.
- Invest in engineering services and aftermarket programs (e.g., certified rebuild kits, extended life upgrades) to monetize installed ICE fleets during the powertrain transition.
Why PW Consulting’s research matters for 2026
Executives need crisp, practical intelligence in 2026 to allocate scarce capital and prioritize initiatives that preserve margin and optionality. Our study combines market sizing, competitive benchmarking, cost modeling and strategic frameworks tailored to actionable decisions—procurement contracts, CAPEX phasing, product portfolio tradeoffs and M&A screening. By integrating primary supplier interviews, plant‑level process analysis and a scenario‑based forecast, the report allows leaders to:
- Quantify risk exposure under different electrification and industrial demand trajectories;
- Identify the supplier or technology investments that yield the highest near‑term operational leverage;
- Design procurement and manufacturing responses that are resilient to raw material swings and evolving OEM specifications.
Controlled disclosure — what this brief omits
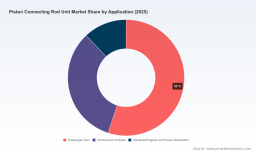
In keeping with the “trailer” principle of this briefing, we intentionally withheld granular segmentation figures and the detailed financials that underpin supplier valuations and target lists. Specific regional and application shares, precise segment revenue breakdowns, and confidential supplier scoring metrics are contained in the full PW report to ensure the integrity of proprietary analyses and to provide maximum utility to subscribing clients.
Next steps
If your 2026 planning cycle involves procurement commitments, technology investment decisions, or M&A posture in the piston connecting rod ecosystem, PW Consulting’s full report supplies the complete dataset and execution templates required to move from insight to action. Our team is ready to provide a tailored briefing session that maps the report findings directly to your P&L and capital plans.
Contact PW Consulting to schedule a confidential walkthrough of the full study and to access the appendices that include our model files, supplier scorecards, and M&A candidate narratives.
For detailed analysis of this topic, please visit the official page: Piston Connecting Rod Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


