



PW Consulting: High Dielectric Plastic Films Market to Hit USD 1,988.79M in 2026 at 6.48% CAGR

High Dielectric Plastic Films Market — Strategic Outlook for 2026 Decision‑Makers
As Senior Strategy Advisor and Chief Industry Analyst at PW Consulting, I present a focused briefing on the High Dielectric Plastic Films market designed to inform boardroom decisions in 2026. This article translates our full market research into the strategic signals executives must understand now — product, supply chain, regulatory and competitive levers that will determine winners over the next planning cycle. Consider this a trailer: we reveal the trends, risk vectors and playbook-level prescriptions while reserving the granular segmentation tables and supplier scorecards for the full report.
High Dielectric Plastic Films Market
Market trajectory and what it means for strategy
The high dielectric films market has moved from a niche specialty into a mainstream materials play with industrial-scale demand. After a steady expansion through the early 2020s, the market reached approximately USD 1,834.8 Million in our base year (2025). Our forecast shows continued growth through 2032, culminating near USD 2,851.2 Million, underpinned by a forecast CAGR of 6.48% for the projection window. This pace reflects a mix of steady electronics replacement cycles, accelerated electrification in transportation and industry, and incremental adoption of specialty polymers in energy storage and power electronics.
High Dielectric Plastic Films Market
For 2026 planning horizons, these numbers translate into three practical imperatives: (1) capacity planning must be precise — demand growth is meaningful but not runaway, (2) product differentiation (permits and certifications, tailored dielectric constants, thermal stability) will command pricing power, and (3) supply chain resilience will materially affect margins because raw material and logistics shocks are likely to persist.
High Dielectric Plastic Films Market
Demand drivers and structural shifts
- Electrification and power electronics: Growth in traction inverters, onboard chargers and industrial motor drives is steadily increasing demand for high-performance dielectric films. These applications value a combination of high breakdown voltage, low loss tangent and thermal stability — attributes that are driving investment in new film grades and coating technologies.
- Energy storage and DC-link capacitors: The proliferation of large-scale energy storage systems and higher-voltage capacitor designs has increased requirements for films that balance dielectric constant with reliability over long duty cycles.
- Materials innovation: R&D into fluoropolymer blends, high‑K additives and multilayer co‑extrusions is accelerating. Suppliers that can provide consistent, scalable grades with documented certification pathways will command a premium.
- Cost dynamics: Fluoropolymer resin pricing rose materially in recent cycles due to monomer supply constraints — we observed a 12% YoY increase influenced by tetrafluoroethylene availability. That cost pressure compresses margins for commodity grades, pushing OEMs and film producers toward higher‑value differentiated solutions.
Regulatory and trade headwinds
- Chemical restrictions: The EU’s tighter controls on PFAS under REACH Annex XVII create compliance obligations and may force reformulation or obtainment of essential‑use derogations for certain dielectric films used in electrical safety applications. That regulatory pathway will be a gating factor for some fluoropolymer products into European supply chains.
- Tariffs and trade policy: Elevated trade measures have shifted effective landed costs in key corridors — exemplified by higher duties on targeted imports. Companies dependent on cross-border sourcing should reassess landed-cost models and consider reshoring or regional production strategies to protect margins.
- Logistics costs and classification risks: Recent guidance has added hazardous-material related surcharges to ocean freight for certain fluoropolymer shipments, increasing transport costs by a non-trivial single-digit percentage in some lanes. These line-item cost increases matter for thin-margin commodity films and can change the relative competitiveness of regional suppliers.
- Product safety and certification: New testing expectations (e.g., UL requirements for high‑permittivity products) add development lead time and cost. Firms that pre‑qualify products to the updated safety standards will shorten OEM qualification cycles and win specification slots.
Competitive landscape — structure and strategic postures
The market is moderately concentrated: the top three suppliers hold a combined share indicative of a market where global incumbents exert material influence, while the top five further extend that control. This structure creates space for both scale-oriented and niche players. Incumbent strategy archetypes we observe are:
- Scale and capacity expansion: Leading materials companies with global footprints are investing to secure wafer‑scale capacity for established grades, particularly for proven products like polyimide and fluoropolymer films. Such investments reduce lead times for high-volume OEMs and cement long-term agreements.
- Technology differentiation: Players focused on specialty fluoropolymers and engineered multilayer films pursue higher margin niches, partnering with power electronics OEMs to co‑develop materials that meet bespoke electrical and thermal specs.
- Vertical integration and service: Some companies are working upstream (resin partnerships) or downstream (captive slitting/lamination and assembly services) to capture margin and control quality in critical value chains.
Representative players in these strategic themes include established multinational firms known for polymer science and industrial films, alongside specialty producers focused on RF and high-voltage applications. Recent tactical moves underscore these postures: product launches targeting EV power modules, capacity expansions for proven high‑dielectric products, and certification upgrades to accelerate market entry into regulated sectors.
Operational content in our full report (high-level)
Our comprehensive study provides operationally actionable deliverables geared to commercial and technical teams:
- Market sizing and trend decomposition with base-year benchmarking and scenario-based forecasts through 2032.
- Technology landscape mapping and a roadmap for dielectric constant, breakdown strength and thermal stability trade‑offs.
- Supply chain risk heatmap covering raw material exposure, logistics classification risks and tariff sensitivities.
- Regulatory matrix and playbook for navigating PFAS/PFOS restrictions, including a pathway for essential‑use derogation strategies.
- Supplier scorecards, CAPEX prioritization tool, and an M&A target shortlist for bolt‑on and capability acquisitions.
- Commercial negotiation templates (pricing clauses, indexation to resin costs, service level agreements) and go‑to‑market playbooks for OEM qualification.
- Financial impact models (price‑cost pass‑through, margin scenarios, payback on capacity expansion) tailored to executive planning cycles.
Strategic recommendations for 2026 decision-makers
- Lock raw material exposure: Negotiate multi-year supply contracts with price‑adjustment collars for fluoropolymer resins; hedge where practical to dampen the impact of monomer shortages on margin.
- Pre‑qualify to new safety standards: Prioritize certifications for high‑permittivity products to reduce OEM time‑to‑market and avoid rework from retroactive compliance demands.
- Regionalize production footprint: Reassess sourcing across tariff- and freight‑sensitive corridors. Small shifts in production location can materially affect landed costs given current duties and transport surcharges.
- Segment up the product portfolio: Separate commodity films from value‑added specialty grades with distinct commercial strategies—pricing, channel, and service levels should be optimized to each cohort.
- Invest selectively in differentiation: Fund development for higher dielectric constant grades and multilayer constructions where customers pay for reliability and certification, rather than competing on price alone.
- Prepare for regulatory friction: Build a compliance liaison role to engage regulators and secure essential‑use derogations where safety arguments are defensible and commercially material.
- Consider strategic consolidation: With moderate concentration at the top, targeted M&A can accelerate access to proprietary grades or regional distribution networks — use our target shortlist and valuation scenarios in the full report.
Why PW Consulting’s study matters to your 2026 plan
Decisions taken in 2026 about facility allocation, product roadmaps and M&A will determine competitive positioning into the early 2030s. Our research combines bottom‑up plant and capacity analysis, supplier interviews, proprietary cost models, and regulatory impact scenarios to produce forecasts that are both defendable and actionable. That combination lets leadership team trade operational certainty for speed — accelerate qualification for high‑value films, delay commodity capacity until pricing normalizes, or move to secure upstream feedstocks.
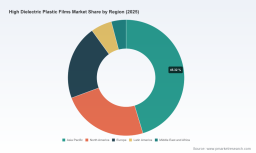
We have deliberately kept the richest datasets — regional and application splits, supplier-level volumes, price curves and the interactive financial models — within the full report to preserve the integrity of our proprietary analyses and to ensure that decision-makers receive calibrated, context-rich intelligence when they request it.
For executives building 2026 budgets, negotiating supplier contracts, or sizing acquisition targets, our study provides the quantitative foundation and the playbooks to act with confidence. To access the full dataset, supplier scorecards and customizable scenario models that underpin the conclusions above, consult the PW Consulting market report page or contact your engagement lead for a tailored briefing.
For detailed analysis of this topic, please visit the official page: High Dielectric Plastic Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


