



PW Consulting: Helicopter Crash-Resistant Seats Market — USD 1,650.45M in 2025, 5.06% CAGR to 2032

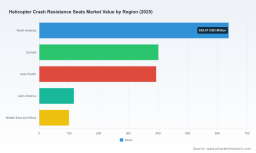
Helicopter Crash Resistance Seats Market — Strategic Preview for 2026 Decision‑Makers
As governments, OEMs and helicopter operators enter a new procurement and modernization cycle in 2026, the helicopter crash resistance seats market is becoming a strategic locus for safety, certification risk mitigation, and aftermarket revenue capture. PW Consulting’s forthcoming market research frames that debate with a data‑driven forecast and practical playbooks tailored for C‑suite, business unit leaders, and procurement heads. This preview summarizes the study’s strategic value and highlights the high‑impact takeaways you need when making 2026 investment and sourcing decisions — while preserving the granular segmentation and proprietary models that sit behind the full report.
Helicopter Crash Resistance Seats Market
Market trajectory at a glance
- Market momentum: The industry has expanded from an estimated USD 1.28 billion in 2020 to roughly USD 1.65 billion in 2025, reflecting modernization programs, fleet renewals, and retrofit demand.
- Near‑term position: PW Consulting’s base year is 2025; our model projects the market to be about USD 1.72 billion in 2026 as the forecast period begins.
- Outlook: Over the 2026–2032 forecast horizon the market grows at a compound annual growth rate (CAGR) of 5.06%, reaching an estimated USD 2.33 billion by 2032 under the central scenario.
Those headline numbers indicate steady, durable growth — not a speculative spike — and they matter differently to different stakeholders: OEMs and Tier‑1 suppliers see product roadmaps and certification calendars; independent retrofitters and MROs view a growing aftermarket opportunity; defense procurement planners see long‑term sustainment budgets and standards compliance obligations.
Helicopter Crash Resistance Seats Market
Why this report matters for 2026 decisions
- Certification is the gating factor. Regulatory requirements and military crashworthiness standards directly drive specification choices and program timing. Expect certification timelines to define winners and losers in 2026 procurement cycles.
- Material and supply risk is strategic. Energy‑absorbing systems rely on constrained inputs (notably aluminum honeycomb cores and advanced composites). Changes in raw material pricing and availability materially affect total cost of ownership and time to field upgrades.
- Aftermarket monetization is maturing. Retrofit kits and Supplemental Type Certificates (STCs) will be the shortest path to near‑term revenue; operators seek low‑disruption upgrades that preserve aircraft availability.
In short: if your 2026 decisions involve seat procurement, retrofit strategy, or capability investment, you must align technical R&D, certification sequencing, and supply agreements — all of which are covered in the full study.
Helicopter Crash Resistance Seats Market
What the PW Consulting report contains (practical deliverables)
- Proprietary demand forecast (2026–2032) by platform, seat type and channel, with sensitivity scenarios and upside/downside cases tied to defense budgets and commercial helicopter activity.
- Certification and regulatory playbook mapping FAA, EASA and MIL standards to product development and timeline risk (including dynamic crash test requirements and downcrash velocities).
- Supply‑chain heat map and cost drivers: vendor tiering, raw material bottlenecks, and a quantified supplier concentration analysis to support sourcing strategies.
- Competitive benchmarking and scorecards for incumbent and challenger suppliers — product capabilities, certification track record, STC portfolio, and route‑to‑market for aftermarket upgrades.
- Commercial models: TCO templates, pricing decks, and service contract archetypes for operators and OEMs to evaluate lease, retrofit and replacement propositions.
- M&A and partnership screening: prioritized targets by capability gap, geographic footprint and aftermarket presence; modelled synergies and integration risk factors.
- Execution playbooks: procurement RFP language, certification engagement timelines, and go‑to‑market tactics for retrofit programs and OEM supply agreements.
The full report converts these deliverables into actionable steps and Excel models you can use directly in negotiation and investment planning sessions. This preview intentionally omits detailed segmentation outputs — the exact regional, platform and seat‑type splits are available in the full report and underpin the forecasts above.
Core market dynamics shaping 2026 choices
- Standards and dynamics: FAA and EASA dynamic crash requirements are non‑negotiable design constraints. For military platforms, MIL‑STD‑1290(AV) sets more aggressive survivability targets that drive heavier, more complex energy‑absorbing systems and influence platform compatibility decisions.
- Materials and weight trade‑offs: Aluminum honeycomb cores remain a dominant energy‑absorption solution but recent supply constraints pushed their industry price higher. Conversely, carbon fiber composites enable around a 25% weight reduction for equivalent impact protection in many new designs, altering lifecycle fuel and payload economics.
- Technology convergence: Two technological pathways are emerging — modular retrofit kits optimized for rapid STC adoption, and integrated seat systems designed into new build platforms. Cellular composite absorbers (cellular foams / engineered lattice materials) are gaining traction in military validation programs for next‑generation attenuation.
- Concentration and aftermarket leverage: Market concentration is meaningful — a relatively small number of suppliers account for a large share of global certified deployments. That concentration drives supply leverage but also creates opportunity for specialized retrofit players to capture niche share.
Competitive landscape — who matters now
Companies with proved certification track records and integrated engineering capability control the architectural choices operators face. Key players profiled in the report include:
- Martin‑Baker Aircraft Co. Ltd. (Denham, UK) — long established in crashworthy seating, with MIL‑STD and FAA certified energy‑absorbing systems for heavy military platforms.
- Safran Seats (Issoudun, France) — a major supplier across civil and defense markets, with certified solutions meeting EASA CS‑27/29 and FAA Part 27/29 dynamic crash requirements.
- IPECO Holdings Ltd. (Droitwich, UK) — specializes in modular, frangible pan and stroke mechanisms for widely used helicopter types; strong in OEM retrofit interfaces.
- DART Aerospace (Mississauga, Canada) — aftermarket and STC specialist with recent certifications for common light‑platform helicopters; a pragmatic partner for operators seeking rapid upgrade paths.
- SKYDEX Technologies Inc. (Englewood, CO, USA) — innovator in cellular composite energy absorbers with validated programs in U.S. military seat evaluations.
- Gentex Corporation (Carbondale, PA, USA) — delivers integrated crew seat systems designed to meet MIL‑STD‑1290 crash standards for rotary‑wing crews.
Recent public developments underscore the split between aftermarket certifiers and material innovators: aftermarket STC activity has accelerated (notable certifications in 2022–2023) while material and energy‑absorbing technology received military validation contracts. These dual trends create distinct strategies — scale and certification breadth for incumbents; niche innovation and speed‑to‑market for agile players.
Strategic implications and recommended actions for 2026
- Procurement: Lock in multi‑year supply agreements for critical raw materials and absorbers; include price‑escalation clauses tied to material indices and clear acceptance gates for certification milestones.
- Product strategy: Prioritize modularity. Design seats and frames to accept energy‑absorbing inserts or cellular composites so you can refresh protection levels without full seat replacement.
- Certification approach: Invest in pre‑certification testing and early engagement with regulators. For retrofit players, pursue STCs for the highest‑volume platforms first to create cashflow and reference installations.
- R&D and sourcing: Allocate R&D to lightweight composite solutions and validate them for dynamic crash events. Simultaneously secure alternative sources for aluminum honeycomb to de‑risk supply chains.
- M&A and partnerships: Consider acquiring or partnering with STC‑savvy retrofitters and materials innovators to accelerate entry into adjacent platform families and aftermarket channels.
- Aftermarket monetization: Sell seats as a service where viable — combine installation, certification management and lifecycle support to capture recurring revenue.
How to use the full PW Consulting study
The full study contains the detailed, account‑level intelligence that supports the headline forecast and strategic recommendations summarized here: platform‑by‑platform demand curves, regional and application splits, supplier revenue profiles, STC and certification timelines, cost models, and a prioritized action matrix for procurement, R&D and M&A leaders. If you are preparing capital budgets, negotiating supplier contracts, or defining a seat product roadmap in 2026, the proprietary models and negotiation templates in the report will materially reduce execution risk and speed decision cycles.
Methodology and credibility
PW Consulting’s forecast is built from a layered methodology: bottom‑up aircraft fleet and retrofitable seat counts, validated by OEM production schedules and defense procurement plans; material and supplier capacity overlays; and scenario stress tests for raw material shocks and regulatory tightening. The study’s base year is 2025 and the forecast period is 2026–2032, with an explicit central case CAGR of 5.06% — conservative enough to test investment theses yet responsive to accelerated retrofit initiatives.
Next steps
For executives preparing to set 2026 budgets or reconsider supplier relationships, PW Consulting can provide tailored briefings that map the report’s models to your fleet mix, procurement cycle and risk tolerance. The summary above highlights where value is created and where execution fails; the full report contains the granular segmentation, price decks and supplier scorecards you need to act.
To access the complete dataset, granular regional and application splits, and the downloadable Excel models that underpin the forecast, contact PW Consulting or visit our report page. The decisions you make in 2026 about certification sequencing, supplier commitments, and retrofit go‑to‑market will determine whether you capture the asymmetric returns the market now offers.
For detailed analysis of this topic, please visit the official page: Helicopter Crash Resistance Seats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


