



PW Consulting: 24-Hour Emergency Roadside Assistance Market to Grow at 5.12% CAGR (2026–2032)

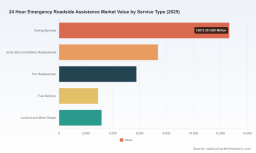
24 Hour Emergency Roadside Assistance Market — Strategic Preview for 2026 Decision-Makers
As executives plan capital deployment, partnerships, and operating models for 2026, the 24 Hour Emergency Roadside Assistance market presents a mix of predictable growth and sudden structural shocks. At a macro level the market moved into the mid‑tens of billions (USD) in the early 2020s and—after steady organic expansion—stood at roughly USD 31.9 billion in our 2025 base year. PW Consulting projects a continued upward trajectory into 2026 and beyond, with a near‑term step increase followed by a compound annual growth rate of about 5.12% across our 2026–2032 forecast horizon. That growth masks a market undergoing technological disruption, regulatory realignment and changing partner economics; this preview explains why those dynamics matter to strategic decision-making in 2026 and how our full study operationalizes the intelligence you need.
24 Hour Emergency Roadside Assistance Market
Why 2026 is a Strategic Inflection Point
Three concurrent trends make 2026 particularly consequential:
24 Hour Emergency Roadside Assistance Market
- Service demand is growing, but cost structures are changing. Volume growth is steady, driven by vehicle parc expansion, rising use of pay‑per‑use and subscription bundles, and greater fleet utilization. At the same time, severity and unit costs are shifting—driven by factors such as more complex vehicle systems, increasing EV presence, and localized infrastructure deterioration—creating margin pressure for providers that fail to adapt their operating models.
- Technology is rewriting the operational playbook. AI dispatch, telematics integration, and digital marketplaces are changing how customers summon help and how providers match resources. White‑label platforms and marketplace players are taking share from legacy models by offering faster response and more transparent pricing to insurers, OEMs and fleets.
- Regulatory and liability vectors are fragmenting risk. New state‑level rules and uneven standards for emergency roadside vehicles and EV incident management are creating localized cost and compliance variation. Some jurisdictions are already introducing storage and handling requirements for damaged EVs that materially affect tow and recovery costs; others lack clear vetting and liability frameworks, exposing buyers and providers to operational risk.
These inflection drivers are not theoretical. They are already manifested in recent market activity: new OEM service alignments, platform rollouts, and consolidations of fleet service teams. For decision‑makers, 2026 is the year to translate strategic intent—whether growth, defense, or divestiture—into executable roadmaps.
24 Hour Emergency Roadside Assistance Market
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
Our full 24 Hour Emergency Roadside Assistance Market study is designed as a decision tool for CEOs, heads of strategy, business development and operations leaders. It goes well beyond high‑level slides to provide the playbooks and analytics teams can use in negotiations, investments and pilots. Highlights include:
- Top‑down market sizing and three forward scenarios (conservative, base, accelerated), calibrated to observed demand shocks and supply constraints.
- Unit economics and pricing frameworks tailored to insurers, OEMs, fleet operators and independents, with sensitivity matrices to stress‑test cost inputs.
- Competitive landscaping with strategic profiles of incumbent and emerging players—coverage models, partner strategies, tech stacks and service propositions—mapped to SWOT and capability heatmaps.
- Operational playbooks: network optimization models, right‑sizing patrol footprints, technician productivity benchmarks and real‑time dispatch KPIs.
- Technology adoption roadmap: telematics integration, AI dispatch, digital payment and claims automation, plus implementation budgets and ROI timelines.
- Regulatory and compliance compendium: jurisdictional risk scoring, contract clauses to mitigate liability, and contingency playbooks for evolving EV handling rules.
- M&A and partnership playbook: valuation multipliers by business model, integration pitfalls, and a prioritized target list for roll‑up or capability acquisition strategies.
- Commercial templates and a 90‑/180‑/360‑day implementation checklist for pilots and scale rollouts.
The report includes data tables, modeling workbooks and scenario drivers that allow clients to replace assumptions with their own inputs. (Note: detailed segment tables and regional splits are available only in the full report.)
Competitive Dynamics — Who Matters and Why
The competitive field combines membership‑based giants, white‑label platform specialists, OEM‑aligned partners and digitally native disruptors. Each archetype faces different strategic tradeoffs:
- Membership clubs and large multinationals leverage scale, brand trust and dense patrol networks. Their challenge is modernizing legacy systems and monetizing beyond membership fees without eroding perceived value.
- White‑label dispatch and platform providers sell orchestration and margins to insurers and OEMs. Their value proposition is speed and integration—partners benefit from cost predictability and digital claims workflows—but these players must continuously invest to keep latency and coverage gaps low.
- OEMs and insurers are moving between outsourcing and insourcing. OEMs increasingly seek to control post‑sale customer experience; insurers balance cost control with customer retention. Strategic choices here shape the mid‑term landscape for service providers.
- Digital disruptors and marketplaces focus on consumer convenience and immediate availability, pushing incumbents to raise service levels while compressing margins in commoditized service lines.
Market concentration metrics indicate a moderately consolidated landscape where top players command material share but meaningful room exists for specialist entrants and regional champions. That structure creates attractive windows for targeted M&A, capability buys (e.g., AI dispatch, EV recovery units), and regional partnerships that can deliver scale economics quickly.
Regulatory and Operational Risks: A Practical Assessment
Regulatory fragmentation is one of the most actionable risks firms must manage in 2026. A few concrete dynamics to factor into planning:
- Local rules that increase recovery and storage costs for damaged EVs change margin math for tows and long‑dwell incidents—procurement teams need contingency pricing and contract language to avoid unexpected fees.
- States without clear vetting requirements for roadside providers create legal exposure for buyers who rely on third‑party crews; insurers and corporate fleets should update vendor due diligence and indemnity clauses accordingly.
- Variability in allowable warning‑light configurations and usage conditions for roadside service vehicles creates compliance complexity for national fleets. Standardize the strictest common denominator in fleet specifications to avoid localized fines or interrupted operations.
- Operational demand shocks, such as sudden spikes in pothole‑related calls, require flexible capacity strategies—short‑term surge contracts, mobile repair units, and predictive maintenance partnerships with municipalities can reduce incidence and cost.
Mitigating these risks is not purely legal work: it requires ops redesign (equipment, training), pricing discipline, and targeted investments in EV‑capable recovery assets and technician certification programs.
Concrete Strategic Options for 2026
Based on our analysis, leaders should prioritize a portfolio of actions that balance near‑term defensiveness with medium‑term capability building:
- Quick wins (0–6 months): update vendor contracts to include explicit EV handling and storage responsibilities; pilot AI dispatch modules to reduce response latency; implement surge capacity clauses for seasonal or infrastructure‑driven demand spikes.
- Capability builds (6–18 months): invest in EV recovery assets and battery‑safe storage bays; integrate telematics feeds for predictive service and automated dispatch; formalize OEM and dealership partnerships to capture post‑sale service flows.
- Strategic expansion (12–36 months): evaluate bolt‑on acquisitions for geographic coverage or tech assets; consider a two‑brand strategy—premium branded patrols and a low‑cost digital fulfillment arm—to protect margin across segments.
How to Use This Report to Drive Board‑Level Decisions
For executives, the value of the PW Consulting study is its ability to translate market signals into executable plans. Use it to:
- Inform capital allocation and operational budgets with scenario‑driven P&L impacts;
- Benchmark performance versus peers on core KPIs—time to arrival, first‑time fix rate, cost per incident—and set realistic stretch targets;
- Prioritize tech pilots and vendor negotiations with clear ROI pathways;
- Design compliance playbooks to mitigate jurisdictional variability and EV‑related exposure;
- Drive M&A or partnership decisions with a modeled view of integration economics and synergies.
Closing: Why Access to Full Data Matters
This preview surfaces the strategic takeaways that should influence boardroom decisions in 2026: sustained market growth, rising complexity from vehicle and regulatory change, and a competitive environment where technology and partnerships determine winners. The full PW Consulting report contains the granular segmentation, regional overlays, provider benchmarking tables and downloadable modeling workbooks that executives need to quantify options, stress‑test plans and execute with confidence. For teams preparing investment memos, procurement renegotiations, or operational redesigns, that level of detail is essential—this preview is designed to guide your immediate priorities and compel the deeper analysis available in the full study.
For detailed analysis of this topic, please visit the official page: 24 Hour Emergency Roadside Assistance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


