



PW Consulting: Beard Shave Formula Market to Hit USD 11,719.4M by 2032 with 4.85% CAGR

Beard Shave Formula Market — Strategic Briefing for 2026 Decisions
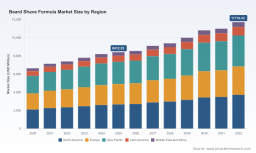
PW Consulting’s Beard Shave Formula Market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames a rapidly maturing category that blends legacy mass‑market players, heritage wet‑shaving artisans, and digitally native beard‑care specialists. At the macro level the market demonstrates stable expansion — growing from roughly USD 6.6 billion in 2020 to about USD 8.4 billion in 2025, and projected to reach approximately USD 11.7 billion by 2032 — reflecting a compound annual growth rate (CAGR) of 4.85% over the forecast window. This briefing distils the strategic implications of those trends for corporate decision‑makers in 2026 while intentionally withholding granular regional and application breakdowns to preserve the full report’s role as a primary source for transaction and product planning.
Beard Shave Formula Market
Why this report matters for 2026 strategic choices
- Capital allocation: Budgeting for R&D, supply‑chain resilience, and targeted distribution experiments (DTC, retail, professional channels) should be informed by the market’s mid‑single‑digit growth profile and the premiumization occurring within the category.
- Portfolio strategy: The combination of scale incumbents and agile niche players means incumbents must decide whether to defend mass channels or selectively invest in premium/natural formulations while challengers must prioritize scalability and margin capture.
- M&A and partnerships: The competitive concentration metrics in the study indicate meaningful room for consolidation and bolt‑on acquisitions to secure capabilities (formulation science, DTC fulfillment, barber channel relationships).
- Regulatory & operational risk: Recent changes in grooming policy across military services and ongoing natural‑oil supply volatility require proactive scenario planning for demand shocks and margin pressure.
Market trajectory and what the numbers tell you
The category’s steady expansion through 2025 underscores resilient end‑user demand for beard‑specific shave preparations and ancillary grooming products. From a strategic viewpoint, two macro takeaways are critical: first, growth is consistent but not explosive — the market rewards targeted differentiation over broad heavy CAPEX bets on volume alone. Second, market concentration is meaningful but not prohibitive: the top three firms account for a material share of the market, while the top five accumulate a clear majority, leaving definable pockets of opportunity for focused entrants and incumbents pursuing adjacent premium or natural segments.
Beard Shave Formula Market
For executives, the implication is clear: incremental share gains remain attainable through product innovation, channel optimization, and brand positioning, but these moves must be calibrated against realistic growth expectations and disciplined margin management. The market’s projected climb to the low double‑digit billions by 2032 means long‑term value creation, but it will be unevenly distributed — the premium and specialty niches are likely to expand faster than commoditized segments.
Beard Shave Formula Market
Segmentation shape without the minutiae
The beard shave formula category is usefully decomposed along product form (gels, creams, foams, oils and soaps), end‑use (individual consumers, professional barber services, hospitality/other institutional uses), and regional dynamics. These axes drive very different product requirements — from performance‑centric formulations designed to soften coarse beards and minimize irritation, to botanically driven premium products prioritizing natural sourcing and skin protection.
Rather than publish detailed regional and application shares here, this briefing emphasizes decision‑relevant distinctions: product form factors dictate R&D and packaging choices; channel mix dictates marketing, pricing, and fulfillment models; and regional regulatory environments influence claims, testing, and labeling requirements. The full report contains the granular segmentation matrices and historical series required for rigorous SKU‑level P&L modeling.
Key dynamics and tail risks shaping 2026 strategy
- Regulatory shifts: Changes issued across U.S. military services in 2025–2026 tighten the scope for long‑term medical shaving waivers and reinforce clean‑shave standards in certain duty contexts. These moves create short‑to‑medium‑term demand variability in institutional channels and emphasize the need for manufacturers to diversify channel exposure.
- Raw‑material volatility: Premium formulations increasingly rely on natural oils (e.g., argan, jojoba). Supply chain volatility for these inputs is ongoing and can materially compress margins for products marketed on natural‑ingredient credentials unless procurement and pricing strategies are adjusted.
- Premiumization & consumer behavior: Elevated willingness to pay for natural, performance, and skin‑sensitive products drives faster growth at the premium end. Consumers are also demonstrating loyalty to brand experiences (barber partnerships, subscription replenishment models) more than to commodity price points.
- Retail & DTC dynamics: Traditional retail still moves high volumes, but subscription DTC and curated bundles are proving to be higher margin growth engines for smaller and digitally native brands, forcing incumbents to reconcile channel conflict with margin uplift opportunities.
Competitive landscape—what incumbents and challengers are doing
The market reflects a classic multi‑channel competitive structure: global CPG giants leverage scale and retail reach; premium heritage brands trade on craft and ritual; and indie DTC players capture premium mindshare with authentic storytelling and ingredient claims. Highlighting a cross‑section of players illustrates strategic variety:
- Procter & Gamble (United States) — Leverages household brands and extensive distribution to defend mass and performance segments. Scale R&D and shelf presence remain core advantages, particularly for broad reach and cost management.
- Unilever (U.K./Netherlands) — Combines mainstream strength with digital playbooks (including subscription models via acquired platforms). Their strategic posture emphasizes multi‑brand ownership to cover both value and premium spaces.
- L'Oréal Group (France) — Focused on technical formulations and skin‑centric claims under specialist men’s grooming lines; strength lies in formulation science and professional channel partnerships.
- The Art of Shaving (United States) — A luxury, ritualized approach to shave preparation and in‑store services; competitive moat exists in experiential retail and premium pre‑shave portfolios.
- Beiersdorf AG (Germany) and Edgewell Personal Care (United States) — Represent well‑positioned incumbents balancing mass skin‑comfort claims with targeted innovations for sensitive or coarse beard care.
- Clarins (France) and other premium cosmetic houses — Prioritize botanical and skin‑health narratives, appealing to consumers seeking premium natural credentials backed by established beauty credibility.
- Independents (e.g., Honest Amish, Beardbrand, Proraso, Cremo) — Capture niche audiences via authenticity, heritage, or performance messaging. These brands are natural acquisition targets for scale players seeking premium or DTC capabilities.
Strategically, incumbents must weigh defensive investments (price, placement, private label competition) against offensive plays (acquisitions of indie brands, targeted premium launches). For challengers, the path to scale runs through differentiated formulations, razor‑thin fulfillment economics for subscriptions, and selective retail partnerships that preserve brand premium.
What the full PW Consulting report delivers (operationally focused)
Our comprehensive report is designed to convert insight into action. Highlights include:
- Market sizing and growth scenarios at global, regional, and channel levels (historical series and 2026–2032 projections).
- Product‑level and channel segmentation frameworks with SKU‑level implication maps for R&D and pricing.
- Supply‑chain and raw‑material risk maps, including stress tests for natural‑oil price increases and mitigation playbooks.
- Competitor dossiers with positioning matrices, route‑to‑market strategies, and acquisition target lists (including valuation heuristics for M&A screening).
- Regulatory heat maps and scenario planning templates addressing grooming policy changes and labeling/compliance risks in key markets.
- Actionable go‑to‑market playbooks for incumbents and challengers — DTC subscription pilots, retail assortment optimization, and barber/pro channels monetization.
- Five prioritized strategic imperatives and a 12‑month execution roadmap tailored for management teams evaluating investments or portfolio pivots in 2026.
The body of the report includes the detailed tables, regional splits, and unit economics that are intentionally not reproduced in this brief to preserve analytical value for subscribers and project partners.
Practical recommendations for 2026 — five priority moves
- Lock in strategic raw‑material arrangements: Negotiate multi‑year supply contracts or joint‑ventures for volatile natural oils; consider formula reformulation buffers where feasible to protect margins.
- Segmented product architecture: Build distinct SKUs for performance, skin‑sensitive, and botanical premium buyers — but centralize R&D to reduce duplication and accelerate claim validation.
- Channel‑tailored go‑to‑market: Pilot premium DTC subscription bundles while maintaining defensive retail shelf presence; establish barber partnerships as both revenue and R&D labs for product validation.
- Regulatory & institutional scenario planning: Quantify exposure to military and institutional channels and diversify to consumer channels in regions where grooming policies tighten.
- M&A & partnership focus: Use tuck‑ins to acquire DTC capabilities, artisanal formulations, or sustainable sourcing expertise — prioritize deals that accelerate margin recovery and brand credibility.
Closing — why access the full report
This briefing surfaces the strategic crossroads facing players in the beard shave formula market as they plan for 2026. The category offers predictable aggregate growth and compelling pockets of premium expansion, but value will accrue to organizations that combine supply‑chain foresight, disciplined product architecture, and channel agility. PW Consulting’s full report supplies the granular regional splits, product‑form revenue tables, scenario models, and competitive benchmarks necessary to convert the insights above into executable plans and rigorous investment theses.
For boards and leadership teams preparing 2026 budgets, product roadmaps, or M&A screens, the full dataset and playbooks are essential. Contact PW Consulting to obtain the complete report, download the interactive models, and schedule a strategy session tailored to your firm’s exposure in this evolving category.
For detailed analysis of this topic, please visit the official page: Beard Shave Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


