



PW Consulting: Cookie Dough Market to reach USD 21,289.33M by 2032 at 5.28% CAGR

Cookie Dough Market 2026: Strategic Imperatives for Decision‑Makers
Executive trailer — why this research matters for decisions in 2026
By the end of 2025 the global cookie dough market had consolidated into a mature, yet innovation-rich category. Our PW Consulting baseline shows market value expanding from USD 11,215.4 million in 2020 to USD 14,850.5 million in 2025, and—under our central scenario—continuing to grow to roughly USD 21,289.3 million by 2032 at a compound annual growth rate of 5.28% across the 2026–2032 forecast window. Those headline numbers matter because they mask two simultaneous dynamics that will determine winners and losers in 2026: (1) persistent consumer demand for convenience and indulgence, and (2) accelerating regulatory and food‑safety pressure that raises the bar on manufacturing, labeling and packaging.
Cookie Dough Market
What PW Consulting’s Cookie Dough Market Report delivers
-
Actionable market sizing and a transparent, editable financial model (USD, millions) with scenario toggles for price, volume and margin sensitivity across 2026–2032.
Cookie Dough Market -
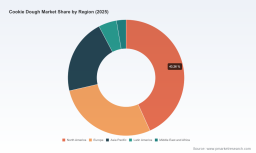
Granular segmentation analysis by product type, channel and geography (note: this introduction intentionally omits segment allocations—detailed splits are in the full report).
Cookie Dough Market -
Competitive landscaping with strategic profiles of incumbent manufacturers, private label operators and emergent edible‑dough brands, including capability maps and share estimates.
-
Operational playbooks for food safety, plant conversion to heat‑treatment/pasteurization, and low‑cost automation options for portioning and frozen storage.
-
Packaging and regulatory readiness checklists tied to the latest U.S. and state‑level rules (e.g., proposed front‑of‑pack nutrition disclosure and California recyclability claims), plus a compliance timing roadmap.
-
Trade, pricing and margin benchmarks (consumer price tiers, retail assortment strategies, and private‑label economics) and a near‑term M&A playbook for consolidation and capacity acquisition.
-
Risk matrices covering product recalls, allergen control, and supply shocks to dairy and specialized ingredients—paired with mitigation pathways and insurance/recall-cost modelling.
Five strategic imperatives for 2026
-
Make food safety a growth enabler, not just compliance: Recent voluntary recalls focused attention on raw‑consumption formats. Investments in validated heat‑treatment, in‑line pathogen testing and supplier traceability reduce downtime risk and are now table stakes for access to large retail and foodservice contracts.
-
Design packaging for regulatory certainty and retail economics: Proposed federal front‑of‑pack nutrition rules and state recyclability mandates require programmatic action. Firms that pre‑emptively reengineer packs to meet upcoming labeling and recyclability standards will avoid rework costs and preserve shelf access.
-
Balance premiumization with affordability: Consumers continue to trade up to gourmet, clean‑label and free‑from variants while remaining price conscious. Tactical SKU rationalization—fewer hit SKUs in premium tiers, wider private label and value formats—drives margin optimization without surrendering innovation leadership.
-
Optimize channel mix with manufacturing flexibility: Winning foodservice contracts requires different SKUs, pack sizes and cold‑chain reliability than retail grocery. Flexible lines capable of switching between frozen, refrigerated and shelf‑stable outputs increase addressable demand and protect utilization.
-
Pursue selective consolidation and capacity partnerships: The category displays moderate concentration at the top, creating windows for bolt‑on acquisitions and co‑manufacturing agreements that accelerate national distribution while limiting capital expenditure.
Competitive landscape — what leading players are doing and why it matters
The category is populated by large CPG multi‑category manufacturers, specialist B2B suppliers, agile direct‑to‑consumer edible‑dough brands and contract bakers. Market concentration metrics suggest a moderately consolidated top tier, but the mid‑market is highly dynamic. Below are strategic takeaways for core company archetypes.
-
Large CPG incumbents (e.g., major branded manufacturers): These players leverage scale in refrigerated and frozen distribution, large promotional budgets, and established retailer relationships. Recent product innovation from major brands underscores a playbook focused on flavor extensions, food‑safety upgrades (heat‑treated flour, pasteurized ingredient systems) and seasonal marketing to recapture impulse sales. Their primary risks are margin erosion from promotional intensity and capital requirements to retrofit plants for new safety standards.
-
Global food groups (household names in retail baking): Multinational operators are using brand equity to accelerate ready‑to‑bake and edible formats in developed and emerging markets. Their global sourcing advantage helps absorb commodity volatility, but they must invest in localized packaging and regulatory compliance to avoid trade friction and recall liabilities.
-
Specialist B2B suppliers and contract manufacturers: Companies focused on ice‑cream inclusions, in‑store bakeries and foodservice (bulk frozen formats) are critical capacity partners. Their ability to deliver consistent bulk formats, custom portioning and private‑label services makes them attractive M&A targets for retailers seeking private‑label scale.
-
Direct‑to‑consumer and clean‑label challengers: Smaller brands emphasizing safe‑to‑eat, allergen‑managed, gluten‑free and vegan formulations are accelerating adoption among younger consumers. They often command premium pricing and attractive margins but face scaling challenges on cold‑chain distribution and retail shelf penetration.
-
Contract/third‑party manufacturers and co‑packers: These firms provide rapid scale-up for seasonal spikes and test SKUs without capital commitment. Their strategic value increases as retailers demand faster time‑to‑shelf for limited editions and regional flavors.
Recent market signals with immediate implications
-
Product innovation keeps demand elastic: Holiday and limited‑edition launches drive short, high‑velocity sales windows that also create routine SKU churn. Brands that manage production runway and promotional cadence capture disproportionate shelf share without long‑term permanent SKU proliferation.
-
Recalls underline operational risk: High‑profile recalls in late 2025/early 2026 demonstrate that contamination and undeclared allergen events can rapidly escalate to national notices. Beyond the direct costs, recalls erode consumer trust and can shift category mix toward brands with demonstrable safety investments.
-
Retail pricing tiers are expanding: Premium tubs and niche diet variants command materially higher retail price points than everyday SKUs, creating margin pools for brands that can validate clean‑label or specialty claims. However, these claims bring heightened scrutiny from regulators and sustainability advocates.
-
Packaging and labeling regulation is shifting fast: Proposed federal front‑of‑pack nutrition mandates and state recyclability rules have concrete compliance timelines. Firms that treat compliance as a supply‑chain project—not a marketing tweak—will minimize out‑of‑market risk and rework costs.
How executives should use this research in 90/180/365 day plans
-
90 days: Run an immediate safety and labeling gap analysis against proposed regulatory timelines; prioritize SKUs for mitigation and rapid conversion to approved packaging and process controls.
-
180 days: Execute a supplier resilience plan (second‑source critical fats, chocolate, and specialty flours), and pilot line conversions for heat‑treated or pasteurized processes. Begin targeted conversations with co‑packers to hedge seasonal capacity risk.
-
365 days: Formalize channel strategies—expand private label partnerships where margins justify capacity investments, and roll out premium/clean‑label SKUs backed by traceable ingredient claims and validated safety protocols. Where appropriate, evaluate M&A targets that buy you faster distribution or specialized capabilities.
What we intentionally omit here — and why you need the full report
This introduction showcases the analytical depth, methodology and strategic takeaways of our Cookie Dough Market research while intentionally withholding the granular segmentation shares, region-by-region growth paths, SKU‑level forecasts, and the detailed competitive share matrix that power executive decisions. Those detailed datasets—along with the downloadable financial model, supplier scorecards, and plant‑conversion cost curves—are included in the full PW Consulting report and are designed to be operationalized by product, operations and strategy teams.
Next step — pragmatic access
If you are leading a commercial, operations or M&A agenda in 2026, use this research to transform market growth into repeatable advantage: prioritize safety and compliance, rationalize your SKU portfolio for margin and speed, and pursue partnerships or acquisitions that fill capability gaps. For immediate access to the full dataset, scenario model and company‑level intelligence, download the complete PW Consulting Cookie Dough Market report. Our analysts stand ready to deliver a tailored briefing and a one‑week diagnostic to convert headline trends into your operational roadmap.
For detailed analysis of this topic, please visit the official page: Cookie Dough Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


