



PW Consulting: Breast Cancer Biomarkers Market to Hit USD 8,332.4M by 2032 (9.2% CAGR)

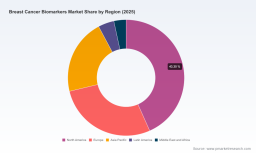
Breast Cancer Biomarkers Market — A PW Consulting Strategic Preview for 2026 Decision-Makers
As life sciences organizations, diagnostics manufacturers, investors, and hospital systems plan for the 2026 fiscal cycle, the breast cancer biomarkers market is an inflection point demanding disciplined strategic choices. Our latest market study (base year 2025, historical analysis 2020–2025, forecast 2026–2032) shows a market that has expanded from roughly USD 2.98 billion in 2020 to USD 4.5 billion in 2025 and is projected to approach USD 8.33 billion by 2032 — a compounded annual growth rate (CAGR) of 9.2% across the forecast window. These headline numbers capture rising clinical demand, growing precision-therapy linkages, and accelerating adoption of molecular and liquid-biopsy technologies; but the next layer of strategic value lies in granular decision frameworks and executable plays that we reserve for subscribers and advisory clients.
Breast Cancer Biomarkers Market
Why 2026 Is a Pivotal Year
-
Regulatory convergence and companion-diagnostic co-development have shifted clinical risk from later commercialization stages to the R&D lifecycle. FDA guidance and recent approvals make 2026 the year companies must align analytical validation plans with market access scenarios.
Breast Cancer Biomarkers Market -
Reimbursement contours are tightening around evidence of clinical utility. Coverage decisions — particularly under molecular diagnostic pathways — will determine which assays scale in clinical labs versus remain niche research tools.
Breast Cancer Biomarkers Market -
Technology bifurcation (standardized IHC/FISH vs. high-value genomic signatures and ctDNA platforms) is creating divergent commercialization models. Choosing where to invest for scale versus differentiation will materially affect return profiles in the 2026–2028 horizon.
What This Research Delivers — Practical, Decision-Ready Intelligence
Our report is engineered for executives and deal teams who need more than descriptive analysis. It combines rigorous market sizing with pragmatic execution tools designed to shorten time-to-decision in 2026:
-
Market-sizing and methodology: a transparent, auditable model covering historical performance and scenario-based forecasts through 2032 (base year 2025).
-
Competitive intelligence and positioning maps: deep profiles of incumbent and emerging players, capability heatmaps across assay modalities, and commercialization footprints.
-
Regulatory and reimbursement playbooks: step-by-step evidence strategies aligned to FDA co-development expectations and payer dossier requirements under contemporary molecular diagnostics programs.
-
Commercial roll-out frameworks: tiered go-to-market templates for reference labs, hospital networks, and direct-to-clinic models, including sales-force sizing, pricing sensitivity bands, and channel economics.
-
M&A and partnership scripts: investment screens, valuation heuristics, and integration checklists for acquiring assay portfolios, platform technologies, or lab networks.
-
Operational risk register and mitigation plans: supply-chain stress tests, critical reagent contingency playbooks, and manufacturing scale-up timelines that align to clinical adoption curves.
-
Data annexes and interactive tools: downloadable financial models and dashboards to run customized scenarios (volume, price, reimbursement, and adoption).
Competitive Landscape — Who Moves the Needle
The market shows moderate concentration: the top three players account for approximately 45% of market revenue, and the top five capture about 62%. This structure leaves room for platform specialists and innovative entrants to displace legacy share where they deliver superior clinical utility or lower total cost of care.
Key incumbent strengths and trajectories we analyzed:
-
Large diagnostics conglomerates retain advantages in reagent supply chains, IVD platform scale, and established relationships with hospital pathology departments. They continue to iterate on IHC/FISH assays to improve quantitation and workflow integration.
-
Genomic and expression-profile specialists are expanding into risk-stratification and therapy-selection spaces, leveraging long-term clinical datasets to defend premium pricing and payer coverage.
-
Liquid biopsy and ctDNA providers have moved from proof-of-concept to clinical utility demonstrations in metastatic settings, and their ability to integrate into trial designs and companion-diagnostic programs positions them for accelerated uptake.
Recent market-moving events highlight these dynamics: regulatory approvals for expanded indications and companion diagnostics in 2024–2025 accelerated adoption and reshaped clinical pathways; clinical-trial readouts showing progression-free survival benefits from ctDNA-guided strategies are opening new use cases for non-invasive monitoring; partnerships to integrate genomic profiles into AI-driven platforms are amplifying the value of existing signature tests. These are the tactical moves that will alter competitive economics in 2026, and our report assesses their strategic implications across multiple scenarios.
Regulatory, Reimbursement and Supply Dynamics — Risks and Opportunities
-
Regulation: The trend toward co-development of therapeutics and companion diagnostics means analyte validation and clinical validation plans must be synchronized with drug development timelines. Delay in either track can jeopardize label linkage and market access.
-
Reimbursement: National and regional coverage frameworks increasingly demand demonstration of clinical utility beyond analytical performance. Early alignment with payer evidence requirements shortens time-to-revenue.
-
Supply-chain fragility: Recent disruptions in antibodies and FISH probe availability have impacted testing volumes. Companies that secure multi-sourced reagents, or that vertically integrate critical inputs, will reduce revenue volatility.
-
Intellectual property: Past patent expirations expanded testing access for hereditary risk markers, enabling lower-cost entrants; however, proprietary algorithmic signatures and platform integrations remain defensible assets.
-
Labeling and RUO constraints: Many high-throughput and NGS assays remain classified as Research Use Only and are not reimbursable for clinical decision-making until cleared; conversion pathways require targeted clinical studies.
Strategic Roadmap for Executives — Six Immediate Plays for 2026
-
Reassess portfolio through a triage lens: prioritize assets that align with companion-diagnostic pathways, have robust clinical utility evidence, or can be differentiated by faster time-to-result (critical for treatment decisions).
-
Accelerate co-development agreements: structure early-stage pharma/biotech partnerships with shared milestones and data governance clauses that protect assay validation timelines and commercial exclusivity windows.
-
Lock down reagent and consumable supply: execute dual-sourcing contracts, strategic inventory buffers, or manufacturing partnerships for antibodies and probe materials to avoid lab downtime.
-
Build payer evidence plans concurrently with clinical pipelines: invest in pragmatic studies and real-world evidence that map assay outputs to treatment decisions and downstream outcomes.
-
Prioritize go-to-market segmentation by clinical utility, not technology: for some assays, channeling through centralized reference labs optimizes cost and quality; for others, point-of-care or near-patient models unlock adoption.
-
Define M&A guardrails: target companies with defensible clinical datasets, validated workflows, or embedded customer relationships — and run integration stress tests against reimbursement scenarios common in 2026.
How PW Consulting Supports Execution
Beyond market numbers, our advisory work translates insights into operational plans. For clients pursuing transactions, we provide diligence templates focused on clinical evidence, regulatory pathway risk, revenue run-rate validation, and synergies. For commercial teams, we deliver launch plans calibrated to payer negotiation timelines, lab conversion rates, and sales-force deployment models. For R&D organizations, we map validation sequences that satisfy both regulatory reviewers and reimbursement bodies while maintaining internal ROI discipline.
The full report contains the detailed segment and regional analyses, down-to-the-dollar channel economics, company benchmarking matrices, and downloadable financial models that enable you to stress-test strategic options under alternate regulatory and reimbursement futures. Those core segment-level and regional breakouts — the numbers that materially change investment and go-to-market prioritization — are intentionally reserved for subscribers and advisory clients as part of our “trailer” approach: we show competence and direction here, and we preserve the granular, proprietary detail behind the paywall to protect actionable intelligence.
If your 2026 strategy depends on getting ahead of regulatory pivots, securing crucial reimbursement evidence, or evaluating acquisition targets in the breast cancer biomarkers space, this study is designed to be the operational backbone of that decision. Contact PW Consulting for a briefing or to access the full dataset, modeling workbooks, and executive workshop options that translate this intelligence into executable plans.
For detailed analysis of this topic, please visit the official page: Breast Cancer Biomarkers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


