



PW Consulting: HER2-Positive Breast Cancer Market to Hit USD 37,045M by 2032; 9.05% CAGR

HER2-Positive Breast Cancer Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a high-consequence synthesis of our HER2-positive breast cancer market study designed to inform boardroom decisions in 2026. This briefing distills the macro trajectory, competitive vectors, and practical use cases of our full report — while intentionally withholding granular subsegment tables to prompt direct access to the full dataset and financial models.
HER2-Positive Breast Cancer Market
Why this market matters in 2026
- The HER2-positive breast cancer market has moved from a specialist oncology niche into a high-value, strategically contested therapeutic category. Our model, anchored on a 2025 base year, shows the global market at roughly USD 20.2 billion (2025 base), growing at a compound annual rate of approximately 9.05% through our forecast window. Under the central case, the market more than doubles by the terminal forecast year, reflecting expanding indications, higher-cost modalities, and broader geographic uptake.
- That profile creates a convergence of investment imperatives: late-stage clinical strategy, ADC and small-molecule manufacturing scale-up, biosimilar cost competition, and payer negotiations around high-cost therapies. For executives making 2026 resource allocation choices, that convergence demands a refined, time-sensitive playbook — which this study supplies.
What the full study delivers (practical, board-ready outputs)
- Top-line forecast with scenario modeling: base, accelerated adoption, and disruption scenarios with drivers and inflection points mapped to regulatory, clinical, and reimbursement milestones.
- Dynamic competitive landscaping: position maps, capability heatmaps, M&A likelihood scoring, and three-year tactical playbooks for originators, ADC developers, and biosimilar entrants.
- Commercial and pricing playbooks: reimbursement barrier matrices by payer archetype, contracting levers (indication-based pricing, outcomes agreements), and pricing sensitivity analyses tied to patient access and volume assumptions.
- Manufacturing and supply-chain risk register: capacity needs for ADCs vs. mAbs, critical supplier dependencies, and mitigation strategies for shortages and quality disruptions.
- Clinical pipeline and regulatory tracker: readouts, likely label expansions, and regulatory tailwinds/constraints that will alter adoption curves in near-term windows.
- Financial models and investment impact analysis: NPV scenarios, partnership valuation frameworks, and exit scenarios tailored to buy-side and corporate development audiences.
Macro drivers and critical dynamics shaping 2026 choices
- Product evolution and indication expansion: The category continues to shift from monoclonal antibodies toward higher-margin modalities — notably antibody-drug conjugates (ADCs) and novel combination regimens. Recent regulatory expansions into earlier-stage, high-risk indications have accelerated addressable patient populations and reimbursement conversations.
- Biosimilars as an accelerant and a disruptor: Patent expirations on originator trastuzumab unleashed biosimilar competition that rapidly captured meaningful share in many markets. That dynamic compresses price benchmarks, changes hospital procurement behaviors, and enables payers to reallocate funding toward premium-priced ADCs and TKIs — but also exerts downward pressure on overall category ASPs.
- Manufacturing complexity and pricing tailwinds for ADCs: ADC manufacturing complexity supports sustained list pricing for leading ADCs. At the same time, supply-chain and capacity constraints for both originators and biosimilars create temporary arbitrage opportunities for agile players with secure supply.
- Regulatory and payer interplay: Regulatory approvals for label expansions can be highly value-accretive, but payer uptake varies by jurisdiction and contract sophistication. Interchangeability rules and local guidance continue to affect biosimilar uptake and prescriber behavior, with some regions requiring prescriber documentation for switches.
Competitive landscape — who matters and what to expect
The HER2 market is concentrated: the top three firms capture roughly three quarters of the market by revenue, and the top five approach mid-80s concentration. That structure creates tactical opportunities for both incumbents and challengers:
HER2-Positive Breast Cancer Market
- Roche / Genentech: The incumbent ecosystem remains dominant via long-established mAb franchises, subcutaneous formulations for administration efficiency, and product breadth across early and metastatic settings. Their strategic playbook will center on lifecycle management, defensive label extensions, and maintaining hospital channel relationships.
- AstraZeneca / Daiichi Sankyo: Their ADC has proven to be a category-defining asset. Label expansions into earlier-stage disease materially increase addressable volume and strengthen their bargaining position with payers despite high per-cycle pricing driven by manufacturing complexity.
- Pfizer (Seagen assets): Small-molecule TKIs, especially in combination regimens, are carving differentiated niches in resistant and metastatic settings. Positive trial readouts can rapidly re-shape combination standards of care.
- Biosimilar players (Amgen, Biocon Biologics/Viatris, Celltrion, Samsung Bioepis): These firms are strategically focused on volume, tender wins, and hospital formulary penetration. Their presence compresses originator ASPs and forces creative contracting across channels.
From a strategic vantage point, incumbents are balancing margin defense with selective investment in high-growth modalities (ADCs, TKIs, combination regimens). Emerging and biosimilar players are prioritizing scale, supply reliability, and price competitiveness to win formularies and tenders.
HER2-Positive Breast Cancer Market
Recent events that materially change the 2026 playing field
- Regulatory expansions for ADCs into earlier-stage disease: These approvals increase short-term addressable populations and accelerate revenue realization for ADC sponsors; they also raise the stakes for payers and employers negotiating access terms.
- Positive combination-trial readouts: Successful trials for TKIs in combination regimens create new cross-product dependencies and open partnership or bundle-play opportunities.
- Biosimilar commercial traction: The post-patent environment has already shifted procurement behavior in several major markets, with biosimilars capturing substantive share and forcing clinical and financial countermeasures by originators.
- Supply disruptions and capacity signaling: Shortages and manufacturing constraints have surfaced repeatedly, underscoring the commercial value of resilient supply strategies and third-party manufacturing partnerships.
Strategic implications and recommended actions for 2026
- For originator manufacturers: Prioritize lifecycle strategies for flagship mAbs while accelerating investment in ADC manufacturing and clinical programs that justify premium pricing. Negotiate multi-year supply agreements with key hospital systems to protect market access against tender volatility.
- For biosimilar entrants and generics players: Focus on scale and service (consistent supply, cold-chain integrity) to win long-term tenders. Consider targeted value-added services (e.g., nurse-administered programs for subcutaneous formulations) to differentiate beyond price.
- For investors and BD teams: Use our report’s scenario outputs to time licensing and M&A — assets that de-risk ADC manufacturing or secure clinical differentiation command premium valuations in high-adoption scenarios. Early-stage partnerships in combination trials may yield asymmetric upside if readouts validate novel regimens.
- For payers and health systems: Develop formulary strategies that recognize differentiated clinical value across modalities and leverage outcomes-based contracts for high-cost ADCs while pressing biosimilar volumes to rebalance budgets.
What the report intentionally withholds here (and why you need the full study)
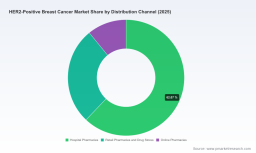
To preserve strategic value for subscribers, this overview omits the granular regional and therapy-type breakdowns, the raw numerical slices behind channel and regional segmentation, and downloadable financial model spreadsheets. Those elements are included in the full report and PowerPoint deliverables, which provide:
- Detailed regional and channel forecasts by revenue and units, with sensitivity analyses;
- Therapy-type comparatives showing margin differentials and time-to-reimbursement expectations;
- Deal-by-deal valuation templates and executable negotiation playbooks;
- Full downloadable models that update with user assumptions for price, uptake, and payer mix.
Final perspective — timing and the window for action
2026 is a hinge year. Macro growth — reflected in a mid-single-digit to low-double-digit CAGR through the forecast window — is translating into real, monetizable opportunities now: ADCs pushing into earlier disease, TKIs reshaping metastatic care, and biosimilars compressing ASPs while expanding patient access. Firms that align clinical development, manufacturing scale, and payer engagement in the next 12–18 months will either lock leadership positions or, at minimum, secure defensible niches.
PW Consulting’s full HER2-Positive Breast Cancer Market study supplies the tactical roadmaps, quantitative models, and decision-ready outputs to operationalize those choices. For executives preparing budgets, deal teams evaluating assets, or commercial leaders revising go-to-market plans for 2026, the full report is the difference between informed agility and reactive scramble.
Next steps
- Download the full report to unlock the regional and therapy-level forecasts, scenario models, and transaction playbooks.
- Schedule a strategy workshop with our consulting team to translate the model outputs into a 12-month execution plan tailored to your asset and market footprint.
Contact PW Consulting for access to the complete dataset, bespoke modelling, and a prioritized 2026 action agenda.
For detailed analysis of this topic, please visit the official page: HER2-Positive Breast Cancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


