



PW Consulting: Uterotonic Agent Market Poised for 6.19% CAGR to 2032

Uterotonic Agent Market: Strategic Brief for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a high-conviction synthesis of our Uterotonic Agent Market study — designed to inform strategic choices in 2026 for manufacturers, public procurers, donors, and private equity investors. This briefing demonstrates the analytic depth of our research while intentionally withholding detailed segment-by-segment tables (regional, drug-type, and application splits) to encourage direct access to the full intelligence package. What follows is a data-driven, action-oriented orientation that highlights the market’s direction, strategic inflection points, competitive dynamics, and the pragmatic tools our full report delivers.
Uterotonic Agent Market
Market trajectory and macro context
The global uterotonic market reached a meaningful scale by 2025 and is set to expand further through the forecast horizon (2026–2032) at a compound annual growth rate of approximately 6.19%. Our base-year assessment (2025) places the market in the lower-mid single billion USD range, with a projected increase into the mid-single billion USD range by 2032 under our central scenario. This growth is driven by a combination of demand stabilization in higher-income procurement streams, accelerated uptake of alternative uterotonics in low-resource settings, and incremental price and mix improvements tied to new formulations, prequalification approvals and tender dynamics.
Uterotonic Agent Market
Key structural facts that should shape 2026 strategy:
Uterotonic Agent Market
- Market concentration is moderate: the three largest players control roughly two-fifths of the market by revenue, and the top five capture well under two-thirds. This provides room for both incumbent scale plays and agile entrants targeting niche geographies or product formats.
- Demand is not homogeneous — procurement decisions are highly sensitive to product attributes (cold-chain dependence, heat stability), regulatory status (WHO prequalification), and price. These non-price factors increasingly drive tender outcomes, especially where donors and multilaterals are active.
- Quality and supply reliability remain critical constraints in several markets; reported instances of severely substandard oxytocin highlight persistent supply-chain failure points and the commercial opportunity for reliable alternatives.
Why 2026 matters: strategic inflection points
Two concurrent shifts create a narrow window for decisive moves in 2026:
- Clinical guidance and procurement policy: WHO-level recommendations continue to favor oxytocin where quality and cold chain can be assured, and recommend heat-stable carbetocin in contexts where cold-chain is unreliable. Procurement agencies and donors are actively updating lists and supplier preferences in response — a trend that will reshape tender criteria and create winners among WHO-prequalified producers.
- Technology and access-compliance: heat-stable formulations, supplier licensing deals, and expanded prequalification activity are lowering barriers to deploying uterotonics in low-resource settings. Licensing agreements that enable local production or non-assertive intellectual property frameworks accelerate scale-up and market access.
Competitive landscape: who matters and why
The competitive terrain is a mix of multinational innovators, global generic houses, and local manufacturers focused on maternal health supply. Our analysis synthesizes capability, regulatory positioning, and route-to-market advantages for the most consequential players:
- Ferring Pharmaceuticals — Strategic differentiator: lead developer and promoter of heat-stable carbetocin. Ferring’s collaboration with global health actors and conditional licensing arrangements position it as a de facto option for donors and governments seeking a cold-chain-free uterotonic.
- Pfizer — Strengths: broad portfolio coverage across oxytocin and misoprostol brands, durable procurement relationships, and scale manufacturing. Pfizer remains a strategic supplier across higher-volume public tenders and private-sector channels.
- Novartis — Role: established oxytocin supplier with clinical brand recognition. Novartis’ participation stabilizes supply in markets where branded originators are still preferred.
- Fresenius Kabi, Hikma, Sun Pharma, Teva — These manufacturers represent the backbone of generic supply in regulated markets. Their strengths are cost-competitive production, global distribution capability, and existing relationships with institutional buyers.
- Cipla, China Resources Zizhu, Acme Formulation — Noteworthy for WHO prequalification status on key misoprostol/oxytocin products. Prequalification remains a decisive credential for access to donor-funded procurement.
- Grindeks, PT Sanbe Farma, Steril-Gene — Producers with a specific focus on oxytocin injection supply and a foothold in international procurement frameworks, often supplying country-level tenders and NGO channels.
- Juhel Nigeria, Emzor — Regional manufacturers in sub-Saharan Africa whose local presence reduces lead times, import dependency and cost for several national programs. Local manufacturing is an increasingly important strategic lever for governments seeking supply security.
Recent institutional moves underline the landscape dynamics: WHO prequalification actions and supplier lists are redefining “qualified” suppliers; the publication of Quality-Assured Supplier Lists for maternal-neonatal-child-health products has accelerated buyer consolidation around prequalified sources; and licensing agreements for heat-stable carbetocin have opened public-sector access pathways in target countries. Each of these developments materially alters procurement calculus and contract design.
Risks, constraints and tactical vulnerabilities
- Cold-chain dependence: standard oxytocin formulations require refrigerated storage, creating quality degradation risk in hot climates and uncertain cold-chain contexts — this remains a key operational constraint for many national programs.
- Quality variability: procurement decisions driven by lowest-price sourcing have historically permitted substandard product penetration. Our field-corroborated evidence of potency failures underscores the reputational and health risks for buyers and suppliers alike.
- Regulatory and reimbursement changes: evolving WHO guidance and donor frameworks can rapidly change demand for specific formulations; suppliers lacking prequalification or adaptive regulatory strategies risk exclusion.
- Supply concentration: despite a fragmented supply base, top players retain meaningful leverage. New entrants must plan for tender-level barriers and buyer preference dynamics.
Opportunities and tactical plays for 2026
Stakeholders that align product, regulatory, and commercial strategies to the evolving procurement architecture will gain disproportionate upside. Recommended plays:
- For originator innovators: accelerate WHO prequalification and public-sector licensing where feasible; prioritize heat-stable formulations and bundled implementation support (training, cold-chain assessments) to win donor-backed tenders.
- For generics and regional producers: invest in quality assurance to secure WHO prequalification and build partnerships with multilateral procurement agencies. Local manufacturing and shorter lead-times are competitive advantages in country-level tenders.
- For institutional buyers and donors: calibrate tender templates to reward verified quality and supply reliability — incorporate lifecycle cost metrics (including spoilage and clinical failure risks) rather than unit price alone.
- For investors: look for buy-and-build opportunities that combine WHO-prequalified assets with regional manufacturing capacity and distribution networks in high-need geographies.
What the full PW Consulting report delivers (practical, operational, and proprietary)
Our comprehensive study is designed to move teams from insight to execution. Highlights of the deliverables include:
- Interactive revenue and demand models (2020–2032) with scenario toggles for cold-chain disruption, donor-pricing shifts, and accelerated heat-stable formulation adoption.
- Country-level procurement and risk heatmaps to prioritize market entry and tender focus for 2026–2028.
- Supplier scorecards mapping manufacturing capability, WHO prequalification status, recent tender performance, and contract-readiness metrics.
- Regulatory tracker and prequalification pipeline with timing estimates and impact assessments on public procurement flows.
- Operational playbooks: cold-chain assessment templates, quality-inspection checklists, and demand-aggregation strategies designed for Ministries of Health and multilateral purchasers.
- Commercial negotiation templates and scenario-tested pricing models for both donor-funded tenders and private-sector channels.
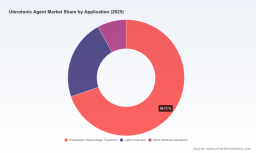
To preserve the integrity of our commercial analyses and encourage a direct engagement, we have intentionally omitted detailed segment splits and country-by-country tables from this brief. The full report contains the granular regional, drug-type and application-level breakdowns, including modeled tender outcomes and price elasticity curves, available on our report landing page.
Final strategic read for 2026
Decisive action in 2026 should focus on three priorities: (1) securing quality credentials and predictable supply (WHO prequalification and transparent QA), (2) aligning product formats with procurement realities (heat-stability where cold-chain is a constraint), and (3) designing commercial models that capture lifecycle value beyond unit price. Organizations that move early to integrate these elements — and to operationalize them through tender-ready evidence and country-level execution plans — will capture the most favorable positions in a market that is growing, consolidating around quality, and becoming more procurement-driven.
PW Consulting’s full Uterotonic Agent Market report supplies the tailored models, competitive benchmarks, and tactical tools needed to convert these insights into high-confidence 2026 decisions. For access to the granular datasets, tender-level scenario outputs, and our advisory packages, please consult the report portal referenced in the executive materials.
For detailed analysis of this topic, please visit the official page: Uterotonic Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


