



PW Consulting: Robot Joint Actuator Market to Reach USD 66,310.66M by 2032 at 18.52% CAGR

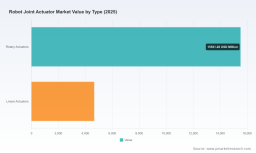
Robot Joint Actuator Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting presents a targeted industry briefing to prepare executives, product leaders and corporate development teams for decisions that will shape their 2026 roadmaps. The robot joint actuator market is entering a phase of accelerated commercialisation and consolidation; our latest study synthesises market sizing, technology benchmarking, regulatory inflection points and competitive positioning into actionable guidance. This introduction highlights why 2026 matters, which strategic tensions will determine winners, and how to prioritise limited resources — while reserving detailed segment-level datapoints for subscribers of the full report.
Robot Joint Actuator Market
Why 2026 is a strategic inflection point
After a sustained expansion through the early 2020s, the robot joint actuator market moves from niche industrial demand into broad-based adoption across humanoid, collaborative and service robotics. Our modelling shows a dramatic trajectory: the market grew strongly between 2020 and 2025 and is forecast to expand further in 2026 and through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 18.52% (forecast period). The combination of accelerating unit demand for integrated joint modules, new product introductions optimised for locomotion and humanoids, and regulatory updates around collaborative operation and cybersecurity creates a unique and time‑sensitive opportunity window for suppliers and OEMs in 2026.
Robot Joint Actuator Market
Put simply: 2026 is the year companies that have been R&D‑heavy must turn investments into scalable product platforms, and the year purchasers must lock in supply and validation pathways to de‑risk deployments. The numbers in our model show this is not incremental growth — it is an adoption curve that rewards speed, integration capability and standards compliance.
Robot Joint Actuator Market
Report deliverables — practical, transaction‑ready intelligence
- Market sizing and high‑resolution growth scenarios (2026–2032) built from supply‑side capacity and demand pull models.
- Go‑to‑market playbooks for vendors and buyers: buy‑vs‑build decision matrices, channel strategies, pricing elasticity models and service monetisation frameworks.
- Technology benchmarks and product scorecards comparing torque density, backlash, thermal performance, IP rating and integrated electronics across representative actuators.
- Supply‑chain and BOM risk maps, including critical material exposures, single‑sourcing risks and tactical mitigation playbooks.
- M&A heatmaps and partnership targets derived from capability gaps, IP holdings and manufacturability analyses.
- Regulatory and compliance checklist aligned to the 2025 ISO and ANSI revisions, focusing on design validation, cybersecurity, and collaborative operation requirements.
- Operational templates: testing protocols, field reliability frameworks and aftermarket service playbooks to preserve lifetime revenue.
Key market dynamics shaping vendor and buyer strategies
- Integration is the new competitive moat. Customers increasingly prize joint modules that combine motor, gearbox, encoders, drives and thermal/packaging engineering into IP67‑class, plug‑and‑play units. The trend reduces system integration timelines but raises the bar for suppliers to own multi‑disciplinary design competence.
- Actuator economics and product mix. Advanced humanoid and mobile platforms are driving demand for ultra‑high torque density and low‑backlash solutions; industry observations at major shows indicate actuators can be the dominant line item in production cost. Suppliers who can deliver compact, high‑efficiency modules at scale will capture disproportionate value.
- Standards and safety as adoption accelerants. The 2025 revisions to ISO 10218 and the aligning ANSI/A3 R15.06 standard broaden requirements for collaborative applications and introduce explicit cybersecurity expectations. Certification pathways will become de facto market access gates in 2026 — early compliance will be a differentiator.
- Material & durability engineering. Advances in high‑carbon steel alloys and precision fatigue design for flexspline components materially extend rated life under cyclical torques; engineering IP around durability is both a quality and a cost lever.
- Serviceability and lifecycle revenue. With higher unit prices for integrated actuators, buyers demand robust warranty, spare parts and field service models. Suppliers who transform service into a predictable revenue stream will improve margins and customer stickiness.
Competitive landscape — who matters and why
The market is moderately concentrated: the top three vendors account for roughly 41% of supplier value, and the top five approach 57%. That structure creates space for focused challengers with technical differentiation and for larger motion companies to expand through product line extensions and partnerships.
Strategic groupings and implications:
- Harmonic‑centric specialists — incumbents with deep proprietary strain‑wave expertise remain the reference architecture for zero‑backlash, high‑precision joints. Their strengths are precision, materials know‑how and established OEM relationships. Expect continued incremental innovation around load life and miniaturisation.
- Integrated actuator challengers — firms delivering motor‑gear‑encoder‑controller packages (including new launches showcased at CES and trade shows) are converting system integrator demand into product roadmaps. Their advantage: faster system validation for robot OEMs and simplified supply chains. Risk: capital intensity and software competency requirements.
- Motion giants and industrial houses — established electro‑mechanical suppliers are leveraging frameless motors, thermal systems and scale manufacturing to move up the stack. They can rapidly commercialise ruggedised platforms for heavy‑duty industrial and mobile applications.
- Regional specialists and emergent OEM suppliers — a cohort of nimble suppliers focuses on humanoid, legged and service segments with aggressive torque density claims and cost engineering. These players can disrupt price tiers but must prove reliability and standards compliance to access enterprise customers.
Recent ecosystem moves are instructive: headline partnerships and product reveals — from trade show demonstrations of fully integrated modules to OEM supply agreements for next‑generation humanoids — validate that 2026 is the year prototypes convert to production commitments. For example, high‑profile supply agreements and product launches have already begun to lock in capacity for 2026 deployments, adding urgency to sourcing and validation decisions.
Strategic recommendations for corporate decision-makers in 2026
- Prioritise platform bets over point innovations. Allocate R&D to modular actuator platforms with upgradeable electronics and predictable thermal envelopes. This protects roadmaps against changing interface standards and shortens OEM validation cycles.
- Fast‑track compliance and security certification. Map product roadmaps to the 2025 ISO/ANSI revisions and invest in supply‑chain traceability and embedded cybersecurity features before customers demand certification evidence.
- Lock supply and capacity early. Given the rapid forecasted growth and concentrated supplier footprints, secure multi‑year supply agreements or alternative sourcing to avoid production bottlenecks in 2026–2027.
- Design for serviceability. Embed diagnostics, modular replaceability and remote support features to turn field economics into recurring revenue and mitigate warranty risk.
- Use M&A and JV selectively. Target acquisitions that fill missing capabilities (e.g., integrated drive electronics, thermal management, or high‑precision gear manufacturing) rather than generic scale plays. The right strategic tuck‑ins shorten time‑to‑market for integrated modules.
- Run scenario planning across three horizons. Prepare for a baseline adoption curve, an accelerated humanoid adoption scenario, and a constrained supply scenario. Use these to size inventory, capital spending and investment gating for 2026.
How PW Consulting’s report turns insight into decisions
This study is built for practitioners. Beyond headline forecasts and narrative, subscribers receive validated supplier scorecards, a purchase‑grade BOM and cost model, structured vendor due‑diligence templates, and an M&A target list mapped to capability gaps. We also provide a regulatory readiness playbook aligned to the 2025 ISO/ANSI updates and a set of scenario models that show how strategic choices made in 2026 materially alter market share and margin outcomes through 2032.
We intentionally limit this public preview to preserve the report’s most actionable segment‑level forecasts and supplier benchmarks. If your 2026 planning cycles include product portfolio decisions, supplier negotiations, capital allocations or M&A screening, procuring the full dataset and the attached strategic annex will materially shorten your time to a defensible decision.
Conclusion — act with calibrated speed
The robot joint actuator market is transitioning from component supply to integrated system enablement. 2026 will reward organisations that combine engineering depth, standards compliance and supply certainty with commercial agility. PW Consulting’s full Robot Joint Actuator Market report equips leaders to move from option generation to decisive action — with the data, templates and competitive intelligence required to capture the next wave of value.
For detailed analysis of this topic, please visit the official page: Robot Joint Actuator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


