



PW Consulting: Paper Coaster Market to Reach USD 807.5 Million by 2032 at 6.2% CAGR

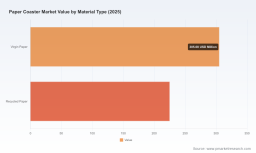
Paper Coaster Market — Strategic Brief for 2026 Corporate Decisions
Executive summary
By 2025 the global paper coaster market reached a clear inflection point: sustained demand across hospitality and promotional channels produced an industry with total revenues of roughly USD 530.0 Million, and our forecast models show a steady compound annual growth rate (CAGR) of approximately 6.2% across the 2026–2032 horizon. That trajectory places the market firmly within the “stable growth, high-fragmentation” quadrant: attractive for targeted investment and operational optimization, but not a winners-take-all arena.
Paper Coaster Market
This paper functions as a strategic preview of PW Consulting’s full Paper Coaster Market report for clients planning procurement, product, M&A, or sustainability moves in 2026. We surface the most consequential dynamics, competitive implications, and prioritized actions — intentionally withholding the granular regional and application tables that accompany the full report to encourage direct engagement and license access to the full dataset and Excel model.
Paper Coaster Market
Why this research matters for 2026 decisions
-
Procurement and category managers are under pressure to balance unit-cost efficiency with tighter sustainability and regulatory requirements. With producer responsibility regimes proliferating in major US states, the true landed cost of paper coaster SKUs will increasingly include end-of-life management and compliance fees.
Paper Coaster Market -
Manufacturers face a bifurcation: compete on low-cost, high-volume offshore supply chains or differentiate through customization, premium materials and rapid fulfillment—each route demands distinct capital, quality control and go-to-market capabilities.
-
Investors and PE sponsors see consolidation potential in a market characterized by low top-five concentration and many regional specialists. Small bolt-on acquisitions that add finishing capabilities, proprietary materials, or channel access can materially increase margins.
Top-line contents and practical value of the full report
The PW Consulting full study combines market-grade data with practitioner tools designed to be operational on Day 1. Highlights include:
-
Validated market sizing (historical 2020–2025 and forward 2026–2032) and scenario forecasts (base, downside, upside) to stress-test CAPEX and procurement commitments.
-
Segment and channel analysis (by material, application and region) presented with sensitivity sliders so users can model outcomes under alternate demand, price and regulation assumptions. Note: regional and application tables are available only in the licensed report.
-
Full cost-stack and margin driver breakdown: input-cost benchmarks, labor and freight sensitivity, finishing/printing cost curves, and material substitution thresholds (e.g., virgin vs recycled fibers).
-
Supplier and capability matrix: operational benchmarking of leading manufacturers, common certifications and compliance gaps, production lead-times, and finishing technology comparisons.
-
Go-to-market playbooks for manufacturers, brand owners and distributors — including SKU rationalization frameworks, price-index clause templates for long-term contracts, and a rolling 24-month raw-material hedge playbook.
-
Regulatory impact maps and EPR compliance roadmaps tailored for US and EU contexts, plus an action checklist for establishing producer responsibility organization (PRO) partnerships.
-
Deal screening and M&A scorecards with financial thresholds and integration red flags specific to the paper coaster subsector.
-
An editable Excel model and slide toolkit for board-level presentations and procurement negotiations.
Competitive landscape — who matters and why
The market is characterized by a mix of regional manufacturers with deep production expertise, branded suppliers focused on hospitality channels, and low-cost exporters. The top three/five firm concentration metrics indicate a dispersed market structure, which creates both pricing pressure and acquisition opportunities.
-
Coaster Factory (United States): Direct North American manufacturer with strengths in high-volume pulpboard production and advanced finishing (UV spot gloss, foil stamping). Strategic advantage: rapid customization and shortened lead times for restaurant and bar chains seeking branded coasters. Considerations: premium onshore cost base but defensible with service-level and finish differentiation.
-
Alfred Mank (Germany): European specialist in higher-grade materials (e.g., airlaid substrates) and moisture-management solutions. Strategic advantage: premium material portfolio and European distribution footprint; attractive partner for mixed-channel hospitality customers needing higher absorbency and brand presentation. Considerations: premium pricing and exposure to European packaging regulation.
-
Hoffmaster (United States): Established producer of pulpboard and budgetboard coasters in standard formats with emphasis on durability. Strategic advantage: broad product range for foodservice and beverage sectors; scale in legacy channels. Considerations: pressure to innovate material and sustainability credentials.
-
Totally Promotional (United States): Focus on promotional coasters with emphasis on full-color imprinting and eco-friendly messaging. Strategic advantage: tight integration to promotional channels and brand campaigns. Considerations: high SKU churn and sensitivity to promo budgets.
-
Singreen Package & Guangzhou Zhi Xiang (China): Cost-competitive bulk manufacturers focused on export markets and promotional coasters. Strategic advantage: scale manufacturing and price leadership for non-time-sensitive volume buys. Considerations: longer lead times, tariffs/shipping volatility, and increasing scrutiny under EPR regimes and customer sustainability policies.
Implication for buyers and investors: domestic manufacturers capture value through customization, speed and compliance services; offshore producers compete on unit economics. A deliberate sourcing strategy — blending nearshore manufacturing for premium SKUs and offshore for commoditized volumes — is the optimal posture for many enterprise buyers in 2026.
Cost, supply and regulatory dynamics to watch in 2026
Three structural forces will define supplier margins and buyer pricing into 2027:
-
Raw-material and logistics volatility: Pulpboard and paperboard feedstock prices exhibit regional dispersion and episodic spikes. Manufacturers that lock in multi-year supply or deploy index-linked pricing pass-throughs will better protect margins. Buyers should demand transparent input-cost clauses and dual-sourcing contingencies.
-
Regulatory acceleration — EPR and recycling mandates: Several U.S. states have enacted Extended Producer Responsibility (EPR) legislation that brings packaging and paper products into producer-funded end-of-life schemes. These laws are phasing in responsibilities, funding, and reporting requirements through the late 2020s. Manufacturers and brand owners must plan for added compliance costs, PRO engagement, and product design-for-recyclability investments.
-
Customer and brand sustainability expectations: Corporate ESG targets and hospitality chain procurement policies are raising the bar for recycled content, compostability and verified recycling streams. Firms that can provide verified chain-of-custody documentation and measurable end-of-life solutions will command premium contracts.
Prioritized strategic actions for 2026
Below are pragmatic, prioritized moves we advise clients to consider this year. Each recommendation is accompanied by an execution-ready checklist in the full report.
-
Manufacturers: Invest selectively in finishing capabilities that customers cannot easily source offshore (e.g., specialized coatings, rapid color turnaround). Pilot takeback programs in partnership with local PROs to mitigate EPR exposure and create new service revenue.
-
Brand owners / Foodservice chains: Rationalize coaster SKUs into a minimal set of certified, recyclable SKUs for mass channels while maintaining a premium custom set for flagship locations and events. Include explicit EPR-cost apportionment clauses in supplier contracts.
-
Procurement teams: Implement a dual-sourcing strategy: onshore partners for short-lead, high-touch SKUs; vetted offshore manufacturers for tolerant, high-volume promotional items. Negotiate pricing with transparent input indexes and minimum order flexibility.
-
Investors and M&A teams: Target companies that deliver either specialized materials (airlaid/PE-laminated substrates), advanced finishing, or regional distribution networks. Focus on tuck-ins with immediate margin uplift potential via cross-selling and footprint rationalization.
Next steps — how to use the full PW Consulting study
The full report provides the quantitative inputs required to operationalize the recommendations above: detailed regional and application tables, supplier revenue estimates, a raw-material price matrix, and the scenario-ready Excel model. For procurement negotiations, board briefings, or transaction diligence in 2026, these deliverables shorten decision cycles and reduce execution risk.
To access the full dataset, granular segmentation, model files, and the supplier playbooks referenced here, please consult the licensed report page. The downloadable tools will allow you to:
-
Stress-test contract structures against price shocks and evolving EPR cost curves;
-
Score potential acquisition targets across production capability, regulatory exposure and channel fit;
-
Customize SKU rationalization templates and supplier RFPs for immediate deployment.
Conclusion
The paper coaster market in 2026 is a classic operationally-driven growth opportunity: modest top-line expansion coupled with outsized value from process, sourcing and regulatory optimization. Whether you are a manufacturer looking to defend margins, a brand owner seeking supply certainty and ESG alignment, or an investor hunting consolidation targets, the stakes and levers are clear — and actionable. PW Consulting’s full report provides the confidential, transaction-grade detail and tools to move from strategy to execution with confidence.
For detailed analysis of this topic, please visit the official page: Paper Coaster Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


