



PW Consulting: Fused Silica Tubing Market to Reach USD 845M in 2025 with 6.12% CAGR

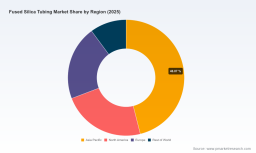
Fused Silica Tubing Market — Strategic Preview for 2026 Decision Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused industry primer to orient executive teams, corporate strategists, and investors preparing for decisions in 2026. This briefing distills the actionable implications of our full Fused Silica Tubing Market study — highlighting market trajectory, structural dynamics, competitive posture, and the pragmatic scenarios that should drive capital allocation, sourcing policy, and product strategy in the year ahead. The complete report contains the granular segmentation and primary-source datasets referenced here; those breakdowns are intentionally withheld in this preview to preserve the report’s proprietary value and to encourage direct access to the source publication.
Fused Silica Tubing Market
Why this market matters in 2026
Fused silica tubing is a high-leverage input across capital-intensive industries — notably semiconductor processing, specialty optics, analytical instrumentation, and UV/laser applications. After steady growth through the early 2020s, the market’s aggregate value reached USD 845.0 million in our base year (2025), following a sustained expansion from USD 635.4 million in 2020. Our forecast expects continued expansion through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.12%, progressing toward a market size above USD 1.28 billion by 2032.
Fused Silica Tubing Market
For leadership teams, this growth profile signals two concurrent imperatives in 2026: (1) prioritize supply-chain resilience and premium product differentiation to capture higher-margin demand, and (2) calibrate capacity investments and partnership strategies against tightening feedstock dynamics and regulatory shifts that disproportionately affect ultra-high-purity production.
Fused Silica Tubing Market
Key market dynamics shaping 2026 choices
-
Feedstock concentration and premiumization: High-purity quartz (HPQ) remains the critical upstream constraint. HPQ commands a substantial premium relative to bulk silica grades, with purity tiers influencing both price and manufacturability of semiconductor-grade tubing. The geographic concentration of HPQ sources (notably a small set of global deposits and established supply hubs) creates asymmetric exposure to mine-level restrictions, environmental permitting, and transport disruption — issues that surfaced repeatedly in 2024–2025. Procurement teams must evaluate multi-sourcing, long-term offtake agreements, and strategic stockpiles as part of standard 2026 playbooks.
-
Demand mix volatility: While semiconductor-grade demand underpins long-term growth, other end-markets (fiber-optics, laboratory instrumentation, UV/lighting) offer differentiated cycle profiles and product requirements. Our analysis shows the total market expanding steadily, but the underlying mix is shifting toward higher-purity, larger-diameter, and specialty-coated tubing — a trend that favors manufacturers with advanced fusion processes and in-house quality control capabilities.
-
Regulatory and trade uncertainty: Environmental mining restrictions and tariff negotiations have tangible cost and access implications for HPQ and finished tubing. These forces increase the value of localized manufacturing footprints and vertically integrated supply chains for firms serving high-security or high-reliability customers. Scenario planning for 2026 should explicitly price in periodic tariff excursions and stricter feedstock export controls.
-
Market concentration and strategic implications: The industry exhibits meaningful concentration at the top — the three- and five-firm concentration ratios indicate that leading suppliers control a majority of the market. This structural reality supports disciplined pricing, rapid technology diffusion by incumbents, and favorable economics for bolt-on capacity expansions. It also opens opportunities for focused challengers to carve niches through specialization (e.g., unique fusion processes, large-diameter cylinders, ultra-low fluorescence tubing).
What the full report provides — practical, transaction-ready components
Our full study is designed as a playbook for executives making near-term decisions. Key actionable deliverables included in the full report are:
- Validated market-sizing and demand-model workbook (2020–2032) with scenario toggles for volume, mix, and pricing inputs.
- Supply-chain heatmaps and vulnerability assessment for HPQ feedstock, logistics chokepoints, and single-source exposures.
- Commercial playbook for procurement: supplier scorecards, contract negotiation levers (pricing indexation, long-term vs. spot balance), and recommended inventory bands under different risk scenarios.
- Product and technology matrix benchmarking fusion processes (electrical fusion, plasma fusion, flame fusion, and synthetic silica routes), coating options, and ISO/cleanroom readiness checklists for semiconductor customers.
- Five strategic scenarios (base, accelerated semiconductor investment, PV re-acceleration, raw-material disruption, and trade-restriction shock) with quantified P&L and capacity utilization impacts for typical OEMs and tubing suppliers.
- M&A and partnership shortlist (tiered by strategic intent: access to HPQ, process know-how, capacity expansion, or market access) and a valuation sensitivity framework tied to revenue-growth and margin expansion levers.
- Regulatory and ESG playbook covering environmental permitting risks, sustainable sourcing options for HPQ, and disclosure templates for investor communications.
Competitive landscape — who matters and why
Leading incumbents combine scale, niche process capabilities, and channel access. The competitive set we profile in detail includes established multinational producers, specialized European premium players, large chemical groups with quartz divisions, and regional integrated manufacturers. Their differentiators — process technology, product breadth, capacity footprint, and customer intimacy — map directly to the strategic choices buyers and investors face in 2026.
-
Multi-national incumbents — firms with global production footprints and diversified end-markets are best positioned to absorb feedstock shocks and to offer bundled supply solutions to semiconductor fabs and industrial OEMs. Their scale enables investment in advanced fusion and inspection capabilities that support large-diameter and high-yield tubing runs.
-
Process specialists — players leveraging unique fusion approaches (e.g., plasma-fusion or proprietary tool-free high-purity manufacturing) are capturing higher-margin specialty orders, particularly where optical clarity, low fluorescence, or very large OD tubing are required.
-
Precision-capillary and coated tubing specialists — manufacturers focused on polyimide-coated capillaries and microfluidic applications retain strong positions in analytical instrumentation; their technical capabilities and customer certifications create high switching costs.
Notable developments underscoring these dynamics include recent capacity investments at major fusion centers and catalogue expansions from specialized fabricators — evidence that the market favors both scale and customizable short-run capabilities. The full report contains company-level SWOTs, capacity maps, and interview excerpts that illuminate where future battles for specification control will occur.
Implications for 2026 corporate strategy
-
Procurement & Sourcing: Treat HPQ as a strategic raw material. Move from transactional purchasing toward structured offtake agreements, supplier development partnerships, and dual-sourcing for critical grades. Quantify the cost of supply interruption in your 2026 planning cycle and hold contingency liquidity for rapid inventory replenishment if required.
-
Product & R&D: Prioritize investments in process controls and downstream finishing (coatings, laser/UV-stable treatments) that differentiate your offering versus commodity tubing. A modest R&D program targeted at reducing defect yield by a few percentage points can deliver outsized margin impact given high unit values.
-
Capacity & Footprint Decisions: Use the report’s scenario model to stress-test greenfield vs. brownfield expansion choices. Where regulatory or trade risk is acute, near-shoring or regional partnerships may be preferable to speculative global capacity allocation.
-
M&A & Partnership Strategy: Look for targets that either fill process gaps (e.g., unique fusion technology) or provide immediate feedstock access and regional market entry. Our M&A framework ranks candidates against integration complexity and immediate revenue accretion potential.
How to use this preview — and where to get the full intelligence
This briefing is intentionally strategic and directional. It synthesizes the market’s macro trajectory — which grew from the mid-six-hundred millions in 2020 to USD 845.0 million in 2025 and is forecast to reach north of USD 1.28 billion by 2032 at a 6.12% CAGR — while withholding the granular regional and application splits reserved for the full study. Those detailed segmentation tables, primary-source interview transcripts, and the interactive model are the levers your strategy and finance teams will need to finalize 2026 budgets, procurement commitments, and M&A mandates.
To access the complete report with the full datasets, behind-the-scenes supplier assessments, and the downloadable scenario model, visit the PW Consulting market portal or contact our industry desk. Our consulting teams are available to run a tailored 90-minute executive workshop that applies the model to your firm’s specific product mix, supplier set, and risk tolerance — producing a prioritized, budget-ready action plan for 2026.
Final word
Fused silica tubing is a technically specialized, strategically important market where small improvements in purity, yield, or supply continuity translate to material commercial advantage. In 2026, competitive advantage will accrue to those who combine disciplined procurement, selective capacity investments, and differentiated product offers — all underpinned by rigorous scenario planning. PW Consulting’s full study equips decision-makers with the quantitative backbone and qualitative insight required to make those calls with confidence.
For detailed analysis of this topic, please visit the official page: Fused Silica Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


