



PW Consulting: Built-In Electric Curtains Market at USD 3,248.5M in 2025; 10.51% CAGR (2026–2032)

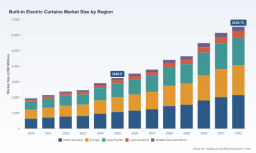
Built-In Electric Curtains Market — A 2026 Strategic Preview for Decision‑Makers
PW Consulting’s latest market research on Built‑In Electric Curtains frames the next investment cycle for product managers, procurement leads, real‑estate developers and systems integrators. Anchored on a 2025 base year and projecting through 2032, the study quantifies a high‑growth landscape: the market expands at a compound annual growth rate (CAGR) of 10.51% over the forecast window. Our topline sizing shows a multi‑year climb from the early 2020s into a substantially larger market by the end of the decade (figures in USD Million). This preview synthesizes the strategic implications you need to act in 2026 while intentionally holding back detailed sub‑segment tables — those are reserved for the full report.
Built In Electric Curtains Market
Why built‑in electric curtains matter now
-
Smart‑home and intelligent building adoption is shifting specification patterns. Stakeholders are moving away from add‑on retrofit motors toward fully integrated, recessed or track‑based systems that preserve interior design while delivering automation and energy‑management benefits.
Built In Electric Curtains Market -
Technology convergence (low‑power wireless standards, local bridging, cloud services and software ecosystems) is transforming curtain systems from discrete mechanical products into platform opportunities — unlocking recurring revenue through services, updates and integrated building control.
Built In Electric Curtains Market -
Cost dynamics and regulation are compressing time‑to‑market for new designs. Raw‑material duties and component import tariffs increase landed costs for motors and aluminum extrusions; safety standards (notably ANSI/WCMA A100.1‑2022) further influence product form factors and customer acceptance.
Market trajectory — what the numbers signal for strategy
The market’s 10.51% CAGR reflects a combination of accelerating demand in premium residential and commercial segments, growing retrofit activity in retrofit‑heavy regions, and stronger specification for integrated systems in new construction. From a strategic perspective, that growth rate creates three simultaneous imperatives for business leaders entering 2026:
-
Scale to capture volume while protecting margin — growth will reward players who can manage supply‑chain cost inflation and offer differentiated integration capabilities.
-
Differentiate through software and services — the hardware commodity risk rises unless firms bundle persistent value (control platforms, analytics, maintenance plans).
-
Manage regulatory and trade exposure — tariffs on motors, fabrics and aluminum extrusions, and safety standards eliminating free‑hanging cords, require product redesign and more agile sourcing.
What the full PW Consulting report delivers (practical, actionable)
This research is designed as a decision‑support toolkit for 2026 and beyond. Key deliverables include:
-
A validated market model with annual sizing (base 2025) and granular forecasts to 2032, including scenario analyses that stress tariffs, raw‑material cost swings and adoption curves for wireless platforms.
-
Go‑to‑market playbooks for three archetypes: OEM suppliers, branded system integrators, and channel/installer networks. Each playbook contains recommended product roadmaps, pricing levers, and channel incentive structures.
-
Supply‑chain diagnostics and mitigation templates: cost‑build models (motor, track, electronics, fabric), supplier concentration mapping, and contingency plans for duties and logistics disruptions.
-
Regulatory and standards tracker with practical compliance checklists (including ANSI/WCMA A100.1‑2022 implications) to accelerate safe‑to‑ship timelines.
-
Detailed competitive profiles and SWOTs for market participants, plus M&A and partner scouting lists for acquisition or alliance strategies.
-
Case studies on built‑in installations across residential, hospitality and institutional sites demonstrating OPEX impacts, installation workflows and specification language templates for architects and consulting engineers.
Note: this preview intentionally avoids publishing the detailed regional, power‑source and end‑use splits. Those core segmentation matrices and the revenue tables that many practitioners require are available exclusively in the full report.
Competitive landscape — practical takeaways
-
Market structure: The market displays a moderate concentration with top‑three players holding a substantial share and top‑five further extending reach. This dynamic creates a two‑tier opportunity: large platform players will continue to dominate high‑spec projects, while nimble challengers can win in retrofit, mid‑market and regional channels.
-
Player archetypes and strategic moves:
-
Platform integrators: Companies with deep system control capabilities focus on bundled lighting/shading ecosystems and premium residential/commercial specifications. Their competitive edge is integration with building automation platforms and channel relationships with designers.
-
Component specialists & OEMs: Providers of motors and tracks maintain margin by selling into both branded systems and white‑label channels; securing OEM contracts and scale manufacturing is core to their playbook.
-
B2B smart window suppliers: Newer entrants leveraging modern interoperability stacks (e.g., Matter/Thread) and rechargeable motor designs emphasize clean integrations and faster installer experiences.
-
-
Notable companies to watch: Established leaders bring scale and integration depth, while specialized track and motor manufacturers control critical component roadmaps. Recent product launches — for example, a 2025 introduction of a Matter bridge and showroom suite by a smart window covering B2B brand — illustrate how interoperability and customer experience are now front‑and‑center in product roadmaps.
Regulatory and cost headwinds — how they influence 2026 decisions
-
Tariffs and import duties: Motor components, fabrics and aluminum extrusions face import levies that can add materially to landed costs. Pricing strategies must account for potential 10–25% tariff exposures on specific components depending on origin and customs classification.
-
Standards and safety: ANSI/WCMA A100.1‑2022 and similar regional safety requirements accelerate the normalization of motorized solutions in place of hazardous free‑hanging cords; product development teams must embed compliance early to avoid late‑stage redesigns.
-
Raw‑material duties and supply risk: Additional duties on aluminum and tubular components increase production costs for integrated tracks, making near‑shoring and supplier diversification strategic priorities.
Priority actions for 2026 — a tactical roadmap
-
Secure your component supply chain: Lock multi‑year agreements with motor and extrusion suppliers, include tariff‑pass‑through clauses and evaluate local assembly to mitigate import duties.
-
Design for standards and retrofit: Revisit mechanical designs to meet ANSI/WCMA requirements and reduce installation time; create retrofit kits that minimize structural work in the field.
-
Invest in interoperability: Accelerate support for open ecosystems and bridges (Matter/Thread, Zigbee integrations) to be chosen by system integrators and smart‑building specifiers.
-
Develop a service monetization plan: Pilot subscription models for remote diagnostics, preventive maintenance and software feature tiers tied to installations.
-
Model scenario P&Ls: Run sensitivity analyses for tariff shocks, aluminum price spikes and slower adoption to inform pricing, inventory and new product launch timelines.
-
Plan selective partnerships and M&A: Where time to capability matters, pursue minority stakes or distribution deals with regional installers, or acquire niche track/motor specialists to internalize margin and IP.
Using this preview — next steps
This article is a curated preview designed to inform 2026 strategic planning. For commercial teams, the report is a playbook: it contains the full revenue matrices, regional and end‑use splits, channel economics and supplier lists that operationalize the recommendations above. For product leaders, the report includes design impact analyses and compliance roadmaps. For M&A and corporate development teams, it contains target scouting and valuation sensitivities tied to the sector’s growth profile.
PW Consulting’s full Built‑In Electric Curtains Market report is the source of the detailed segmentation, vendor scorecards and downloadable modeling assets referenced here. To access the full intelligence package and data tables required to convert the strategic priorities above into executable plans, please visit our report page or contact our industry team.
For detailed analysis of this topic, please visit the official page: Built In Electric Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


