



PW Consulting: Fuel Vapor Canisters Market to grow at 3.42% CAGR through 2032

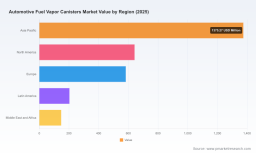
Automotive Fuel Vapor Canisters Market — Strategic Preview for 2026 Decisions
Executive trailer: what this preview delivers
As original equipment manufacturers (OEMs), Tier‑1 suppliers, aftermarket specialists and private‑equity investors plan for the critical 2026 decision window, the Automotive Fuel Vapor Canisters market presents a mix of steady growth, regulatory-driven technology demand and concentrated supplier economics. This preview synthesizes the macro trajectory (historical performance and base‑case forecast through 2032), the regulatory inflection points that will shape product specifications, and the supplier dynamics that matter when allocating R&D, procurement and M&A capital. The aim is to show the analytical depth that informs PW Consulting’s full study while intentionally withholding the granular segmentation tables and line‑item forecasts that are available in the full report.
Automotive Fuel Vapor Canisters Market
Market snapshot: scale, rhythm and near‑term outlook
Between 2020 and 2025 the market expanded modestly, reflecting the interaction of vehicle parc dynamics, tightening evaporative‑emission regulations, and the continued role of combustion powertrains in global mobility. In 2025 the global market reached approximately USD 2.95 billion. Under PW Consulting’s baseline modelling — which incorporates regulatory timelines, OEM cycle plans and material‑supply assumptions — the market is expected to grow at a compound annual growth rate of about 3.42% through the 2026–2032 forecast window, reaching an estimated market size north of USD 3.7 billion by 2032. This is a growth profile of steady, regulation‑anchored demand rather than explosive expansion, and it implies different strategic priorities than markets driven primarily by disruptive technology adoption.
Automotive Fuel Vapor Canisters Market
Why 2026 is a strategic inflection
- Regulatory alignment and product specifications: New evaporative emission test procedures and running‑loss standards adopted by major regulators have a phase‑in cadence that centers on 2026–2028. These standards do more than tighten acceptable emissions — they prescribe test protocols, working‑capacity criteria and size/pressure thresholds that materially affect canister designs, media formulations and system packaging.
- OEM program timing: Vehicle program development cycles mean that specification freezes and supplier selection decisions made in 2026 influence model years launching through the late 2020s. Suppliers that can demonstrate compliance at program sign‑off stand to win multi‑year content partnerships.
- Supply chain tightening for activated carbon: The adsorbent media at the heart of most canisters is subject to feedstock variability and capacity bottlenecks. Securing validated media—both in performance and in sustainable sourcing—becomes a procurement priority as OEMs push for validated high‑capacity media to meet new testing regimes.
What the PW Consulting report contains (practical, decision‑grade content)
The full study is built to support capital allocation, product roadmaps and commercial negotiation through:
Automotive Fuel Vapor Canisters Market
- Proprietary market sizing and a clear, auditable forecast model (2026–2032) that ties unit volumes to vehicle production scenarios, regulatory adoption curves and technical upgrades in canister design.
- Technology and test‑protocol gap analysis that maps regulatory requirements (e.g., running loss, butane working capacity and breakthrough criteria) to product attributes — media capacity, flow characteristics, purge strategies and canister sizing constraints.
- Procurement playbooks for activated carbon and composite housings: supplier scorecards, risk heatmaps and inventory/contract structures to mitigate feedstock and freight volatility.
- Go‑to‑market recommendations for OEMs and aftermarket players, including channel segmentation, warranty risk assessment and pricing sensitivity under different regulatory and fuel blend scenarios (gasoline, ethanol blends, LPG and methanol variants).
- Deal rationales for M&A and JV candidates, including financial thresholds, integration pitfalls and a framework for valuing proprietary media formulations or modular canister platforms.
Concrete tools include a scenario‑driven forecast workbook, supplier negotiation checklists and regulatory compliance matrices — all designed for immediate operational use by procurement, engineering and corporate development teams.
Competitive landscape: who matters and why
The market is commercially concentrated: a limited set of established suppliers dominate global content for activated carbon canister systems while a mix of aftermarket specialists and materials producers shape the complementary value chain. The players profiled in the study illustrate the strategic choices facing buyers and investors:
- PHINIA Inc. — A specialist with deep expertise in modular carbon canisters and integrated OBD/evaporative solutions. PHINIA’s long product lineage and modular approach make it a natural partner for OEMs that require flexible tank‑size support and fuel‑blend compatibility.
- A. Kayser Automotive Systems GmbH — A market leader in activated carbon canister systems, with full systems capability (valves, ventilation and purge lines). Kayser’s systems depth positions it to capture engineering content beyond the canister itself, which raises competitive barriers to smaller suppliers.
- MAHLE GmbH — An OEM‑grade supplier with integrated fuel management platforms. MAHLE’s scale and engineering resources allow it to drive system integration wins where thermal and packaging constraints must be solved across powertrain architectures.
- Standard Motor Products, Inc. (SMP) — A dominant aftermarket player with an expansive EVAP program and recent program and product expansions in 2025–2026. SMP’s aggressive coverage on late‑model applications underscores aftermarket growth opportunities and the importance of spares availability for in‑service fleets.
- MotoRad — Focused on EVAP canisters for replacement and service markets; a reminder that aftermarket channel strategies and warranty economics can support differentiated pricing and margin profiles versus OEM supply.
- Ingevity Corporation — A leading activated carbon producer whose hardwood‑based media is widely used in automotive EVAP systems. Media suppliers like Ingevity influence technical capability, validation timelines and, crucially, raw material availability.
Recent public moves — for example, SMP’s program expansions announced in mid‑2025 and early‑2026 — signal the aftermarket’s proactive response to fleet replacement needs and late‑model coverage. Regulatory updates (notably CARB’s 2022 adoption of new evaporative test procedures) functionally elevate the technical bar for all suppliers and accelerate qualification timelines for media and modules.
Regulatory & material dynamics that will shape supplier economics
- Test protocols become product drivers: Rules that define working‑capacity (for example, butane loading and 2‑gram breakthrough criteria), stabilization cycling and purge protocols create engineering targets. Suppliers that invest in test‑bench validation and can provide OEMs with documented compliance will command a premium in supplier selection.
- Feedstock and capacity risk for activated carbon: High‑capacity, durable adsorbent media is not a commoditized input in automotive EVAP contexts. Variability in feedstocks and converting capacity can create multi‑quarter qualification lead times; buyers should consider multi‑sourcing, inventory buffer strategies and strategic contracts with performance clauses.
- Design complexity and system integration: As evaporative regimes broaden to cover running loss, diurnal and hot‑soak emissions, canister solutions increasingly need multi‑layer media, high‑flow passages and integrated control valves. Suppliers with systems capability (canister + valves + lines + OBD integration) extract higher content per vehicle and create switching costs.
Practical strategic moves for executives in 2026
- For OEMs and Tier‑1s: Fast‑track canister validation projects tied to regulatory deadlines; prioritize suppliers that can demonstrate test‑bench data under the adopted protocols. Incorporate performance‑based contracting with media suppliers (e.g., warranty‑linked adsorption metrics) to de‑risk compliance.
- For suppliers and materials firms: Differentiate on validated media performance and systems integration capability. Consider modular platforms that allow tuning of media volumes and purge strategies across vehicle programs to increase addressable content without reinventing packaging.
- For aftermarket players: Leverage late‑model coverage expansions and warranty repair trends to build recurring revenue streams. Strengthen logistics and SKU rationalization to reduce time‑to‑repair for high‑utilization fleets.
- For investors and M&A teams: Target bolt‑on acquisitions that add validated media capacity, systems integration know‑how or regional manufacturing footprint in high‑volume OEM hubs. Avoid assets that are long on product but lack documented compliance to the latest test procedures.
Risk matrix — what could upset the base case
- Accelerated EV adoption in specific markets: Faster‑than‑expected electrification in key regions would reduce demand for ICE canisters and compress the market sooner than modelled.
- Feedstock shocks: Disruptions in activated‑carbon feedstock or conversion capacity could spike prices and materially affect supplier margins and qualification timelines.
- Regulatory variance: Divergent test interpretations or delayed implementation in major markets can create asymmetric adoption and inventory build cycles; this favors suppliers with geographic diversification.
Conclusion — the 2026 decision agenda
For organizations making strategic commitments in 2026, the fuel vapor canister market requires a focused, evidence‑based approach: prioritize validated technical compliance, secure media supply under performance guarantees, and evaluate partnerships that raise system‑level content rather than simply component supply. The market’s steady growth and regulatory anchoring create predictable opportunity — but converting that into durable commercial advantage hinges on execution across engineering validation, procurement design and channel strategy.
Next step
PW Consulting’s full Automotive Fuel Vapor Canisters Market report provides the detailed segmentation, supplier scorecards, scenario financials and downloadable forecast model needed to operationalize the recommendations above. To access the proprietary tables, regional and application splits, and the complete forecast workbook, please consult the report brief on our website or contact our industry team for a demonstration.
For detailed analysis of this topic, please visit the official page: Automotive Fuel Vapor Canisters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


