



PW Consulting: Walk-In Humidity Chambers Market Set to Expand at 6.3% CAGR (2026–2032)

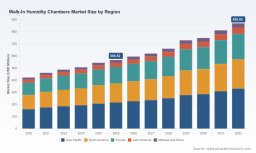
Walk In Humidity Chambers Market 2026: Strategic Preview for Executive Decision-Making
As organizations finalize capital and product development plans for 2026, the walk in humidity chambers market presents a predictable yet strategically nuanced growth corridor. At PW Consulting we frame this corridor not merely as an aggregate revenue trend — from USD 422.15 Million in 2020 to USD 566.52 Million in 2025 — but as a set of operational inflection points that will determine supplier selection, facility investments, and product roadmaps through the 2026–2032 forecast horizon. Our base-case outlook points to continued expansion (project-level CAGR of 6.3% across 2026–2032), culminating in a market that approaches USD 869 Million by 2032. This preview explains why that growth matters to senior leaders, what tactical choices it forces in 2026, and where the full research delivers the actionable detail your teams will need.
Walk In Humidity Chambers Market
Why this market matters to 2026 corporate plans
-
Testing and validation are moving from delegated lab hours to dedicated in-house facilities. Firms in electronics, aerospace, pharmaceuticals, automotive (including EV battery testing), and medical devices increasingly view controlled-environment capacity as a strategic asset rather than a commoditized service.
Walk In Humidity Chambers Market -
Regulatory and quality requirements continue to tighten — especially for pharmaceutical stability testing where ICH and FDA-aligned control regimes demand precise long-term humidity and temperature profiles. Compliance risk is now directly tied to chamber specification and ongoing calibration capability.
Walk In Humidity Chambers Market -
Operational priorities — energy efficiency, uptime, and digital monitoring — are reshaping procurement. Buyers are prioritizing total cost of ownership and service networks over first-cost alone.
Market trajectory and what it implies for 2026 decisions
The market’s steady expansion over 2020–2025 and the projected growth through 2032 reflect a combination of sustained demand from regulated industries and rising requirements in sectors such as battery testing and industrial electronics. For 2026 planning cycles, that translates into three immediate imperatives for executives:
-
Prioritize modularity and scalability in capital investments. Demand patterns are uneven across industries and product lifecycles; solutions that permit phased build-outs or reconfiguration will preserve optionality.
-
Factor in service and qualification capability as a negotiated deliverable. Long-term stability studies and high-value product testing are only as reliable as the maintenance, recalibration, and documentation chains that support them.
-
Accelerate energy-efficiency retrofit and specification standards. With operational runtime accounting for most lifetime cost, energy performance is a near-term differentiator.
Supply chain and component signals
-
Core construction relies on stainless-steel interiors and specialized insulation; procurement teams should expect periodic pressure on these inputs. High-performance compressors and precision humidity sensors are supply nodes with elevated risk profiles — a small number of specialized suppliers and rising demand for accurate control systems create potential bottlenecks.
-
Because humidity sensor availability and quality directly affect test validity, technical due diligence on sensor suppliers (including calibration traceability) needs to become a standard step in vendor qualification.
-
Manufacturers are responding with design choices that reduce exposure: modularized panels, standardization of control electronics, and options for local sourcing of common components. Buyers should insist on BOM transparency where long-term service is critical.
Regulatory and standards landscape
Regulatory frameworks are a major driver of product specification. Walk in humidity chambers intended for pharmaceutical stability testing must meet ICH conditions for long-term and accelerated studies, and many are engineered to comply with FDA, GMP, ISO 17025 and CE requirements. For 2026 procurement and validation plans that support regulated product launches, compliance pathways must be mapped into procurement timelines — including IQ/OQ/PQ sequences, software validation for monitoring systems, and documentation for audit readiness.
Competitive landscape — who matters and why
The market structure reflects a mix of specialized incumbents and regional manufacturers. The three- and five-firm concentration ratios (CR3 ~31.4%, CR5 ~42.8%) indicate a moderately fragmented market where specialist capabilities and service footprints offer meaningful differentiation.
-
BINDER GmbH (Tuttlingen, Germany) — Notable for ICH-focused walk-in solutions and advanced monitoring options. Recent strategic M&A has expanded its pharmaceutical stability reach and control-system capabilities.
-
Russells Technical Products (Holland, MI, USA) — Offers modular W-Series designs and altitude testing options, positioning it well for niche applications requiring custom thermal-humidity-altitude envelopes.
-
Weiss Technik North America (Grand Rapids, MI, USA, including CSZ) — Broad product range and brand depth across environmental simulation with recent manufacturing capacity expansion signaling stronger North American supply resilience.
-
Associated Environmental Systems (AES, North Chelmsford, MA) — Emphasizes custom and heavy-duty builds; recent facility relocation nearly doubled manufacturing space, a clear play for larger-volume and bespoke programs.
-
Darwin Chambers Company — Focused on pharmaceutical walk-in rooms and GMP storage; a preferred partner for organizations looking to outsource design-build-install projects with regulatory alignment.
-
Parameter Generation & Control (A BINDER Company) — Known for rapid-delivery lines and standard sizes tuned to stability testing; now integrated into a larger platform to extend reach and delivery capability.
-
Testron Group & Wewon (China-based providers with US support) — Competitive on lead times and customization, increasingly focused on sustainability (ISO14001) and regional aftersales networks.
Recent moves matter: BINDER’s acquisition of Parameter Generation & Control (July 2025) demonstrates consolidation aimed at vertical capability in pharmaceutical stability systems. AES’s and Weiss Technik North America’s manufacturing expansions (late 2025 and 2026 respectively) signal that suppliers are allocating capital to capacity and near-shore production — a response to demand growth and to customer preferences for shorter lead times and local service footprints.
Strategic questions for 2026 planning cycles
-
Do we treat controlled-environment capacity as a capital asset or an outsourced service? The answer will vary by industry and product lifecycle stage — but for regulated product portfolios, in-house control often mitigates supply and scheduling risk.
-
What level of supplier consolidation reduces risk without sacrificing innovation? The market shows room for specialists; however, consolidation trends indicate benefits from platform capabilities (software-enabled monitoring, rapid delivery, qualification services).
-
How will energy and lifecycle costs alter the ROI on replacement vs retrofit? Incorporating energy modeling and TCO runs during 2026 procurement cycles can change the preferred vendor, especially for high-utilization environments.
-
Which vendors demonstrate validated compliance workflows and documentation for IQ/OQ/PQ — and can they provide sustained local calibration support?
What PW Consulting’s full report provides (practical and operational deliverables)
-
Detailed market sizing and forecast models (2020–2032) with scenario variants reflecting demand shocks, regulatory tightening, and energy-cost sensitivity.
-
Vendor profiles and a decision-support matrix that evaluates suppliers on compliance, delivery lead time, TCO, and service network maturity.
-
Commercial negotiation playbook and contract clauses tailored to lifecycle support, spare parts availability, and performance SLAs.
-
Procurement-ready technical checklists, IQ/OQ/PQ templates, and a supplier due-diligence scorecard focused on humidity-control systems.
-
Capex planning tools including a TCO calculator and energy-performance benchmark suite to evaluate retrofit versus replacement decisions.
-
Scenario-based risk maps identifying supply-chain pinch points (critical raw materials, compressors, humidity sensors) and mitigation actions including dual-sourcing strategies and local stocking policies.
To honor the “trailer” principle: this article highlights the strategic contours and decision levers you need for 2026, but the granular segment breakdowns, regional and application-specific forecasts, and downloadable procurement templates are available only in the full Walk In Humidity Chambers Market report. Those datasets include the detailed splits, supplier scorecards, and financial models that procurement, facilities, and R&D teams will use as inputs into 2026 budgets and capital plans.
Immediate next steps for executives
-
Fast-track a multidisciplinary review (procurement, facilities, QA, and R&D) to convert strategic priorities into a 2026 capital and service plan.
-
Request vendor demonstrations that include live-data monitoring, energy consumption metrics, and maintenance logistics during bid evaluations.
-
Integrate sensor and control-system verification into supplier acceptance criteria; insist on documented calibration trails tied to ISO/ICH/FDA expectations.
-
Consider small-scale pilot purchases to validate supplier delivery, documentation, and service before committing to multi-site rollouts.
In the current cycle, the market’s steady growth masks a set of operationally critical differentiators: compliance assurance, uptime and service models, energy performance, and supply-chain resilience. Getting those elements right in 2026 will determine whether controlled-environment capabilities become a competitive advantage or a recurring risk. For a full, actionable briefing — including the segment-level forecasts, supplier rankings, and procurement tools you need to operationalize this strategy — access the complete PW Consulting Walk In Humidity Chambers Market report.
For detailed analysis of this topic, please visit the official page: Walk In Humidity Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


