



Anti-Fog Polycarbonate Market to Hit USD 282M by 2032 - PW Consulting

Anti-Fog Polycarbonate Film and Sheet Market: Strategic Outlook for 2026 Decisions
Executive preview
As companies prepare strategic plans for 2026, the anti-fog polycarbonate film and sheet market presents a mix of steady growth, concentration-driven competitive dynamics, and regulatory and feedstock-driven tailwinds that will materially affect sourcing, product development, and go-to-market choices. This introduction summarizes why a disciplined, scenario-driven approach to investments and partnerships in this segment is essential. It also explains how PW Consulting’s full study arms decision-makers with the operational frameworks, risk-mapped scenarios, and supplier-level intelligence required to act with confidence — while reserving the granular segment tables and proprietary model outputs for the full report.
Anti Fog Polycarbonate Film And Sheet Market
Where the market stands and where it’s headed
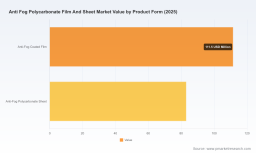
Between 2020 and 2025 the global market for anti-fog polycarbonate film and sheet expanded meaningfully, and our base-year analysis for 2025 captures a market that is now approaching the high hundreds of millions in USD revenue. Our forecast to 2032 embeds an expected multi-year expansion trajectory supported by a mid-single-digit compound annual growth rate (CAGR), reflecting persistent demand from safety/medical PPE, horticulture/greenhouse, displays, and industrial refrigeration applications. In short: growth is steady, predictable, and concentrated in a manageable set of end-markets — ideal conditions for disciplined capacity planning and targeted innovation.
Anti Fog Polycarbonate Film And Sheet Market
Market concentration is moderate: the top three global players do not yet dominate the majority of value, and the top five increase that share materially but still leave room for regional specialists and differentiated technology providers to capture pockets of premium margin. This structure creates both acquisition opportunities for scale and carve-out targets for capability-led entrants.
Anti Fog Polycarbonate Film And Sheet Market
Why 2026 is an inflection year for corporate decision-making
-
Operational cadence and timing. Several new production and fabrication capacities announced through 2025–2026 change lead times and regional supply balances. Firms that finalize partnerships or capacity commitments in early 2026 lock in advantaged service footprints for the next decade.
-
Regulatory and formulation thresholds. Recent additions to persistent organic pollutant lists and tightening chemical limits in major markets necessitate material requalification cycles. Product teams and procurement should treat 2026 as a window to validate formulations (including PFAS-free options) and secure compliant supply chains before stricter enforcement timelines take effect.
-
Input-cost signals. Volatility in polycarbonate feedstocks — driven by upstream shifts in phenol/acetone and bisphenol A pricing — will continue to pressure margins. Scenario-based procurement playbooks and hedging strategies developed now mitigate margin erosion during 2026–2028.
Practical, decision-oriented content included in the full report
PW Consulting’s full study is organized around practical outputs that executives and functional leaders can apply immediately:
-
Market sizing and demand-driver models with downloadable inputs to rerun forecasts under custom scenarios (supply disruptions, accelerated regulatory change, or demand shocks in medical PPE).
-
Supplier scorecards and capability matrices — covering technical performance of anti-fog chemistries, coating durability metrics, abrasion resistance, and long-term anti-fog lifetime claims — enabling rapid supplier shortlists for qualification pilots.
-
Commercial playbooks: pricing sensitivity maps, margin impact simulations by channel, and go-to-market templates for OEM partnerships and distribution agreements.
-
Capex decision framework: an investment checklist that translates demand forecasts into required capacity, OEE assumptions, and payback sensitivity to feedstock and regulatory scenarios.
-
Regulatory compliance checklist and reform-impact pathways, showing where reformulation will be necessary versus where supplier certifications can be fast-tracked.
These deliverables are intentionally operational: the study is more than trend commentary — it’s a toolkit to accelerate procurement, NPD, and M&A decisions in 2026.
Competitive landscape: who matters and how to engage them
The competitive map blends global commodity-scale polymers businesses, specialty sheet and coating specialists, and regional fabricators. Key players profiled in the report include leading global innovators and important regional suppliers. Each profile includes a capability assessment and transaction-ready negotiation levers — licensing, joint development, exclusive supply zones, tolling, and co-investment options.
-
POLYVANTIS (formerly SABIC Innovative Plastics) — A global technology leader with long-duration anti-fog films designed for high-humidity PPE and display environments. Their product positioning emphasizes long-term hydrophilic performance alongside impact resistance.
-
Covestro AG and Mitsubishi Gas Chemical — Two engineering-materials incumbents deploying broad polymer science and scale to serve automotive, electronics, and safety markets with anti-fog grades.
-
FSI Coating Technologies (SDC division) — Focused on durable, abrasion-resistant anti-fog coatings for visors and freezer display cases; recent innovation includes PFAS-free formulations that respond to evolving chemical restrictions.
-
Regional and specialty fabricators — Several China-based manufacturers and regional European/US sheet producers provide custom thicknesses, co-extruded multiwall panels, and localized service that remain critical to speed-to-market for OEMs and installers.
Engagement guidance: for OEM procurement teams, we recommend dual-track strategies — secure at least two qualified suppliers with different exposure to raw-material risk, and negotiate short-term exclusivity tied to volume commitments to protect product roadmaps without erecting long-term lock-ins.
Regulatory and input dynamics that will shape winners
-
Regulation: New listings and substance limits in major regulatory regimes force reformulation and new test regimens. Manufacturers with pre-validated, low-risk chemistries will accelerate into regulated segments (medical, automotive), while others will face multi-quarter relaunch costs.
-
Raw-materials: Upstream feedstock shifts materially influence cost curves. Price volatility is not a market abstraction — it is a determinative variable for margin modeling and should be simulated across stress scenarios when sizing capacity investments.
-
Trade environment: Expanded tariff and trade policy actions have added sourcing complexity. Companies with diversified procurement footprints and local conversion capability will avoid service interruptions and margin compression caused by geopolitical shocks.
Technology and sustainability: the dual front where differentiation is bought
Two concurrent themes will separate winners from laggards:
-
Performance innovation. Advances in coating durability, abrasion resistance, and hydrophilic longevity (products now claiming multi-decade performance in some settings) change warranty economics and total cost of ownership for end users.
-
Regulatory-aligned sustainability. The market is moving toward lower-impact chemistries and circular-material conversations. PFAS-free anti-fog alternatives and demonstrable recyclability are not only compliance responses but also commercial differentiators in procurement processes that increasingly weigh lifecycle metrics.
Actionable 90‑day plan for executives
-
Supply assurance: Run a supplier stress test using our baseline scenarios to identify single points of failure and secure contingency agreements that include conversion capacity or tolling clauses.
-
Product roadmaps: Prioritize reformulation or qualification of at least one PFAS‑free or low‑content chemistry for key SKUs where regulatory risk is highest.
-
Commercial pilots: Launch two co-development pilots with differentiated partners — one with a global materials innovator and one with a regional fabricator — to hedge technology and logistics risk.
-
M&A and partnerships: Use our valuation sensitives and acquisition scorecards to screen targets that offer either vertical integration (coating application) or market access (regional distribution).
Why PW Consulting’s full study matters for your 2026 planning
Executives need more than headline growth numbers; they need executable roadmaps. Our full report provides the quantitative models, supplier-level intelligence, and transaction-oriented playbooks that translate market dynamics into concrete decisions: where to build, what chemistry to adopt, who to partner with, and how to price through upstream volatility. The public snapshot you’re reading shows the strategic contours; the full study supplies the confidential tables, regional demand drivers, and segmentation economics that corporate teams will use to finalize 2026 budgets and contracts.
Next steps
For teams formulating 2026 investments, procurement strategies, or M&A pipelines in anti-fog polycarbonate film and sheet, PW Consulting’s comprehensive study is structured to be immediately operational. The final report includes the raw model files, supplier scorecards, and negotiation playbooks referenced here — essential inputs to convert market opportunity into defensible advantage. Contact our advisory desk to schedule a briefing and access the full dataset, proprietary scenarios, and supplier intelligence needed to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Anti Fog Polycarbonate Film And Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


