



PW Consulting: Targeted Multiple Myeloma Drugs Market to Reach USD 40,038.72M by 2032

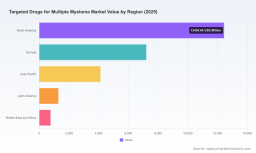
Targeted Drugs for Multiple Myeloma: Strategic Intelligence for 2026 Decision-Makers
As PW Consulting’s senior industry analyst, I present a concise but deep overview of the Targeted Drugs for Multiple Myeloma market designed to anchor executive decisions in 2026. This briefing synthesizes macro growth dynamics, competitive inflection points, regulatory and reimbursement shifts, and the practical implications for R&D, commercial strategy, M&A and manufacturing. It intentionally signals the analytical framework and decision levers you need while reserving the granular sub-segmentation tables and proprietary scenario outputs for the full report.
Targeted Drugs For Multiple Myeloma Market
Why this market matters in 2026
The multiple myeloma targeted therapies market has entered a phase of structural expansion and compositional change. After rising from roughly USD 18.5 billion in 2020 to about USD 25.85 billion in 2025, the market is forecast to grow at a compound annual growth rate (CAGR) of 6.45% through the 2026–2032 forecast window, reaching approximately USD 40.0 billion by 2032. That trajectory reflects not only continued demand for established modalities (antibodies, proteasome inhibitors, immunomodulatory agents) but also rapid adoption of next‑generation targeted constructs—bispecifics, antibody-drug conjugates (ADCs), and CAR-Ts—reshaping treatment algorithms and commercial models.
Targeted Drugs For Multiple Myeloma Market
Critically, market concentration is meaningful: the leading three companies account for a majority share of market revenues while the top five consolidate roughly three quarters of the market. This concentration creates both defensive moats and strategic openings: established players can leverage scale to accelerate combinations and label expansions, while challengers can capture niche, high-value positions via novel mechanisms or targeted partnerships.
Targeted Drugs For Multiple Myeloma Market
What’s changed in the regulatory and reimbursement landscape
- Regulatory pragmatism around surrogate endpoints: In early 2026 the FDA issued draft guidance clarifying the use of minimal residual disease (MRD) negativity and complete response as primary endpoints to support accelerated approvals in multiple myeloma trials. This aligns regulatory incentives with trial designs that are shorter and more efficient, increasing the value of candidates that can demonstrate deep, durable responses on MRD.
- Pathways to broader access: Building on analyses that link MRD to long-term outcomes, regulators and payers are more willing to accept MRD-based evidence for expedited access. Expect payer dossiers and HTA submissions in 2026–2027 to emphasize MRD-driven modeling and real‑world evidence plans up front.
- Operational de‑risking of cell therapies: Recent agency actions have streamlined monitoring requirements and removed REMS constraints for selected CAR‑T products, reflecting growing confidence in real‑world safety data. This materially reduces downstream commercialization friction and total cost of care considerations for CAR‑T providers and payers.
- Patent cliff and generic dynamics: The full generic entry of lenalidomide in the U.S. from January 31, 2026, materially alters backbone economics for many combination regimens and compels originators and competitors to accelerate lifecycle and differentiation strategies.
Key competitive inflection points (what to watch)
- Label and combination expansion: Johnson & Johnson (Janssen) continues to lead in execution—recent 2026 approvals expanded both combination and earlier-line indications for its monoclonal antibody franchises and bispecific pairings. These moves raise the benchmark for combination trials and for commercial access in earlier lines.
- Next‑generation oral agents: Bristol Myers Squibb’s positive Phase 3 readout for a next‑generation CELMoD signals that potent oral targeted agents can still shift the value equation—especially where they can be combined with proteasome inhibitors or antibodies to create all‑oral regimens with attractive clinic and payer appeal.
- Bispecifics and ADCs accelerating adoption: Players such as Regeneron, Pfizer, and GSK have secured regulatory footholds for BCMA-directed bispecifics and ADC combinations—fast adoption will depend on manufacturing scale, safety management protocols, and pricing models that reflect single‑agent vs. combination value.
- CAR‑T capacity and platform plays: CAR‑T portfolios (including collaborations and acquisitions among Gilead/Kite, Legend/Janssen and others) are shifting from proof‑point status to a commercial product class. Scale constraints and site-of-care logistics remain the gating factors; companies that secure manufacturing capacity and hub-and‑spoke care models will convert clinical wins into durable commercial returns.
Strategic implications for corporate leaders in 2026
- Portfolio prioritization: Recalibrate R&D and commercial resource allocation toward assets that can demonstrate MRD conversion and deep response durability within shorter trial timelines. For incumbents with mature franchises, prioritize label-expansion trials that pair established agents with high‑potential bispecifics or CELMoDs to defend share against biosimilars/generics.
- Launch sequencing and combination economics: Develop monetization strategies that account for evolving standard-of-care backbones post-generic entry. Pricing and contracting teams must model multiple reimbursement scenarios including indication‑based pricing, outcomes‑based agreements, and combination discounts to secure formulary placement.
- Manufacturing and supply chain: For CAR‑T and bispecific programmes, convert clinical supply investments into commercial readiness—invest in regionalized manufacturing capacity and cold‑chain logistics, and secure strategic partnerships for fill/finish to avoid launch bottlenecks.
- M&A and partnership playbook: Use targeted bolt-on acquisitions to fill technological gaps (cell therapy manufacturing, ADC conjugation expertise, bispecific platforms) while reserving larger transformational transactions for opportunities that create differentiated scale or first‑mover access to platform technologies.
- Real‑world evidence and HTA strategy: Build MRD-anchored real‑world evidence plans contemporaneous with registrational programs. Early engagement with payers to align on MRD‑based surrogate acceptance criteria will shorten the time from approval to reimbursement.
Commercial and go‑to‑market considerations
Distribution dynamics are shifting as care migrates across hospital systems, specialty clinics and, gradually, outpatient infusion/SC sites. Commercial teams should design multi-channel launch strategies that align with site-of-care economics and incorporate digital patient support models to accelerate uptake of complex regimens. For CAR‑T and other one‑time therapies, commercial value lies as much in hub network enablement and patient navigation as in list price. Payers are increasingly focused on total cost of care and durability; commercial evidence packages must quantify these dimensions.
What PW Consulting’s full report delivers (practical, actionable assets)
- Market model and scenarios: A detailed, auditable market model spanning 2020–2032 with base, upside and downside scenarios, plus sensitivity analyses on key inputs (MRD acceptance, generic entry timing, CAR‑T capacity utilization).
- Launch readiness playbooks: Step‑by‑step commercial and medical strategies for twelve launch archetypes (bispecific, ADC, oral CELMoD, CAR‑T, antibody combo), including pricing corridors, payer value dossiers, KOL maps, and phased market entry plans.
- Competitive profiles: Deep dossiers on leading companies, including pipeline maps, trial timelines, manufacturing capabilities, and partnership opportunities—scored for strategic fit and commercial impact.
- Regulatory & HTA navigation toolkit: Practical guidance for structuring MRD‑driven registrational programs, evidence generation roadmaps, and payer engagement templates tailored to regional HTA nuances.
- Commercial downside mitigation: Contract archetypes, patient support program blueprints, and manufacturing backup plans to reduce launch risk for high‑value assets.
How to use this intelligence in a 90‑ to 180‑day planning cycle
- 90 days: Re-align prioritization—identify 1–2 assets that should receive accelerated MRD‑focused registrational designs; initiate payer advisory boards to validate evidence needs; conduct a manufacturing capacity stress test for cell therapy candidates.
- 180 days: Implement commercialization frameworks—finalize launch sequencing, negotiate strategic manufacturing partnerships, and deploy early real‑world evidence pilots in high‑adoption centers of excellence.
Trailer: what’s contained but withheld here
In the interests of sparking immediate yet action-oriented decisions, this preview exposes the strategic contours and decision levers of the market but deliberately withholds detailed sub‑segment revenue tables, regional and drug‑class share breakouts, and proprietary scoring matrices that underpin our recommendations. Those granular outputs—core to investment, launch and M&A modeling—are included exclusively in the full PW Consulting Targeted Drugs for Multiple Myeloma Market report and interactive dashboards.
Final recommendation
Decision‑makers should treat 2026 as a pivot year: regulators and payers are aligning around MRD-driven approvals, generics are reshaping backbone economics, and new modalities are moving rapidly from niche to mainstream. Companies that act now—by integrating MRD into trial design, securing manufacturing and distribution capacity, and developing flexible pricing contracts tied to durability—will turn the sector’s structural growth (6.45% CAGR to ~USD 40 billion by 2032) into sustainable competitive advantage.
For the full data, granular segment tables, and the actionable playbooks referenced above, consult the complete PW Consulting report and our interactive modeling suite. Our team is available to walk executive teams through tailored scenario runs and launch readiness assessments that convert insight into near‑term action.
For detailed analysis of this topic, please visit the official page: Targeted Drugs For Multiple Myeloma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


