



PW Consulting: GTD Market to Top USD 810.26M by 2032 with 5.81% CAGR

Gestational Trophoblastic Disease Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused primer on the Gestational Trophoblastic Disease (GTD) market designed to frame boardroom and commercial-strategy conversations for 2026. This briefing synthesizes market momentum, clinical and regulatory inflection points, competitor positioning, and the practical intelligence our full report delivers — while deliberately withholding detailed segment tables to encourage direct access to the underlying dataset and model.
Gestational Trophoblastic Disease Market
Why GTD deserves a seat at your 2026 strategy table
-
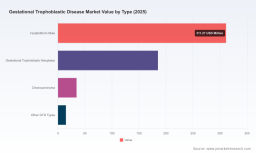
Clinically driven market growth: The GTD market has grown from a narrow specialty niche into a clearly expanding opportunity. The overall market rose from USD 412.3 Million in 2020 to USD 546.04 Million by the 2025 base year and is forecast to continue expanding, reaching USD 810.26 Million by 2032. This trajectory is supported by a forecast CAGR of 5.81% for 2026–2032, which positions GTD among steadily growing rare-oncology subsegments where incremental clinical advances translate rapidly into commercial uptake.
Gestational Trophoblastic Disease Market -
Actionable clinical levers: Recent guideline updates, new clinical data and the emergence of immunotherapy and targeted repurposing studies are shifting treatment algorithms and referral pathways. For executives, this means that late-stage clinical evidence and guideline adoption timelines — not just first-to-market approvals — will determine commercial outcomes.
Gestational Trophoblastic Disease Market -
Manageable competitive density: The market shows moderate concentration among established oncology and generics players, creating a landscape where well-positioned entrants can scale via partnerships, formulary strategies and guideline adoption without confronting extreme fragmentation or monopolistic incumbency.
Market trajectory and what the headline numbers mean for 2026 choices
From a strategic planning standpoint, the market’s compound growth and absolute scale have immediate implications for resource allocation. The mid-single-digit CAGR through 2032 indicates reliable expansion driven by steady incidence, improved diagnosis/monitoring, and the selective adoption of novel therapeutics and combinations. For 2026 planning cycles, leaders should treat the market as a growth platform that rewards:
- Focused clinical development investments that shorten time-to-guideline inclusion.
- Commercial models that prioritize guideline adoption, center-of-excellence penetration, and payer evidence generation.
- Partnerships with established oncology manufacturers and specialty distributors to bridge supply and access gaps in target geographies.
Clinical and regulatory dynamics shaping near-term commercial outcomes
Three dynamics will most strongly influence commercial trajectories in 2026 and beyond:
-
Guideline-driven uptake. The 2025 international consensus guidance from the EOTTD–ESGO–GCIG–ISSTD consortium has formally recognized avelumab as an option in certain low-risk GTN cases to avoid escalation to multi-agent chemotherapy in select settings. Guideline inclusion accelerates payer consideration and clinician adoption; companies should prioritize real-world evidence and economic modeling to convert guideline statements into on-the-ground utilization.
-
Immuno-oncology and rescue strategies. Checkpoint inhibitors (pembrolizumab, avelumab and others) are increasingly used in chemo-resistant GTN or in trials. While most checkpoint inhibitors lack indication-specific regulatory approvals for GTN as of 2026, NHS England-type recommendations and trial signals create a pragmatic pathway for off-label or directed access programs. This trend opens a practical commercial channel for manufacturers with existing immuno-oncology franchises and necessitates lifecycle strategies for label expansion or formal registration.
-
Novel modalities and repurposing. Early-stage work — such as focused ultrasound research and preclinical studies repurposing statins for choriocarcinoma — suggests potential future adjacencies beyond classic cytotoxic agents. These approaches are not yet commercialized at scale but represent strategic optionality for companies exploring platform technologies or combination regimens.
Competitive landscape: pragmatic positioning and rivalry
The GTD therapeutic environment is populated by multinational originators, established generics manufacturers, and oncology specialist players. From a competitive-mapping perspective:
-
Large originators (e.g., longstanding oncology franchises) currently benefit from brand recognition, distribution reach, and existing guideline-relevant product portfolios. Their muscle is especially pronounced where immunotherapy or branded oncology agents intersect with GTD care pathways.
-
Generics and injectable suppliers control critical access levers for cytotoxic backbones and supportive care. Supply reliability, cost management and hospital formulary relationships are decisive in settings where single-agent chemotherapy remains standard of care.
-
Specialist biopharma and academic spin-outs focusing on rare gynecologic tumors can create outsized clinical and commercial impact by delivering compelling efficacy or tolerability improvements that shift first-line practice or permit de-escalation of multi-agent regimens.
Key corporate archetypes represented among active players include: large multinational originators with immuno-oncology capability, established generic injectables manufacturers, and clinical-stage innovators testing novel combinations. Market concentration metrics indicate that a small group of companies capture a meaningful majority of commercial activity, but not enough to preclude new entrants with differentiated clinical evidence or nimble access strategies.
Recent developments that materially affect 2026 decisions
-
Clinical data — A high-profile analysis presented at the 2026 ESMO Sarcoma & Rare Cancers Congress reported an improvement in complete response rates when first-line avelumab was combined with an 8-day methotrexate schedule versus methotrexate alone in low-risk GTN. This kind of head-to-head and external-control-informed evidence will shape clinicians’ risk/benefit calculus and reimbursement conversations.
-
Guideline updates — The 2025 multi-society consensus that incorporated avelumab as a potential option in certain low-risk cases underscores how guideline language can pivot the market without awaiting conventional regulatory label changes.
-
Policy-level access — NHS England-style recommendations for checkpoint inhibitor use in refractory high-risk GTN establish pathways for targeted access programs and influence global payer evaluations, particularly in countries with centralized decision-making.
Commercial playbook for 2026
Executives should prioritize a triaged set of actions to convert the market’s growth into durable revenue streams and competitive advantage:
-
Clinical evidence acceleration: Invest in pragmatic trials and registries that align tightly with guideline committees’ evidence requirements (comparative effectiveness, hCG normalization metrics, safety in fertility-preserving contexts).
-
Guideline-first market access: Coordinate publication, consensus engagement and payer dossiers to translate guideline mentions into reimbursement pathways rapidly.
-
Supply and specialty channel optimization: For injectable and chemotherapy suppliers, secure hospital-level contracts, stock reliability assurances and educational outreach to key referrers (maternity units, gynecologic oncology centers).
-
Label-extension and lifecycle planning: For companies with checkpoint inhibitors or biologics, map out evidence strategies to move from trial/compassionate use into formal indications or strong place-in-therapy positions.
What PW Consulting's full GTD report delivers
Our complete market study translates the strategic implications above into executable deliverables for 2026 action plans. The full report includes:
-
Proprietary market model with historical (2020–2025) and forecast (2026–2032) line items, sensitivity analyses and scenario outputs you can plug into investment and portfolio models.
-
Regulatory and guideline timelines with jurisdiction-by-jurisdiction access risk scoring and payer-impact matrices.
-
Detailed competitor dossiers and capability maps — from branded immunotherapies to generic injectables — with candidate go-to-market scenarios and partner/opportunity heatmaps.
-
Actionable commercial strategies: three prioritized GTD go-to-market playbooks (originator-led, generics optimizer, and innovator entry) with staffing, evidence, and budget estimates for initial 24-month rollouts.
-
Center-of-excellence and referral network analysis identifying clinical nodes where investments in medical-education and access programs yield highest ROI.
Recommended next steps for 2026 corporate planning
-
Sponsor an evidence-acceleration workshop this quarter to align clinical, HEOR and market-access teams around priority trials and registry designs that can convert into payer-friendly endpoints.
-
Complete a short-list of partnership targets across injectables manufacturers, specialty distributors and academic centers to de-risk supply and speed center penetration.
-
Run a rapid payer-scenario simulation using our forecast model to stress-test pricing and reimbursement assumptions under alternative guideline adoption trajectories.
Closing note
The GTD market is at an inflection where focused clinical evidence and smart access strategies will create disproportionate returns for companies that act this year. PW Consulting’s full report provides the granular segmentation, modeled scenarios, and playbooks required to make those moves with confidence. For executives preparing budgets, M&A screens, or late-stage development plans in 2026, this is a market where timing, evidence design, and partnership selection will decisively shape who leads the next phase of growth.
Access the full dataset and executable appendices on our report page to unlock the segment-level detail and downloadable models that enable immediate implementation.
For detailed analysis of this topic, please visit the official page: Gestational Trophoblastic Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


