



PW Consulting: Data Center Consulting Market to Reach USD 28,417M in 2025 with 13.45% CAGR

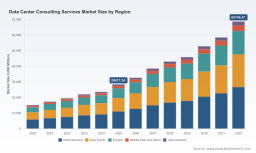
Data Center Consulting Services Market — Strategic Preview for 2026 Decision-Makers
As organizations accelerate digital transformation, artificial intelligence adoption, and hyperscale capacity builds, the global market for data center consulting services has entered a sustained expansion phase. Our new PW Consulting market study — covering historical performance through 2025 and a detailed forecast horizon beginning in 2026 — shows a multi‑year structural growth trajectory with a compound annual growth rate (CAGR) of 13.45% for the forecast period. The market crossed a significant milestone in 2025 and is projected to continue scaling meaningfully into the early 2030s.
Data Center Consulting Services Market
Why this study matters for decisions made in 2026
-
Timing capital allocation: 2026 is a year of discrete windows for committing to new build, modular expansion, or colocation agreements. Our market model translates high-level growth signals into scenario-based demand curves so CFOs and infrastructure owners can align multi-year CAPEX with realistic utilization trajectories and energy cost assumptions.
Data Center Consulting Services Market -
Optimizing operating models: Rapid changes in workload placement and hybrid architectures force choices between managed services, in‑house operations, and co-located models. The report provides TCO frameworks and migration playbooks that surface the critical breakpoints where outsourcing or retaining operations materially alters lifetime cost.
Data Center Consulting Services Market -
Mitigating regulatory and compliance exposure: New privacy laws, sectoral rules for sensitive data handling, and emissions-focused generator regulations are making compliance a design consideration rather than a box checked at the end. The research synthesizes current regulatory developments and models the operational impact on design, staffing, and contingency planning.
-
Sustainability and community license to operate: Environmental, social and governance (ESG) expectations are no longer peripheral. Investors and site hosts increasingly require biodiversity, water management and community engagement strategies embedded in project plans; the report quantifies how these practices affect project timelines and capital needs.
What the PW Consulting report delivers (practical, action-ready content)
-
Integrated market model: A calibrated topline model that links macro demand drivers to near-term capacity needs and consultant service demand across a multi-year forecast horizon. This model is accompanied by transparent assumptions and sensitivity levers for power pricing, server density trends, and utilization efficiency.
-
Decision playbooks: Step-by-step playbooks for build vs buy choices, migration sequencing from brownfield to modernized platforms, and rapid assessment templates for colocation and interconnection strategies.
-
Financial toolkits: TCO calculators, capital planning templates, and scenario-based IRR/NPV illustrations tailored to data center projects under varying energy, labor, and regulatory regimes.
-
Vendor and partner evaluation materials: Due-diligence checklists, contracting red-lines for services and construction management, and a vendor scorecard methodology that balances technical competency, delivery reliability, and sustainability credentials.
-
Operational playbooks: Staffing and skills roadmaps, maintenance and spare-parts optimization, and a practical migration & cutover checklist designed to reduce downtime risk in complex retrofits.
-
Risk register and mitigation matrices: A prioritized enumeration of technical, regulatory, and community risks with recommended mitigation actions and contingency budgets.
Note: the report contains granular segmentation by region, service type and end‑use industry and a comprehensive supplier revenue matrix. To preserve this brief’s role as a strategic preview, those granular splits and company revenue line items are intentionally withheld here — they are available in full in the published study.
Competitive landscape — how the supplier universe is shaping 2026 outcomes
The data center consulting services market remains fragmented: the top three firms account for less than one‑fifth of total market revenue, and the top five remain below 30% concentration. This fragmentation creates divergent strategic options for buyers: engage a wide ecosystem of specialists for best-in-class technical outcomes, or consolidate with a smaller set of large integrators to simplify program management.
-
AECOM and Jacobs (both with major US bases): leaders in site selection, design, and end-to-end project delivery for mission‑critical facilities. Their strengths lie in global program management, heavy civil and MEP engineering, and delivery of complex capital projects at scale.
-
Arup and Ramboll : engineering and sustainability specialists who are frequently engaged on projects where energy efficiency, architectural integration, and biodiversity/ESG outcomes are defining success criteria. Ramboll’s recent partnership to embed biodiversity into a large campus project highlights the growing demand for nature‑positive design approaches.
-
Accenture and IBM Consulting : strategy and IT transformation partners focused on cloud migration, hybrid architectures, and embedding AI into infrastructure operations. Accenture’s recent expansion of capital project delivery capabilities through an acquisition demonstrates the increasing crossover between management consulting, digital tools, and construction management.
-
Deloitte , PwC , and EY : advisory firms that combine risk/compliance, tax, and operational transformation services, and are often selected for program governance, regulatory assurance, and enterprise risk assessments tied to large-scale builds.
-
JLL : a specialist in real estate, site selection, and investment advisory. JLL’s market outlooks and campus-level capacity projections are widely used by corporates and investors to inform site strategy and land acquisition timing.
-
HCL Technologies , TCS , and Kyndryl : providers with strong heritage in managed services and infrastructure operations, positioned for long-term outsourcing contracts and run-books that capture operational knowledge at scale.
-
McKinsey & Company : a strategic advisor for C‑suite decisions around platform strategy, M&A, and large transformation programs where organizational design and future-state operating models are the primary focus.
Recent developments and regulatory dynamics that will shape 2026 playbooks
-
Capital project delivery and digital tools: Significant M&A and capability builds among major consultancies are accelerating the fusion of construction management with AI-driven planning tools. Expect shorter design cycles but greater emphasis on digital twin and construction analytics to manage schedule and cost risk.
-
Workforce and labor: Large-scale training initiatives focused on electrical trades and specialized data center skillsets are beginning to materialize. Organizations that lock in training partnerships now will reduce long-term labor premium risk.
-
Regulatory shifts: New emissions rules for backup generators in some jurisdictions and enhanced federal and state privacy controls have elevated compliance into a core project constraint. Design decisions for redundancy, emissions control, and data handling now have immediate operational and permitting implications.
-
Capacity outlook: Industry forecasts anticipate a step‑up in capacity demand over the next five years, changing the calculus for power procurement, land strategy, and grid interconnection planning. Buyers must integrate capacity scenarios into both short-term resource commitments and long-term siting decisions.
Practical 90‑day action plan for 2026
-
Conduct a regulatory impact scan focused on generator emissions, privacy obligations, and bulk data handling rules; map any near-term project milestones that might be affected.
-
Run an immediate TCO and sensitivity analysis using low/medium/high scenarios for power cost and utilization — prioritize projects where payback is most sensitive to energy price volatility.
-
Initiate or expand workforce partnerships for electrical and critical facilities trades; include apprenticeship metrics and retention KPIs in vendor RFPs.
-
Pilot a modular or prefabricated approach on a single project to compress schedule risk and test vendor integration capabilities.
-
Update procurement templates with ESG and compliance conditions, and issue an RFP to assess market pricing for integrated delivery versus specialist engagements.
Why PW Consulting’s full study is a strategic asset
The full PW Consulting Data Center Consulting Services Market study combines a rigorously validated market model, executive interviews, supplier revenue matrices, and practical implementation toolkits. It is designed to convert market intelligence into executable plans — whether you are an operator sizing next‑generation capacity, an investor evaluating campus plays, or a CISO assessing compliance exposure across a global estate.
This preview intentionally highlights the analytical framework, competitive dynamics, and decision-ready outputs while omitting the report’s granular segmentation and supplier revenue line items. For procurement-ready vendor scorecards, region- and service-level demand curves, and downloadable financial templates, please consult the full report.
PW Consulting stands ready to support your 2026 strategy session with bespoke scenario runs, stress tests of your portfolio under regulatory and energy price shocks, and hands-on workshops to operationalize the report’s playbooks into your capital planning and vendor selection processes.
For detailed analysis of this topic, please visit the official page: Data Center Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


