



Rubber Milk Tubing & Hose Market: USD 674.23M by 2032, 4.81% CAGR (PW Consulting)

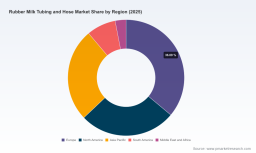
Rubber Milk Tubing and Hose Market — Strategic Primer for 2026 Decision-Making
Executive summary
By 2025 the global rubber milk tubing and hose market had matured into a stable, quality-driven segment valued at approximately USD 485.6 Million. Our baseline modelling shows the market expanding at a compound annual growth rate (CAGR) of roughly 4.81% through the forecast horizon, reaching the mid‑seven‑hundreds in USD Million by the early 2030s. Growth is steady rather than explosive; it is being shaped more by regulation, product differentiation and supply‑chain dynamics than by raw unit demand shocks. For executives planning capital allocation, product roadmaps, or M&A in 2026, the strategic questions are therefore about margin enhancement, risk management and targeted capability plays rather than broad market capture.
Rubber Milk Tubing And Hose Market
Why this study matters to 2026 decisions
-
Data‑anchored visibility: The report combines historical performance (2020–2025) with scenario‑based forecasting (2026–2032) so leaders can stress‑test operating plans against plausible price, regulation and demand trajectories.
Rubber Milk Tubing And Hose Market -
Competitive posture: Market concentration metrics reveal a fragmented but consolidating sector; three‑ and five‑firm concentration ratios indicate material room for consolidation and differentiation plays.
Rubber Milk Tubing And Hose Market -
Actionable levers: The analysis translates macro drivers into six executable levers—product quality & certification, raw material strategy, channel architecture, aftermarket services, sustainability credentials, and M&A—that procurement, R&D and corporate development teams can operationalize in 2026.
Market snapshot and trajectory
The market increased from the low‑hundreds of USD Million in 2020 to about USD 485.6 Million in 2025, reflecting steady investment by dairy processors and equipment OEMs in hygienic, durable tubing. Projections at a 4.81% CAGR to the end of the forecast period imply a market that rewards incremental innovation (better sanitary designs, longer life, traceability) and premiumization (higher value grades and certified materials) rather than basic price competition alone. This creates an environment where higher‑margin specialty players and vertically integrated suppliers can outpace commodity producers.
Key dynamics shaping 2026 strategy
-
Regulation and food‑safety as market gates
Compliance is non‑negotiable. Products must meet food‑grade standards including FDA 21 CFR 177.2600, 3‑A Sanitary Standards, NSF‑51 and relevant BfR requirements. For buyers and OEMs, procurement is increasingly a certification play: not all suppliers can rapidly demonstrate traceable material sources and validated sanitation performance. Investments in certification and hygienic design yield outsized returns in buyer preference and reduced total cost of ownership (TCO).
-
Raw material volatility and margin pressure
Raw material inputs are a continuous source of cost uncertainty. Benchmark natural rubber prices and EPDM price differentials across regions, as well as index readings such as the U.S. PPI for rubber and plastics hose, are important early signals for margin stress. In 2026, we observe downward pressure on some natural rubber benchmarks while synthetic elastomer prices remain regionally disparate—creating arbitrage and sourcing opportunities for agile purchasers.
-
Supply chain resilience and lead‑time optimization
Lead times for specialized food‑grade compounds and finished tubing are non‑trivial. Companies that establish dual sourcing for critical elastomers, lock in mid‑term contracts, or pursue near‑shoring for higher‑value SKUs will enjoy better service metrics and fewer production stoppages for dairy OEM customers.
-
Service and aftermarket as margin engines
As product lifecycles lengthen and hygiene requirements intensify, aftermarket services — scheduled replacement programs, traceability analytics, and validated cleaning protocols — become a recurring revenue source. Manufacturers with field service capabilities or distributor networks that offer bundled maintenance contracts can materially lift lifetime customer value.
-
Product differentiation through material science and design
Silicone and specialty rubber compounds that combine abrasion resistance, smooth non‑porous surfaces, and low bacterial affinity create defendable product premiums. Design choices that reduce milk retention, simplify cleaning, and extend service life will be decisive competitive differentiators in the next three years.
-
Sustainability and circularity trends
Sustainability is moving from marketing to procurement checklist. Recyclability, lower embodied carbon in compounds, and supplier transparency over supply‑chain emissions are increasingly evaluated by larger dairy processors. Early movers on certified sustainable elastomer sourcing can secure preferred supplier positions with national and international dairy chains.
Competitive landscape — strategic takeaways
The sector contains a mix of specialized, certification‑focused manufacturers and larger engineered‑polymer players. Firms with deep food‑grade expertise, documented sanitary compliance and established OEM relationships will continue to command pricing power. Key archetypes include:
-
Small to mid‑sized specialists that emphasize FDA/3‑A/NSF compliance, custom sizes and fast customer support. Their strengths are agility, niche product breadth and tight quality control.
-
Established European and multinational suppliers that offer full system solutions (milk + pulsation + air hoses) and scale advantages—especially in engineering support, logistics and multi‑jurisdictional certification.
-
OEM‑aligned producers supplying private label or integrated milking systems—where long term contracts and aftermarket parts supply underpin revenue stability.
Consolidation opportunities are visible: concentration metrics indicate meaningful share split among the largest firms but not dominant monopoly power. That creates space for strategic acquisitions (bolt‑ons for geographic reach or capability), partnerships, and selective capacity investments to secure higher margin segments.
Profiling representative competencies
-
Specialist silicone suppliers typically excel in food‑grade certifications and custom formulations. Their propositions focus on low bacterial adherence, heat resistance, and compliant materials for direct milk contact—attributes that attract processors who prioritize sanitation and product traceability.
-
Regional manufacturers often offer competitive lead times and distributor relationships within their geographies; these players can be advantageous partners for OEMs seeking localized supply and rapid engineering iterations.
-
Large industrial polymer groups bring scale in compound development, logistics and branded hoses for combined systems (milk + pulsation). They frequently lead in specification work for large dairy equipment suppliers and tanking operators.
Practical content of the PW Consulting report (what’s inside)
-
Market sizing and scenario forecasts (2020–2032) with base and alternative scenarios to quantify downside and upside outcomes.
-
Segment and channel maps highlighting where premiumization is concentrated and where unit‑volume opportunities persist (note: full segment tables and detailed regional/application splits are available in the full report).
-
Supply‑chain heatmaps and material‑price sensitivity analyses, tying rubber and elastomer price movements to margin scenarios and recommended procurement hedges.
-
Regulatory compass and compliance gap assessment tool to prioritize certifications by customer segment and geography.
-
Competitive scorecards and acquisition screening matrices for roll‑up targets, bolt‑on capabilities and partnership candidates.
-
Go‑to‑market playbooks for OEMs, distributors and manufacturers focusing on product positioning, aftermarket monetization and digital service bundling.
How senior leaders should act in 2026
-
Procurement: move from spot buying to layered contracts that combine short‑term flexibility with medium‑term price collars on critical elastomers; actively monitor PPI and regional EPDM differentials as leading indicators.
-
R&D & Product: prioritize hygienic redesigns that reduce cleaning time and milk retention; accelerate certifications that matter to large buyers (FDA, 3‑A, NSF) to reduce decision friction in procurement cycles.
-
Commercial: design aftermarket replacement programs and service SLAs that convert consumable purchases into recurring revenue; use trial programs with key processors to prove TCO improvements.
-
M&A & Corporate Development: target bolt‑ons that add certification capabilities, geographic distribution, or aftermarket service teams; prioritize targets that move CR metrics upward without overpaying for commodity scale.
-
Sustainability: evaluate low‑carbon elastomer sourcing and circular‑design pilots for high‑usage SKUs to earn procurement preference from multinational dairy chains.
Conclusion — the strategic horizon
The rubber milk tubing and hose market in 2026 rewards discipline and precision. Incremental investments in certification, supply‑chain flexibility and aftermarket services are more likely to move the needle on profitability than broad capacity expansion. The market’s steady CAGR masks meaningful pockets of opportunity for premium, compliant products and service models. Executives who integrate the six levers outlined above into their 2026 operating plans will be best positioned to capture durable, higher‑margin share.
Next steps
PW Consulting’s full study contains the complete segment tables, regional and application breakdowns, company profiles and scenario models that underpin the strategic recommendations summarized here. For procurement teams, R&D leaders, and corporate development executives preparing 2026 budgets and roadmaps, accessing the full dataset will convert directional insights into executable plans. Contact our research desk or visit the report page to download the full materials, segment‑level datasets and the tailored decision‑support workbook.
For detailed analysis of this topic, please visit the official page: Rubber Milk Tubing And Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


