



PW Consulting: Fire Retardant Additives Market to Reach $13.26B by 2032 at 4.95% CAGR

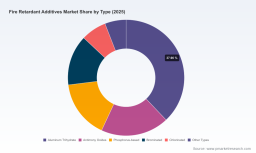
Fire Retardant Additives Market: Strategic Outlook for 2026 Decision-Makers
Executive summary
As companies prepare investment and commercial plans for 2026, the fire retardant additives market is entering a period defined by steady expansion, regulatory tightening, and material-technology rebalancing. Our base-year assessment (2025) pegs total global revenue at approximately USD 9.45 billion, with a mid-single-digit compound annual growth rate (CAGR) of about 4.95% across the 2026–2032 forecast horizon. By the end of the forecast window the market is expected to be roughly one-third larger than the 2025 base, driven by ongoing substitution toward halogen-free chemistries, rising performance requirements in electronics and transportation, and recovery in construction activity in several major markets.
Fire Retardant Additives Market
Why this matters for 2026 planning
-
Capital allocation: Forecasted mid-single-digit growth informs capacity planning and brownfield/greenfield CAPEX timing. Investors and operations teams need to weigh modest demand growth against localized raw-material and regulatory risks that can affect margins and payback horizons.
Fire Retardant Additives Market -
Product strategy: Demand is moving decisively toward non-halogenated solutions and synergistic systems. Companies that can quickly demonstrate regulatory-compliant performance while managing cost-to-formulate will capture premium share in selective applications.
Fire Retardant Additives Market -
M&A and partnerships: Market concentration metrics indicate a clear top-tier influence but meaningful room for consolidation and specialist plays. Strategic bolt-ons that fill portfolio gaps (e.g., polymeric phosphorus grades, engineered fillers, or application-specific masterbatches) remain attractive.
Market trajectory & interpretive lens
The trajectory from 2020 through the 2025 base year shows recovery and rebalancing following pandemic-era disruptions. The modest but persistent CAGR through 2032 reflects a market driven less by commoditized volume expansion and more by structural shifts: regulatory-driven reformulations, electrification and miniaturization in electronics, and higher safety specifications in building codes and automotive interiors. For 2026 decision-makers, the key inference is that revenue pools will grow, but value will cluster around differentiated chemistries, formulation services, and regulatory assurance capabilities rather than undifferentiated filler supply alone.
Key demand & supply dynamics to watch
-
Regulatory pressure is a primary near-term determinant. Recent European restrictions under chemical authorisation frameworks and jurisdictional labelling requirements in places like California have accelerated reformulation timelines for several legacy brominated and chlorinated systems. This creates both compliance costs and commercial openings for halogen-free alternatives.
-
Raw-material volatility remains elevated. Supply-side constraints and production discipline in feedstock chains have periodically pushed prices higher and tightened availability for critical inputs such as mineral fillers and bromine intermediates. Buyers will need scenario-based cost models to stress-test formulations and customer economics under price shocks.
-
Trade and tariff noise has raised sourcing complexity. Recent adjustments to import duties on certain supplier-origin products require firms to reassess nearshoring, dual-sourcing, and transfer-price impacts when constructing supply strategies for 2026.
-
Application-level demand is diversifying: electronics and electrical segments are demanding higher-performance thin-film and polymeric solutions; transportation is prioritizing low-smoke, low-toxicity systems for EV battery enclosures and interiors; construction continues to require cost-efficient, code-compliant fillers and intumescent systems. Winning requires product configurability across these distinct value pools.
Competitive landscape — what the leaders are doing
The market exhibits a moderately consolidated structure: the top three firms control a meaningful share of global revenue, while the top five capture a clear majority of market value, leaving room for specialized players to thrive. Competitive dynamics are a mix of scale-driven commodity supply and innovation-led niche plays.
-
Clariant AG (Muttenz, Switzerland) — Deep portfolio strength in phosphorus-based and halogen-free flame retardants used across plastics, textiles and coatings. Recent product introductions demonstrate a push to win polyolefin conversion projects where regulatory compliance and processability matter.
-
BASF SE (Ludwigshafen, Germany) — Strong engineering-plastics position and coatings expertise; a player to watch for integrated solutions combining char-forming intumescent systems with polymeric co-additives for high-performance applications.
-
Lanxess AG (Cologne, Germany) — Focused on phosphate esters and formulations for foams and polyurethanes; a reliable channel to mattress, furniture and insulation segments where comfort and flame safety intersect.
-
Albemarle Corporation (Charlotte, NC, USA) — Major bromine-based supplier with scale in electronics and construction materials; strategic response to bromine supply constraints and price swings will determine regional competitiveness.
-
ICL Group Ltd (Tel Aviv, Israel) — Expanding capacity in phosphorus flame retardants; a contender for wire & cable and textile markets seeking polymeric and polymer-bound chemistries.
-
Huber Engineered Materials (Atlanta, GA, USA) — Specialist in fillers such as alumina trihydrate and magnesium hydroxide; value proposition centers on technical-support-driven substitution opportunities in composites and polymers.
-
FRX Polymers (Chelmsford, MA, USA) — Innovation-led supplier of oligomeric phosphorus-based polymers targeting high-performance thermoplastics, electronics and transportation applications.
-
Thor Specialties (Speyer, Germany) — Broad, application-focused offerings for textiles and specialty papers; plays to regulated markets where certification services are important.
-
Rio Tinto (London, UK) — Upstream provider of magnesium-hydroxide feedstocks; supply economics and mine-level reliability will affect downstream margin models.
-
Dow Inc. (Midland, MI, USA) — Integrated chemicals player with synergist and additive portfolios for polyolefins and styrenics; competitive advantage where polymer-additive interaction engineering is required.
Recent corporate actions—product launches, capacity expansions, and focused new-grade releases—underscore two strategic behaviors: (1) leaders are investing selectively in halogen-free and polymeric systems, and (2) specialist vendors are leveraging technical differentiation to capture routes-to-market in electronics and transport. The market concentration statistics suggest meaningful advantages for scale players (integration, global reach) while leaving growth pathways for innovation-centric companies.
Industry headwinds and accelerants
-
Regulatory accelerants: New listings and listings-related labelling requirements have compressed acceptable chemical choices in certain jurisdictions, intensifying demand for compliant alternatives and driving testing and certification spend.
-
Supply-side headwinds: Spot supply tightness for mineral fillers and halogen feedstocks in specific quarters has increased procurement risk. Procurement teams should model dual-sourcing and inventory strategies into 2026 budgets.
-
Price dynamics: Raw-material volatility favors manufacturers with hedging, tolling partnerships, or vertically integrated feedstock access. Commercial teams should quantify pass-through elasticity across key customer segments.
What the PW Consulting report delivers — practical content for 2026 action
The full Fire Retardant Additives Market report is constructed as a decision-support toolkit for corporate leaders and investors. Key deliverables include:
-
Demand and revenue forecast models (2026–2032) with scenario sensitivity to raw-material cost shocks and regulatory adoption curves.
-
Commercial playbooks for conversion from legacy halogen systems to halogen-free and polymeric phosphorus solutions, including margin impact templates and customer negotiation levers.
-
Supplier scorecards and a vetted short-list for strategic partnerships, joint development agreements, and tolling options.
-
Regulatory impact matrices and a monitoring calendar keyed to major jurisdictions, including compliance cost estimates and reformulation lead times.
-
Detailed competitor dossiers with capability maps, recent moves, and likely next steps by product line and region (note: granular subsegment shares and confidential price schedules are reserved for full subscribers).
-
Raw-material cost models and stress tests, including contract-renewal negotiation guides and hedging options for critical feedstocks.
-
M&A target profiles and integration checklists for roll-up strategies aimed at acquiring specialty chemistries or formulation capabilities.
Seven strategic imperatives for 2026
-
Prioritize halogen-free product platforms where customer upgrade cycles and regulatory timelines align; accelerate pilot projects with top-tier OEMs in electronics and transportation.
-
Invest in formulation services and regulatory-certification capabilities as a commercial differentiator—customers increasingly value 'end-to-end' validated solutions.
-
Hedge supply risk through diversified raw-material sourcing, commercial inventory cushions for critical inputs, and selective upstream partnerships.
-
Use scenario planning to quantify margin sensitivity to commodity swings and tariff fluctuations; build price-escalation clauses into long-term contracts where feasible.
-
Explore bolt-on acquisition targets that deliver specific application know-how (e.g., thin-film phosphorus polymers, intumescent coatings, specialty fillers) rather than general scale alone.
-
Differentiate with sustainability and circularity narratives (e.g., lower-toxicity formulations, recyclability-friendly designs) that resonate with procurement teams under ESG mandates.
-
Embed rapid-response formulation teams to shorten lead times for customers facing sudden regulatory changes or component shortages.
How to use this analysis in 2026 decision cycles
For C-suite and business-unit leaders, this analysis should be treated as both a market map and an active playbook. Use the forecast and scenario outputs to set realistic capacity expansion profiles and to stress-test existing supply contracts. For product and commercial teams, the recommended playbooks will accelerate win rates in conversion projects. For corporate development, the report’s target-screening approach reduces diligence time by highlighting capability gaps and valuation sensitivities specific to flame-retardant chemistries.
Next steps — where to get the full intelligence
This introduction highlights the strategic contours you need for 2026 planning, while preserving the detailed subsegment economics, contractual templates, and confidential supplier benchmarking that power executable programs. PW Consulting’s full Fire Retardant Additives Market report contains the granular models and annexes required to operationalize the imperatives above. To access the comprehensive datasets, scenario workbooks, and vendor scorecards, please visit PW Consulting’s report page or contact our industry practice lead for a tailored briefing and sample extracts.
For detailed analysis of this topic, please visit the official page: Fire Retardant Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


