



PW Consulting: Rative Dentistry Market to grow 6.51% CAGR to USD 32.42B by 2032

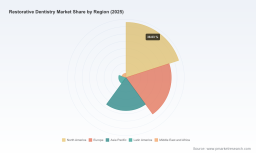
Rative Dentistry Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a succinct yet rigorous preview of our Rative Dentistry Market research — calibrated to inform board-level decisions and corporate strategy for 2026. This briefing synthesizes the macro trajectory, competitive dynamics, regulatory headwinds and practical implications executives must account for when allocating capital, designing product roadmaps, and shaping go-to-market plays. It purposefully demonstrates analytical depth while reserving the granular segment-by-segment tables and split forecasts for the full report.
Rative Dentistry Market
Why this study matters for 2026
The restorative dentistry market is on a clear growth path: our work uses 2025 as the base year and projects performance through 2032 under a structured forecasting framework. The market reached approximately USD 20.85 billion in 2025 and is modeled to expand at a compound annual growth rate of 6.51% across the 2026–2032 forecast window, reaching an expected market size above USD 32 billion by 2032. That pace points to durable volume expansion and pricing upside driven by material science advances, digital workflow penetration, and broader systemic incentives for oral health integration.
Rative Dentistry Market
For executives, this macro picture frames three enduring strategic questions for 2026:
Rative Dentistry Market
- Where on the value chain should we concentrate investment to capture the fastest-growing pockets (materials, digital systems, implants, or consumables)?
- How aggressively should we pursue inorganic growth given competitive concentration and mid-market consolidation opportunity?
- What operational changes are required to mitigate raw-material volatility and regulatory complexity while accelerating clinical adoption?
Market trajectory: what the headline numbers conceal
The headline CAGR and market totals validate that restorative dentistry remains an investable, innovation-rich segment. Yet beneath this steady growth lie three structural shifts that materially alter competitive playbooks:
- Material innovation: Next-generation bioactive composites and ion-releasing fillers are shifting clinical preference toward solutions that actively support remineralization and reduce secondary caries risk. Early launches and clinical data have begun to rebase value propositions from “fit and finish” toward demonstrable biological benefit.
- Digitalization and same‑day workflows: The maturation of CAD/CAM systems and chairside restoratives has compressed procedure timelines and increased the economic value of integrated platforms that bundle hardware, software and consumables.
- Policy and reimbursement tailwinds: Emerging incentives to integrate oral health screening into broader care pathways (for example, a new Medicare-related incentive structure in the U.S.) are creating additional referral and utilization levers for restorative services.
These forces interact: innovative materials increase procedure value, digital workflows lower delivery cost and time, and reimbursement incentives expand addressable demand. For decision-makers, the combined effect magnifies returns for strategically timed investments in product and channel capabilities.
Competitive landscape — concentrated but open to moves
The market exhibits a mid-level concentration profile: our metrics indicate that the top three players capture a meaningful share, and the top five further consolidate nearly half of market revenue. That configuration produces a landscape where global champions maintain scale advantages while a long tail of specialist and regional players create pockets of dislocation and opportunity.
- Dentsply Sirona: A global leader pairing comprehensive restorative portfolios with CAD/CAM systems and broad consumable lines. Recent product launches in bioactive composites and a solid financial outlook signal continued investment in integrated restorative solutions.
- 3M: Strong in advanced direct restorative materials and bonding systems; recognized for durable, aesthetic composites and cement technologies.
- Straumann Group: Deep expertise in implant and digital restorative workflows; recent annual disclosures emphasize digital and regenerative product launches that strengthen end-to-end restorative propositions.
- Ivoclar Vivadent, GC, Zimmer Biomet, Envista (Kerr/Nobel), and select specialist suppliers: Each holds differentiated capabilities — from high‑aesthetic ceramics and bioactive glass ionomers to implant systems and prosthetic platforms — creating a competitive mosaic where partnerships and selective M&A are logical strategic tools.
Executives facing growth or defense decisions should evaluate three levers: scale (to defend pricing and distribution), differentiation (material or digital-led), and platform orchestration (connectivity between clinics, labs and suppliers). Our qualitative and quantitative profiling in the full report maps these levers to near-term commercial outcomes, but we reserve detailed segment-level share tables for subscribers.
Operational and regulatory dynamics that will shape 2026 actions
Operational resilience matters more than ever. Key dynamics we modeled and stress-tested include:
- Raw material cost volatility: The composites supply chain is sensitive to synthetic monomer and specialty filler pricing. Procurement strategies should combine longer-term supply contracts, multi-sourcing and pass-through pricing mechanisms embedded in distributor agreements.
- Quality and compliance: ISO 13485-aligned quality management systems remain a gating item for major market access and for supporting rapid regulatory filings. Companies without robust QMS risk delayed launches and shortened commercial windows.
- Environmental and clinical standards: Policies encouraging the use of amalgam separators and the broader push toward mercury-free restorative alternatives are reshaping product developmental priorities and facility investments.
- Reimbursement & incentives: The addition of oral health incentives into broader payment programs (notably in the U.S.) creates new justification for investments in screening-enabled restorative pathways and cross-referral systems between medical and dental providers.
These operational inputs feed directly into capital allocation decisions. For example, allocating R&D spend to bioactive, fluoride-releasing or low-shrinkage chemistries should be balanced against investments in regulatory capacity and clinical evidence generation to accelerate reimbursement capture.
Practical, action-oriented outputs inside the report
PW Consulting’s full study is designed as a decision toolkit rather than a static market narrative. Key deliverables include:
- A top-down market model with scenario analyses (base, upside and downside) through 2032, enabling sensitivity testing across price, penetration and adoption curves.
- Proprietary competitive heat maps and capability matrices that score rivals on product breadth, digital integration, clinical evidence and distribution strength.
- Go-to-market playbooks for incumbents and new entrants: channel optimization, lab-clinic partnerships, and differentiated service bundles that increase lifetime value per patient.
- Regulatory and reimbursement roadmaps tailored to major markets, with tactical checklists to accelerate product approvals and payer engagement.
- M&A and partnership screening: target archetypes, valuation benchmarks, and integration risk matrices reflecting prevailing market concentration dynamics.
Each module is accompanied by executable annexes — for example, negotiation templates for supplier contracts, sample clinical economic models, and a phased rollout plan for implementing chairside CAD/CAM capabilities across multi-site clinic groups.
Investment and M&A implications for 2026
Given the market’s growth profile and concentration metrics, strategic options that consistently emerge from our analysis are:
- Build-or-buy decisions favoring bolt-on acquisitions that add a technical differentiator (e.g., bioactive chemistries or proprietary digital integration) rather than generic volume plays.
- Selective vertical integration into critical consumables to protect margins and ensure supply continuity, combined with partnerships for capital-intensive hardware.
- Portfolio optimization where firms rationalize lower-growth commodity lines to free resources for high-margin, innovation-led products and digital services.
Private equity and corporate strategists will find the market structure conducive to platform plays that combine a strong channel partner with differentiated proprietary technology; our report includes candidate profiles and diligence checklists for these opportunities.
What this preview deliberately withholds — and why
To preserve the value of the research as a strategic asset, this introduction intentionally avoids publishing the detailed regional, product-type and end-user splits that underpin our modeling and scenario outputs. Those granular split metrics — which include region- and application-level growth drivers, price elasticity estimates, and sub-segment revenue projections — are available in the full report and associated data pack. Withholding segment-level tables is intended to protect the commercial sensitivity of the analysis and to provide an incentive for stakeholders to engage directly with the full deliverables.
How to use this intelligence in your 2026 planning cycle
Leaders should treat this research as both a forecasting engine and a decision-support library. Immediate steps we recommend before committing capital in 2026:
- Run the report’s scenario models against your internal pipeline to see how product launches and pricing moves change enterprise value under conservative and aggressive adoption assumptions.
- Prioritize short-term investments in regulatory capacity and clinical evidence generation for any bioactive or novel restorative product you plan to commercialize within 18–24 months.
- Revisit procurement and hedging strategies for critical resin and filler inputs; convert spot exposures into contracted supply where possible to stabilize margins.
- Map potential M&A targets using the capability matrices in the report to identify the fastest routes to product differentiation and geographic scale.
Closing perspective
Restorative dentistry in 2026 is not a market of marginal improvements; it is a sector in which material science, digital workflows and changing care economics converge to reshape where value will accrue. The market’s steady CAGR and expanding total size create a favorable backdrop, but success will be determined by choices around differentiation, operational discipline and evidence-backed commercialization. PW Consulting’s full Rative Dentistry Market study translates these strategic imperatives into operational plans — the deeper data, segment-level forecasts, and executable annexes are contained in the report and supplementary data packs.
For boards, investment committees, and corporate strategy teams preparing 2026 plans, this preview sets the strategic frame. To access the complete market model, competitor scorecards, and tactical playbooks referenced here, please consult PW Consulting’s full research release.
For detailed analysis of this topic, please visit the official page: Rative Dentistry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


