



PW Consulting: Zellweger Spectrum Disorders Market to Reach USD 493.39M by 2032 at 6.72% CAGR

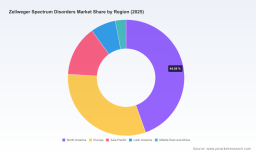
Zellweger Spectrum Disorders Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s targeted industry briefing introduces the Zellweger Spectrum Disorders (ZSD) market as an emergent, specialty rare-disease segment where near-term commercial decisions will determine mid-decade winners and platform owners. Our market model indicates a clear, evidence-backed growth trajectory (compound annual growth rate of approximately 6.7% across the 2026–2032 forecast window) from a mid-2020s baseline to a materially larger market by the end of the decade. This growth reflects a mix of continued uptake of approved adjunctive therapies, expansion in diagnostic capture, and the accelerating probability of disruptive gene-editing and genetic-medicine interventions progressing through preclinical and clinical pipelines.
Zellweger Spectrum Disorders Market
Why this matters for 2026 strategy
-
Timing and option value: With the field still dominated by a small number of commercial incumbents and diagnostic service providers, 2026 is a pivot year for strategic investments — defined by whether organizations will lock in access to diagnostic funnels, secure payer visibility, or position for future disease-modifying entrants.
Zellweger Spectrum Disorders Market -
Capital allocation and portfolio sequencing: The market’s steady expansion at ~6.7% CAGR forces a re-evaluation of R&D prioritization versus near-term commercial plays (diagnostics, supportive care, and adjunctive bile acid therapies). Firms must balance investment in incremental product improvements and distribution leverage against optionality for transformative therapies coming from gene- and base-editing research.
Zellweger Spectrum Disorders Market -
Payer and access dynamics: Payers are already forming expectations around cost-effectiveness for adjunctive therapies and diagnostics, while preparing frameworks for one-time or high-cost gene therapies. How companies engage with payers in 2026 will materially affect launch dynamics for any novel disease-modifying agent.
Market architecture — what the full report models (high level)
Our full study applies a multi-layered market architecture combining epidemiology, diagnosis rates, therapeutic uptake curves, and unit economics to produce forward-looking revenue scenarios. The report contains:
-
A rigorous epidemiology module calibrated to published incidence and newborn-screen adjustments, with sensitivity cases for regional clustering (e.g., documented founder populations) and improved diagnostic penetration.
-
Diagnosis and patient flow modelling that links genetic and biochemical testing capacity to patient identification, with explicit assumptions on diagnostic yield and referral capture over time.
-
Therapeutic adoption curves segmented by product type (adjunctive bile acid therapy, symptomatic/supportive treatments) and end-user channels (hospital, specialty clinic, homecare), with transparent assumptions and alternative scenarios for accelerated approval or limited indication expansions.
-
Payer pathway and pricing architecture that evaluates reimbursement levers, co-pay dynamics, and real-world evidence requirements.
-
Commercial opportunity maps and channel strategies for market entry, expansion, and loyalty programs focused on clinicians, genetic counselors, and center-of-excellence networks.
Note: this briefing intentionally omits granular split tables and regional/unit amounts that are included in the full report; these are provided to subscribing clients to preserve competitive discretion.
Clinical and R&D landscape — near-term inflection points
The clinical landscape today is defined by an established adjunctive treatment for hepatic manifestations and an ecosystem of diagnostic and supportive care. Key dynamics shaping near-term strategy:
-
Established standard: An FDA-approved adjunctive cholic acid product remains the only marketed therapy specifically indicated for certain liver manifestations tied to peroxisomal disorders. Its continued commercial availability and guideline reaffirmation have stabilized a baseline addressable market for treatment of liver-related morbidity.
-
Transformational science: Cutting-edge genome editing—illustrated by recent preclinical base-editing correction of a common PEX1 mutation in animal models—raises the probability of future curative-class interventions. These advances will compress timelines for strategic planning: companies must build optionality today (partnerships, manufacturing readiness, payer engagement) to capture asymmetric upside if therapies translate clinically.
-
Unmet needs beyond the liver: No therapies as of 2026 have established safety and effectiveness for extrahepatic manifestations, making neurometabolic and developmental outcomes a critical area for differentiation and long-term value creation.
Competitive landscape — positioning and implications
The competitive ecosystem combines a few commercial product sponsors with a broader array of diagnostic and platform players. From our strategic vantage point, three archetypes drive market dynamics:
-
Therapeutic incumbents that own approved adjunctive treatment and clinician mindshare. These organizations have monetized the hepatic treatment niche and built distribution and reimbursement relationships that create near-term barriers to entry.
-
Diagnostic and platform providers whose genetic panels and testing services act as the primary funnel for identifiable patients. Their role in accelerating diagnosis—and therefore treatment initiation—gives them outsized influence on capture rates and real-world outcomes data.
-
Emergent science leaders (academic and biotech) developing gene-editing and precision-medicine approaches that could reframe disease economics and payer willingness to fund high-cost, one-time interventions.
Representative organizations featured in our competitive matrix include established therapeutic sponsors, genome diagnostics firms, and life-science tools companies that support the testing and clinical workflows. Each entity’s core competency (commercial reach, diagnostic coverage, platform-readiness) is mapped to tactical playbooks in the full report — enabling readers to prioritize partnerships, licensing, or bolt-on M&A that accelerate pathway control.
Commercial dynamics and payer strategy
Commercial success in ZSD will require a three-pronged approach:
-
Capture diagnostics: Align with genetic testing labs and newborn-screen expansion advocates to reduce diagnostic delay and increase the addressable treated population.
-
Evidence generation: Invest early in real-world evidence and registry infrastructure that demonstrates long-term hepatic and extrahepatic outcomes, cost offsets, and quality-of-life benefits; anticipate payer demand for outcome-based agreements.
-
Channel optimization: Design differentiated go-to-market approaches for tertiary centers, specialty clinics, and homecare support services; leverage telehealth and genetic counseling to extend reach while controlling costs.
M&A, partnerships, and manufacturing considerations
Given the concentrated nature of commercial activity and the rising prospect of gene-editing therapeutics, corporate development strategies should be selective and scenario-driven. The full study includes a prioritized list of inorganic targets and partnership archetypes mapped to three strategic objectives: near-term revenue capture, diagnostics funnel control, and platform readiness for curative therapies. Manufacturing readiness — particularly for specialty formulations and, later, viral or non-viral vectors — is a gating factor for large-capacity moves and should be evaluated against likely regulatory and payer timelines.
What PW Consulting’s full report delivers (practical takeaways)
-
Action-oriented financial models: downloadable Excel with base case, optimistic, and conservative scenarios; transparent assumptions you can tweak to test your strategic options.
-
Market-entry and partnership playbooks: step-by-step approaches for diagnostics companies, therapeutics sponsors, and clinical service providers.
-
Payer-engagement templates: evidence dossiers, budget-impact models, and suggested outcome-measure bundles tailored to different health-system archetypes.
-
Regulatory and clinical milestones calendar: tracking preclinical advances and guideline updates that will reset commercial timelines.
These deliverables are designed to move leaders from analysis to decision (license, invest, partner, or wait) within a 90–180 day planning horizon.
Immediate recommendations for 2026
-
Diagnostics-first strategy for commercial teams: negotiate prioritized access to testing panels and build joint physician education programs to accelerate diagnosis-to-treatment time.
-
Payer-focused evidence generation: sponsor pragmatic registries now to capture hepatic and extrahepatic outcomes; structure data collection to support potential outcomes-based contracts for future high-cost interventions.
-
Option value preservation: secure collaboration options with gene-editing and vector-development groups rather than full M&A if capital is constrained; preserve flexibility to scale if clinical translation occurs.
-
Commercial readiness: ensure cold-chain, specialty pharmacy relationships, and center-of-excellence networks are in place to support potential rapid expansion of treated populations.
Closing — the strategic opportunity
The ZSD market presents a classic rare-disease strategic paradox: steady, cash-generating near-term pathways co-exist with high-impact optionality from potential future curative therapies. PW Consulting’s analysis shows a materially growing addressable market over the 2026–2032 period, underpinned by diagnostic momentum and incremental therapeutic uptake. However, the true inflection point will be set by the clinical translation of gene-editing approaches and the payer frameworks that follow—events for which companies must prepare now.
For clients seeking the complete dataset, granular segmentation (regional, product-type, and end-user splits), and the tactical playbooks required to act in 2026, PW Consulting’s full Zellweger Spectrum Disorders Market report and interactive model are available on our research portal. Access to the complete materials will enable you to move from strategic intent to executable plans with clarity and confidence.
For detailed analysis of this topic, please visit the official page: Zellweger Spectrum Disorders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


